

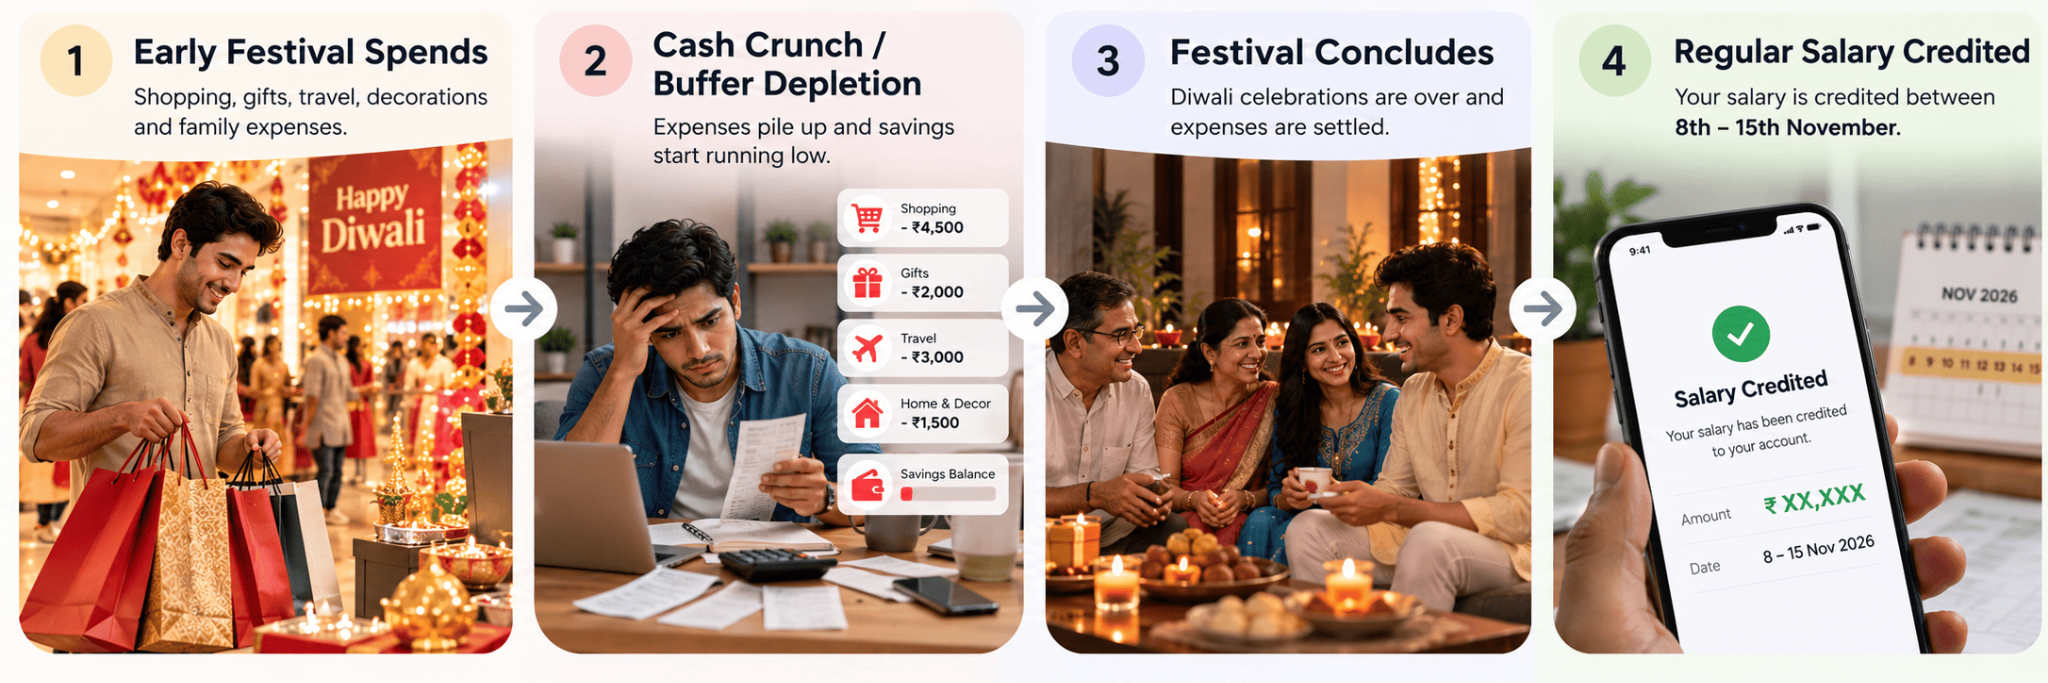
If you are paid after Diwali, you are facing one of the most common cash flow challenges in India your highest expenses for shopping, traveling, and gifting are right before you get your paycheck in your bank account. Taking up debt on high-cost cards or using unbudgeted reserves may lead to a long term worry. Temporary festive crunch, Pocketly will help salaried professionals, freelancers and young earners with small ticket digital credit lines starting from ₹1,000 and up to ₹50,000 that are sanctioned transparently by our RBI registered NBFC partner Speel Finance Company Private Limited.
Managing Expenses When Payday Falls After the Festival
|
Core Scenario |
The Practical Challenge |
Responsible Financial Fix |
How Pocketly Can Help |
|
Salary Credit Delayed |
Major Diwali expenses occur before payday arrives. |
Prioritize mandatory festival purchases; defer non-essentials. |
Explore our personal loan for salaried applicants for short-term support. |
|
Gifting & Travel Spikes |
Train/flight tickets and family gifts deplete living buffers. |
Cap travel and gift budgets using strict spending envelopes. |
Access flexible lines of credit with clear 61-day to 9-month terms. |
|
Irregular Inflows |
Freelancers face delayed invoice clearances in late autumn. |
Plan on base-month cash flow rather than peak expectations. |
Check our personal loan for self employed individuals. |
|
College / First Job |
Festival contributions strain limited monthly pocket money. |
Track daily micro-spends and avoid unverified quick cash apps. |
Review our personal loan for non salaried borrowers. |
What Does a "Salary After Diwali" Squeeze Mean?
A salary after Diwali squeeze happens when the festive calendar places Dhanteras, Diwali, and Bhai Dooj in late October or early November, while employer payrolls remain fixed to the end of the month or early the following month.
During this period, households encounter heavy festive expenses including festive attire, home renovation, electronic upgrades, sweets, gold purchases, and holiday transit tickets. When your paycheck arrives only after the festival concludes, you must secure money before Diwali without draining core emergency funds or accumulating costly penalties.
How Does Pre-Festive Cash Flow Timing Work in India?
Festival planning in India requires managing uneven cash outflows against rigid income dates. When expenses hit all at once, workers often search for a salary before payday solution.
To resolve short-term financial needs without distress, you should understand how different funding sources operate:
-
Planned Savings Pools: Drawing from earmarked seasonal savings prevents any need for borrowing.
-
Short-Tenure Digital Personal Credit: An unsecured micro-loan offers predictable repayment terms over fixed months rather than compounding indefinitely.
-
Credit Card Revolving Debt: Swiping cards without an immediate plan to clear the balance in full can trigger heavy finance charges (often 36% to 49% APR) and retroactive interest.
Institutional Bank Loans vs Instant Personal Loans on Pocketly
Traditional personal loans from public or private sector banks are typically built for large, long-term borrowing, making them ill-suited for small festive cash crunches. The table below highlights the operational differences:
|
Evaluation Factor |
Traditional Bank Personal Loan |
Pocketly Digital Personal Loan |
|
Minimum Ticket Size |
Usually ₹50,000 to ₹1,00,000 |
Micro-ticket friendly: ₹1,000 to ₹50,000 |
|
Documentation Mode |
Physical branch visits, Form 16, hard copies |
100% paperless digital onboarding via smartphone |
|
Processing Duration |
3 to 7 business banking days |
Fast automated underwriting and rapid bank transfer |
|
Collateral Requirements |
Zero collateral, but strict income cutoffs |
100% unsecured; no pledge or guarantor required |
|
Lending Entity |
Direct Commercial Bank |
Speel Finance Company Private Limited (RBI-registered NBFC) |
|
Ideal Use Case |
Large home remodeling or multi-year consolidation |
Short-term cash bridge while awaiting your monthly salary |
Who Is Eligible to Apply for Credit Before Diwali?
At Pocketly, our eligibility criteria ensure that young earners and salaried workers overlooked by traditional banking institutions can access credit safely.
-
Nationality: Resident Indian citizen.
-
Age Bracket: Between 18 and 40 years.
-
Income Source: Regular monthly cash inflow (full-time salaried employment, freelance earnings, or a consistent monthly bank allowance).
-
Banking Setup: An active Indian savings bank account enabled for digital payments.
-
Credit Score Policy: A CIBIL score is not mandatory to initiate an application with us; underwriting evaluates transactional cash flow consistency alongside KYC verifications.
Documents and KYC Requirements
Because Pocketly operates a fully digital process, you never have to visit a physical office or submit physical photocopies.
-
Identity Verification: Valid PAN card number.
-
Address Verification: Paperless digital address check via Aadhaar.
-
Visual Verification: A quick in-app Video KYC session.
-
Account Setup: Active savings bank account details for direct fund credit and repayment scheduling.
Step-by-Step: How to Bridge Festive Cash Crunches on Pocketly
Getting an instant personal loan on Pocketly is fast and structured:
-
Download the Official App: Install Pocketly from Google Play or the App Store.
-
Create Your Account: Register with your active mobile number and complete the one-time password (OTP) verification.
-
Submit Paperless Verification: Input your PAN and Aadhaar details to verify your identity, then finish the short Video KYC.
-
Select Amount & Duration: Choose a borrowing limit between ₹1,000 and ₹50,000 with a repayment tenure ranging from 61 days to 9 months.
-
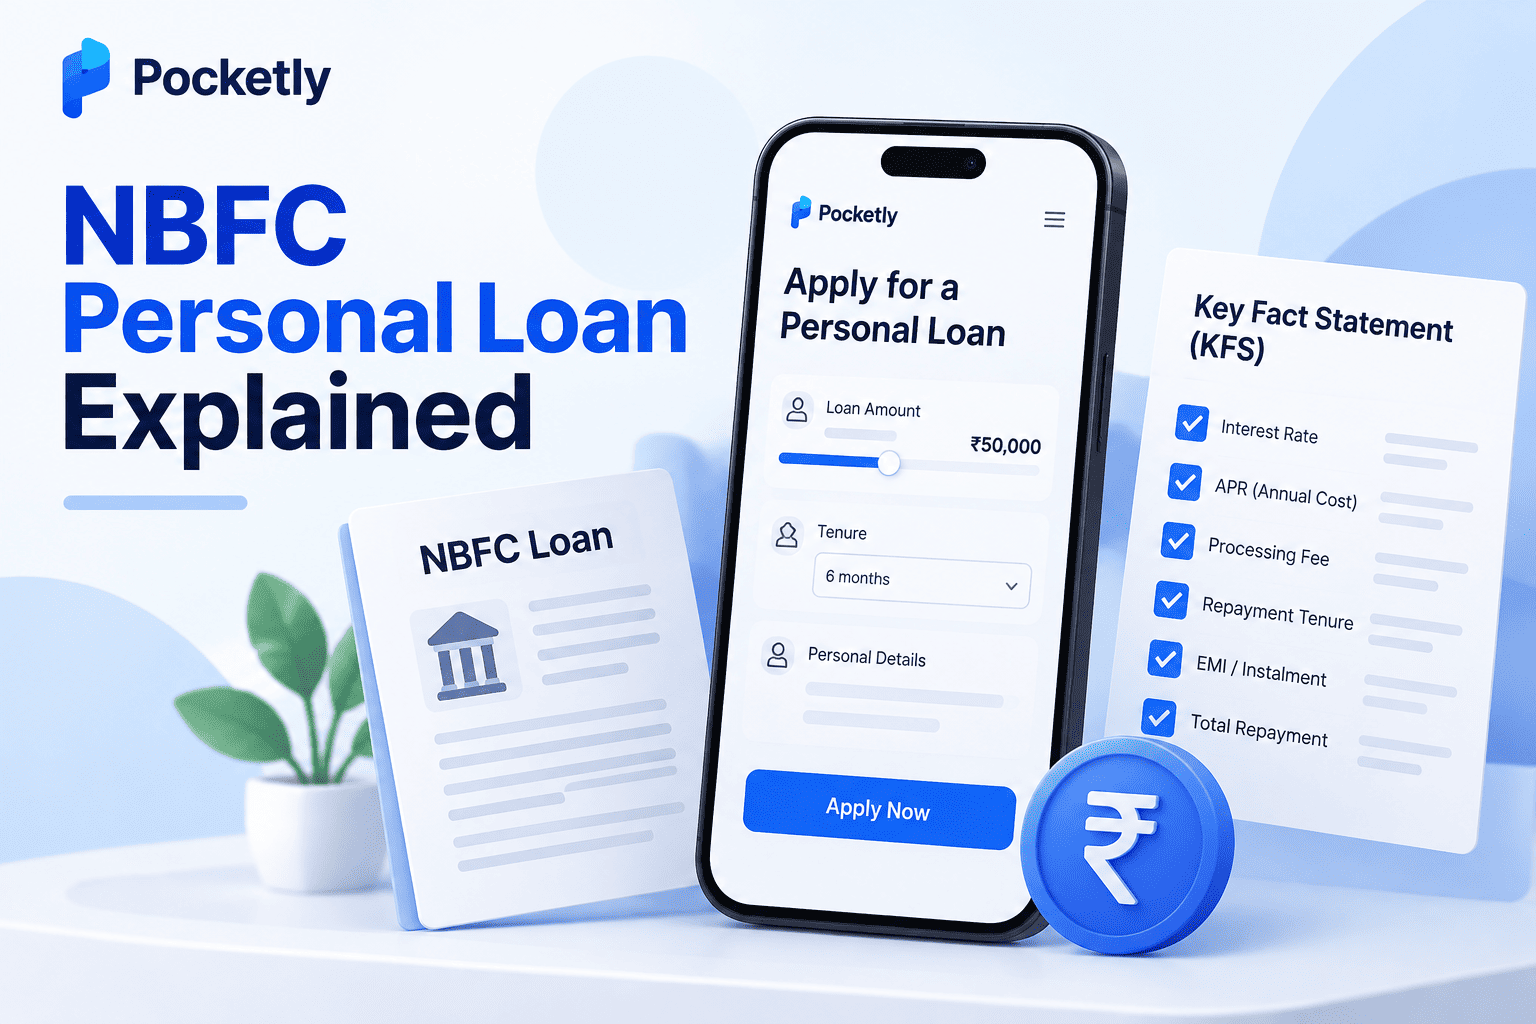
Inspect the Key Fact Statement (KFS): Review the full breakdown of your monthly interest, processing fees, net credit amount, and Annual Percentage Rate (APR).
-
Direct Bank Transfer: Once underwriting checks are finalized, approved funds are credited straight into your bank account.
Costs, Interest Rates, and Repayment Terms
Borrowing must always remain responsible and transparent. In accordance with our Responsible Lending policy and Reserve Bank of India (RBI) digital lending guidelines, we disclose all borrowing costs upfront:
-
Monthly Interest Rate: Between 2% and 3% per month, depending on underwriting evaluation.
-
Processing Fees: Between 0% and 9.4% (inclusive of applicable 18% GST).
-
Annual Percentage Rate (APR): Capped between 30% and 99.73% (up to 121% across specialized products), reflecting the total cost of credit including fees and taxes.
-
Loan Repayment Tenure: Flexible durations from 61 days up to 9 months.
-
Early Foreclosure: 2.5% of the outstanding principal balance if settled early; evaluate your interest savings using our loan foreclosure calculator.
Illustrative Festive Cash Bridge Repayment (₹5,000 Loan)
|
Loan Parameter |
Illustrative Figures |
|
Principal Borrowed |
₹5,000.00 |
|
Repayment Tenure |
90 days (3 months) |
|
Annualized Interest Rate |
36% p.a. (3% per month) |
|
Processing Fee + 18% GST |
₹425.00 |
|
Net Amount Disbursed |
₹4,575.00 |
|
Estimated Total Interest |
₹302.96 |
|
Monthly Equated Instalment (EMI) |
Approx. ₹1,767.65 per month |
|
Total Amount Repaid |
₹5,302.96 |
|
Total Cost of Credit |
₹727.96 |
(Note: The above calculation is purely illustrative. Final sanctioned limits, interest charges, and fee deductions depend on underwriting criteria and are outlined on your personalized Key Fact Statement. Test your custom numbers with our free personal loan EMI calculator before borrowing.)
Tailored Borrowing Options Built for Your Income Stream
Income arrangements differ across India. At Pocketly, we have created specific borrowing paths suited to different career profiles:
-
For Full-Time Salaried Employees: If festival celebrations drain your wallet a week before payday, evaluate our personal loan for salaried applicants to cover timely obligations.
-
For Small Business Owners & Freelancers: Independent professionals dealing with seasonal festive trade spikes can explore our personal loan for self employed tier.
-
For Students & Gig Economy Earners: Young adults receiving pocket allowances or freelance project payouts can access structured support through our loan for non salaried category.
What Should You Check Before Taking a Loan?
When shopping pressures tempt you to take quick credit, review these fundamentals first:
-
Verify the Regulated Underwriter: Never borrow through unauthorized APKs. All credit through Pocketly is underwritten and disbursed by Speel Finance Company Private Limited, an RBI-registered NBFC.
-
Review the Full APR, Not Just Interest: Check the Key Fact Statement to verify the true borrowing cost including processing charges and GST.
-
Assess Your Monthly Debt-to-Income: Keep your total monthly debt payments under 40% to 50% of your net pay. Calculate your commitments with our FOIR calculator or budget your festive expenses using our 50 30 20 Rule Calculator.
-
Understand Application Speeds: Searching for an "instant personal loan online in 2 minutes" reflects our fast, paperless onboarding flow, not an exemption from automated underwriting and KYC checks.
-
Identify the Best Loan App in India: When comparing apps, review partner NBFC credentials, KFS transparency, fair recovery guidelines, and ISO 27001 data security compliance rather than misleading marketing slogans.
Common Festive Spending Mistakes to Avoid
-
Overspending on Celebrations: Borrowing beyond your means for non-essential purchases leads to prolonged post-holiday debt stress. Read our guide on Lifestyle Inflation: Why Higher Income Does Not Always Mean More Savings to stay grounded.
-
Falling for Unregulated 7-Day Schemes: Fraudulent lending apps promise unconditional cash advances, only to demand predatory upfront fees and use abusive recovery methods. Learn how to protect your finances by reading 7 Days Loan vs 30 Days Loan: Interest, Charges & Repayment.
-
Ignoring EMI Due Dates: Delays harm your credit history and attract late charges. If you foresee cash flow difficulties, review our advisory on Loan Ki Kissht Nahi Bhar Pa Rahe? EMI Late Hone Par Kya Hoga? to take the right steps early.
-
Borrowing Without Budgeting for Inflation: General price rises make festival gifts and essentials costlier. Read our analysis on Why Do People Take Personal Loans During Inflation? to understand disciplined credit habits.
Plan Your Festive Budget Wisely with Pocketly
A festive cash crunch does not have to spoil your Diwali celebrations. By organizing your expenses early, verifying all borrowing costs on your Key Fact Statement, and keeping your debt within comfortable limits, you can manage pre-festive expenses with confidence.
Frequently Asked Questions (FAQs)
What should I do if my salary arrives after Diwali?
If your salary lands after Diwali, make a prioritized list of essential festival expenses, hold off on discretionary splurges, and utilize a transparent, short-term micro-loan to bridge urgent outlays until payday.
Can I get money before Diwali with Pocketly?
Yes, eligible borrowers can apply for personal loans between ₹1,000 and ₹50,000 through the Pocketly app to manage urgent festival expenses.
Can I get an instant personal loan online in 2 minutes?
You can complete our digital application in just a few minutes, but loan approvals and disbursals depend on real-time KYC validation and credit underwriting. We do not provide unverified or automatic approvals.
How do I estimate my monthly repayments before taking a festive loan?
You can test different loan amounts, tenures, and interest rates using our free personal loan EMI calculator to see your exact repayment obligations upfront.
Can salaried professionals use Pocketly to manage salary delays?
Yes, salaried employees who need a short-term cash bridge before payday can apply via our personal loan for salaried category.
Can self-employed individuals apply for a festive loan?
Yes, freelancers, consultants, and business owners can explore our personal loan for self employed profile to manage holiday working-capital crunches.
Can non-salaried earners and students qualify for credit on Pocketly?
Yes, individuals with regular allowances or gig income without conventional corporate pay slips can evaluate our personal loan for non salaried options.
What factors help identify the best loan app in India?
When evaluating the best loan app in India, look for partnerships with RBI-registered NBFCs, clear Key Fact Statements, transparent APR caps, fair recovery practices, and responsive grievance channels.
How does repaying a Pocketly loan affect my credit score?
Repayments are reported to Indian credit bureaus by our regulated lending partner, Speel Finance Company Private Limited. Clearing your EMIs on time helps build a strong credit track record, while missed payments lower your score.
Can I repay my festive loan early?
Yes, early foreclosure is permitted at any time. A standard 2.5% foreclosure fee applies to the outstanding principal balance.