

Fastest Way to Get a Personal Loan Disbursed in India (2026 - 2027)
Need ₹5,000 for an urgent bill? Waiting for your salary? Or did an unexpected medical, travel or household expense suddenly appear?
When money is needed quickly, most people don't want to spend days visiting a bank and filling out forms. They want to know the fastest way to get a personal loan and how soon the money can actually reach their bank account.
In 2026, digital lending has made this much easier. You can apply for an instant personal loan online, complete KYC digitally and check your eligibility without following a traditional branch-based process.
At Pocketly, we have built our personal loan journey around this need for speed and simplicity.
But there's something every borrower should understand:
Fast approval and fast disbursal are not the same thing.
What Is the Fastest Way to Get a Personal Loan?
The fastest way to get a personal loan is generally to choose a 100% digital loan process, keep your PAN, KYC and bank information ready, provide accurate details and complete verification without delay.
Digital processing can reduce waiting time, but fast personal loan approval still depends on eligibility, verification and underwriting.
How Fast Can a Personal Loan Be Disbursed?
Your personal loan disbursal time depends on more than the application form.
Here's what normally happens:
|
Step |
What Happens |
|
1. Apply |
Enter personal and financial information |
|
2. KYC |
Complete identity verification |
|
3. Eligibility |
Application is assessed |
|
4. Approval |
Eligible loan offer is generated |
|
5. Review |
Check interest, APR, fees and tenure |
|
6. Agreement |
Accept applicable loan terms |
|
7. Disbursal |
Approved amount is transferred |
The important difference is between instant approval and instant cash. Approval means your application has cleared the required assessment. Disbursal means the approved funds have actually been transferred.
7 Ways to Get a Personal Loan Faster in 2026 - 2027
1. Keep Your PAN and KYC Information Ready
One of the easiest ways to avoid delays is to prepare before applying.
Keep these details ready:
-
PAN
-
Aadhaar/address information
-
Mobile number
-
Email ID
-
Bank account details
-
Income information, where required
-
Details needed for video KYC
If you're searching for a PAN card loan online, remember that PAN is part of identity and financial verification. It does not mean a lender will provide a loan based on a PAN card alone.
2. Choose a 100% Digital Application
The biggest advantage of online loans vs traditional loans is convenience.
A digital journey can remove several manual steps. Instead of travelling to a branch, eligible borrowers may be able to apply, complete KYC, review the loan offer and finish documentation through their phone.
For young borrowers dealing with a short-term cash shortage, this can make a major difference.
Why Consider Pocketly for a Quick Personal Loan in India?
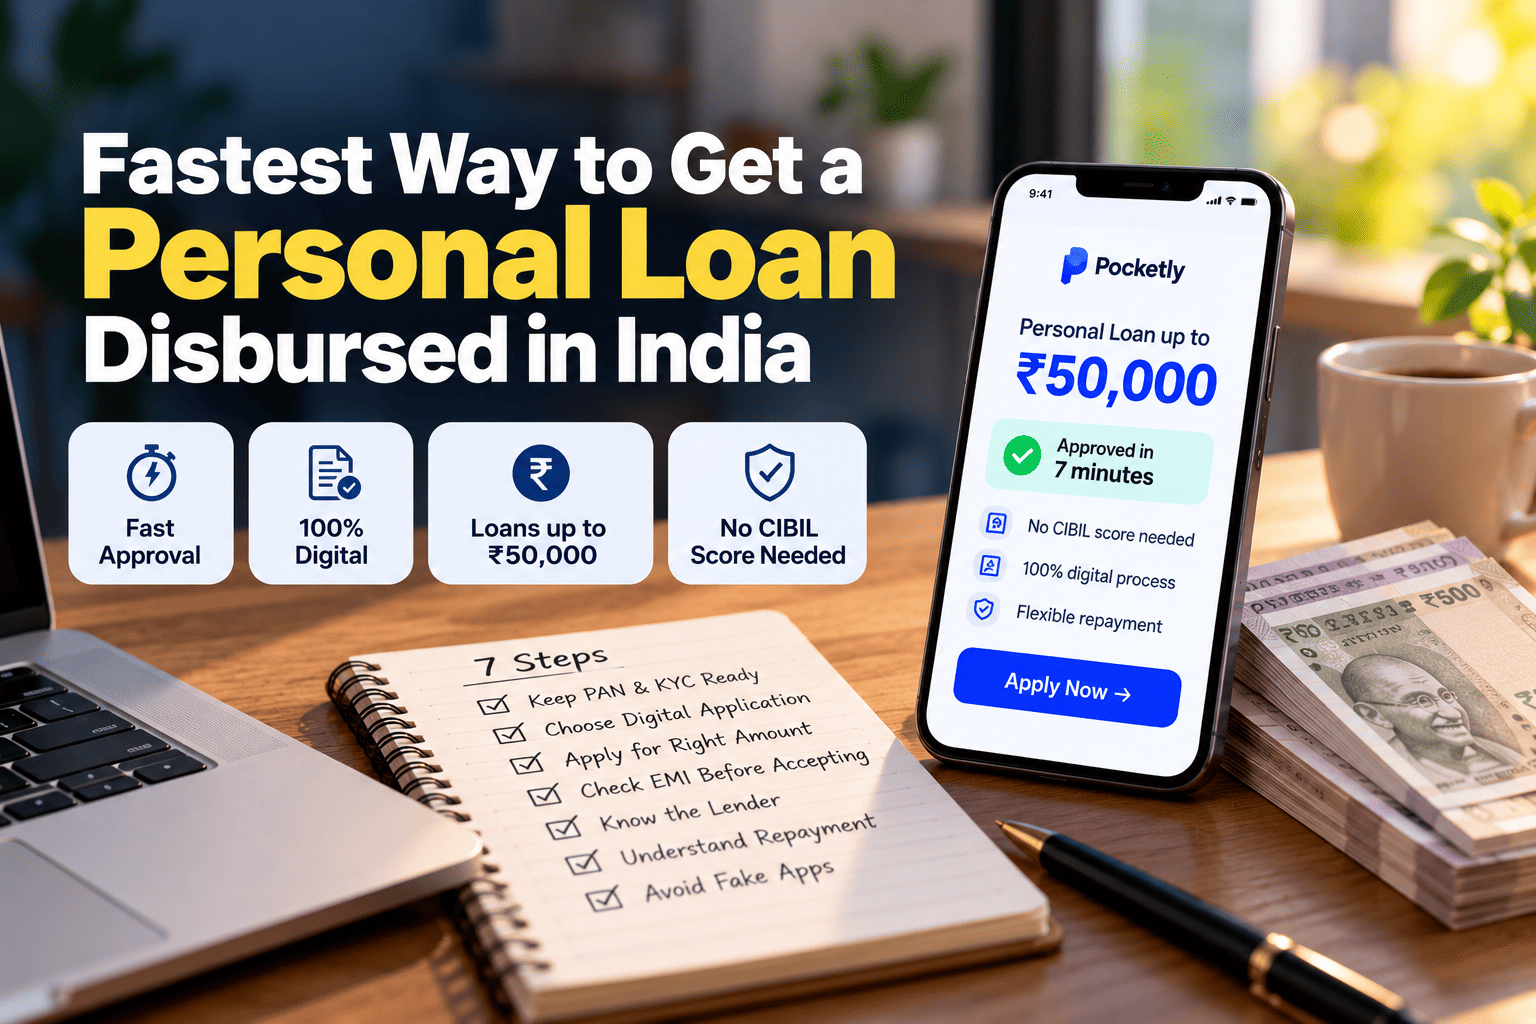
Pocketly is built for young India, including eligible first-jobbers, salaried professionals, freelancers, self-employed borrowers and other eligible applicants looking for smaller personal loans.
With Pocketly, eligible borrowers can access:
-
Personal loans from ₹1,000 to ₹50,000
-
100% digital application journey
-
Minimum KYC
-
No collateral
-
No CIBIL score requirement to apply
-
Flexible repayment options
-
Fast digital processing
-
Direct bank disbursal after approval
Pocketly states that a loan request can receive approval processing within a maximum of 7 minutes, subject to eligibility and assessment.
That doesn't mean every applicant receives money in seven minutes. Approval, eligible amount and instant personal loan disbursement depend on successful verification and applicable lending criteria.
3. Apply for the Amount You Actually Need
Suppose you urgently need ₹5,000.
Borrowing ₹30,000 simply because a higher amount is available may create an unnecessary repayment burden.
Whether you are considering an instant loan of ₹5,000, a mini cash loan or a larger personal loan, start with the actual expense.
Ask yourself:
-
How much do I really need?
-
What EMI can I comfortably afford?
-
What is the repayment period?
-
What is the total repayment amount?
-
What other EMIs do I already have?
Different types of personal loans may suit different needs, including medical expenses, education, travel, household expenses or other short-term requirements. The right amount matters more than the maximum amount available.
4. Check Your EMI Before Accepting the Loan
Getting a same day personal loan disbursement is useful only if you can comfortably repay it.
Don't check only the monthly EMI.
Check the complete cost.
|
Loan Detail |
Why Check It? |
|
Loan amount |
Know what you're borrowing |
|
Interest rate |
Understand interest cost |
|
APR |
Compare overall annualised borrowing cost |
|
Processing fee |
May affect loan cost |
|
GST |
May apply to relevant charges |
|
Tenure |
Determines repayment period |
|
EMI |
Must fit your budget |
|
Total repayment |
Shows what you'll ultimately pay |
Pocketly currently publishes general loan amounts of ₹1,000–₹50,000, repayment periods of 61 days to 9 months, interest of 2%–3% per month and processing fees of 0%–7.5% plus applicable GST.
Before accepting an offer, use a personal loan EMI calculator and review the applicable Key Fact Statement.
A lower EMI does not automatically mean a cheaper loan. Longer repayment periods can change the total borrowing cost.
5. Don't Assume a Low CIBIL Score Means No Options
Another common question is:
How much CIBIL score is good to get a personal loan?
There isn't one score that guarantees approval everywhere. Lenders have different eligibility and underwriting criteria.
Even someone searching for an NBFC personal loan for bad credit should understand that a low score does not automatically guarantee approval or rejection. Income, current obligations, verification, credit history and lender-specific assessment may also matter.
Pocketly states that a CIBIL score is not required to apply through its platform.
However:
No CIBIL score required ≠ guaranteed loan approval.
Eligibility and verification still apply.
6. Know Who Is Actually Lending the Money
Before choosing any quick personal loan in India, look beyond the app's logo.
Ask:
Who is the actual lender?
An NBFC personal loan is a personal loan provided by a Non-Banking Financial Company rather than a traditional bank.
At Pocketly, personal loans are lent by Speel Finance Company Private Limited, an RBI-registered NBFC, through the Pocketly technology platform.
This distinction is important when people search for RBI approved loan apps. Rather than relying only on the phrase “RBI approved”, borrowers should verify the regulated lender associated with the app, along with the KFS, APR, fees and repayment terms.
7. Avoid Fake “Instant Approval” Offers
Urgency can make borrowers easier targets for scams.
Be careful if someone promises:
-
Guaranteed approval
-
Loan without any verification
-
Money in exchange for an upfront payment
-
Guaranteed low interest regardless of profile
-
Loan through an unknown APK
-
Approval through WhatsApp only
-
A request for your OTP, UPI PIN or banking password
Personal loan scams can start through fake apps, websites, calls, SMS messages or WhatsApp offers. Pocketly's borrower-safety guidance recommends checking who provides the loan, whether the lender is regulated, and the applicable KFS and charges before accepting an offer.
Fast should never mean careless.
Can You Get an Instant Personal Loan Without Documents?
You may see searches such as personal loan without documents or instant loan app without income proof.
In practice, legitimate lending still involves verification.
What digital lending can reduce is physical paperwork.
For example, Pocketly provides a digital process with minimum KYC rather than claiming that legitimate lending requires absolutely no verification.
That's an important difference.
Is Same Day Personal Loan Disbursement Possible?
Yes, it may be possible when:
-
Your application is complete
-
KYC is successful
-
Your information is correct
-
You meet applicable eligibility requirements
-
The loan is approved
-
Bank details are verified
-
There are no banking or technical delays
But no responsible lender should promise the exact same personal loan disbursal time to every applicant.
Final Word
If you're searching for the fastest way to get a personal loan, focus on preparation rather than simply searching for the app making the biggest speed claim.
Keep your KYC information ready. Apply for an amount you genuinely need. Understand your EMI. Verify the lender. Read the KFS. And never mistake fast personal loan approval for guaranteed instant personal loan disbursement.
For eligible borrowers looking for an instant personal loan online, Pocketly offers a 100% digital borrowing journey with personal loans from ₹1,000 to ₹50,000, minimum KYC, flexible repayment options and no CIBIL score requirement to apply.
When an unexpected expense can't wait, Pocketly can help eligible borrowers check their personal loan options online.
Apply with Pocketly, review your eligible offer and understand the complete borrowing cost before accepting.
FAQs
What is the fastest way to get a personal loan?
Apply through a legitimate digital lending process, keep your KYC and bank details ready and complete verification promptly with pocketly.
Can I get an instant personal loan online?
Yes. Eligible borrowers can apply through digital lending platforms such as Pocketly. Approval and disbursal remain subject to applicable checks.
How can I get fast personal loan approval?
Submit accurate details, complete KYC immediately and respond quickly to any additional verification request.
Can I get same day personal loan disbursement?
It may be possible with some digital loan processes after successful approval and verification, but it is not guaranteed.
Can I get an instant loan of ₹5,000?
Small personal loans may be available depending on the lender and your eligibility. Pocketly currently offers eligible loan amounts starting from ₹1,000 and going up to ₹50,000.
Can I get an NBFC personal loan with bad credit?
You can apply where eligible, but approval depends on the lender's underwriting and verification criteria.
Does Pocketly require a CIBIL score?
Pocketly states that a CIBIL score is not required to apply. Approval remains subject to applicable eligibility and verification.
Is Pocketly an NBFC?
Pocketly is a technology platform. Personal loans through Pocketly are lent by Speel Finance Company Private Limited, which Pocketly identifies as an RBI-registered NBFC.
Should I calculate EMI before applying?
Yes. Use a personal loan EMI calculator to understand the possible repayment obligation before borrowing.
What should I check before taking an instant loan?
Check the lender, loan amount, APR, interest, processing fee, repayment tenure, EMI, total repayment and Key Fact Statement.