

NBFC Personal Loan in India: What Borrowers Should Check Before Applying
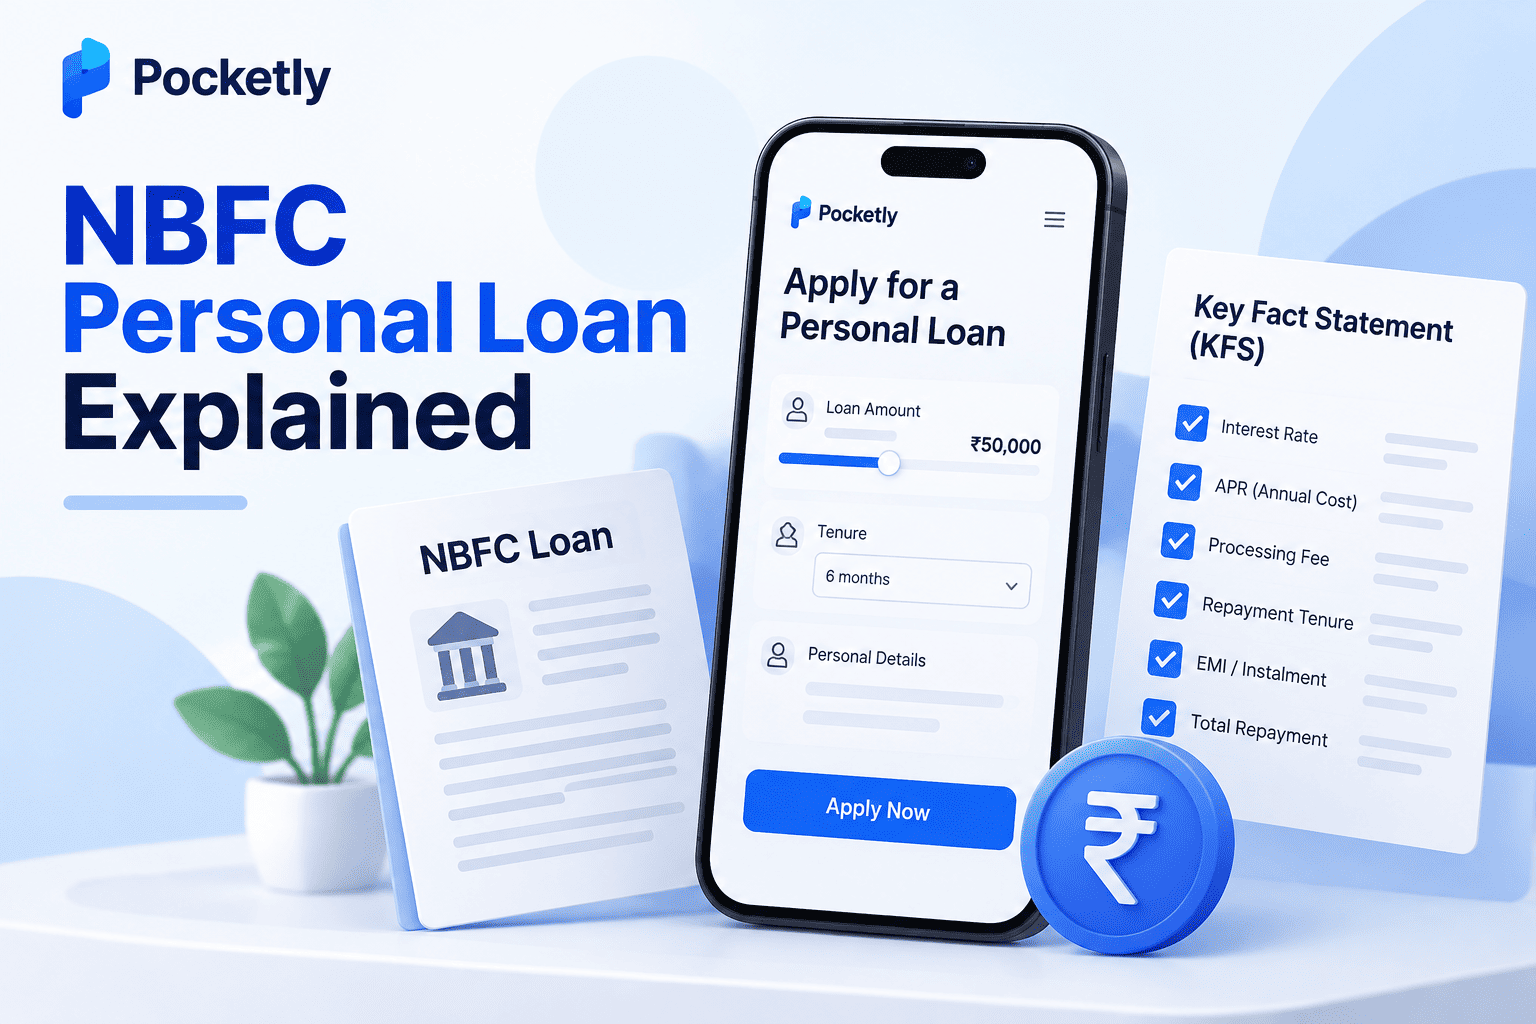
An NBFC personal loan in India is an unsecured personal loan offered by a Non-Banking Financial Company to eligible borrowers for personal financial requirements. Unlike a traditional bank, an NBFC is a financial company that can carry out activities such as lending subject to the applicable regulatory framework.
At Pocketly, personal loans are lent by Speel Finance Company Private Limited, an RBI-registered NBFC, through our technology platform, Pocketly.
Approval is not automatic. Your application is evaluated according to applicable eligibility, verification and underwriting criteria.
Eligible borrowers can explore our personal-loan options according to their requirements and applicable eligibility criteria.
Check Your Eligibility With Pocketly
Borrow responsibly and choose an amount you can reasonably repay.
Quick Answer
|
Question |
Answer |
|
What is an NBFC loan? |
Credit offered by a Non-Banking Financial Company |
|
Can NBFCs provide personal loans? |
Yes, eligible NBFCs can undertake lending |
|
Is an NBFC a bank? |
No |
|
Can an NBFC personal loan be digital? |
Yes |
|
Is collateral always required? |
Many personal loans are unsecured, depending on the product |
|
Who lends through Pocketly? |
Speel Finance Company Private Limited |
|
Is Speel Finance an NBFC? |
Yes. Our responsible-lending disclosure identifies it as an RBI-registered NBFC |
|
Does applying guarantee approval? |
No. Approval remains subject to applicable eligibility and underwriting |
The RBI describes NBFCs as companies engaged principally in financial activities such as loans and advances, investments and certain other financial businesses. RBI also regulates and supervises NBFCs under the applicable regulatory framework.
What Is the Meaning of an NBFC Personal Loan?
The NBFC personal loan meaning is straightforward: it is a personal loan where the lending entity is a Non-Banking Financial Company rather than a conventional bank.
An NBFC can undertake lending and other permitted financial activities, but an NBFC should not be treated as another name for a bank. The RBI regulates NBFCs under a framework applicable to their activities and classifications.
For a borrower, the more useful question is therefore:
Who is the regulated entity providing my loan?
This becomes particularly relevant when applying through a mobile app or other digital platform.
With Pocketly, the distinction is clear. Pocketly is our technology platform, while Speel Finance Company Private Limited is the RBI-registered NBFC lending personal loans through the platform.
Also Read: 7 Day Loan App in India: Short-Term Loan Options in 2026
How Does an NBFC Personal Loan Work?
An NBFC personal loan online can take you from application to repayment through a largely digital journey.
A typical process works like this:
-
Choose the required loan amount
Decide how much you genuinely need rather than automatically selecting the maximum amount available. -
Submit your application
Enter the requested personal, contact, income and other relevant information. -
Complete applicable KYC
The lender may require identity, address and other KYC information according to the applicable process. -
Creditworthiness is assessed
The lender evaluates your application using its eligibility and underwriting framework. -
Review the loan offer
If eligible, review the interest rate, APR, processing charges, repayment period, instalments and other applicable conditions. -
Read the Key Fact Statement
The KFS helps you understand important information about the loan and its cost before entering the agreement. -
Accept the agreement
Proceed only after checking the repayment obligation and applicable terms. -
Receive the funds
Following successful approval and completion of applicable requirements, the loan can be disbursed according to the lender's process. -
Repay according to schedule
Follow the repayment schedule communicated in your loan agreement.
For digital borrowing, speed should never replace checking the terms of the loan.
What Should You Check in the Key Fact Statement?
A Key Fact Statement, or KFS, is one of the most useful documents to examine before taking a personal loan.
RBI's KFS framework defines APR as the annual cost of credit that includes the interest rate and other charges associated with the credit facility. The framework also requires applicable KFS disclosures to include an APR computation sheet and loan amortisation schedule. Charges that are not disclosed in the KFS cannot subsequently be charged by the regulated entity without the borrower's explicit consent.
Check:
-
sanctioned loan amount
-
amount you will receive
-
interest rate
-
APR
-
processing fee
-
applicable taxes and charges
-
repayment period
-
instalment amount
-
repayment dates
-
total repayment obligation
-
applicable penal charges
-
prepayment or foreclosure conditions, where applicable
This makes APR especially useful when comparing two loans whose headline interest rates appear similar.
NBFC vs Bank Personal Loan: What Is the Difference?
People searching for NBFC vs bank personal loan usually want to know which borrowing route suits them.
There is no universal answer because eligibility, pricing and loan conditions vary between lenders and borrowers.
|
Factor |
NBFC Personal Loan |
Bank Personal Loan |
|
Lending entity |
Non-Banking Financial Company |
Bank |
|
Regulatory framework |
Subject to applicable RBI regulation |
Subject to applicable RBI banking regulation |
|
Digital applications |
Common among digital lenders |
Also widely available |
|
Eligibility |
Depends on lender |
Depends on bank |
|
Interest/APR |
Product and borrower dependent |
Product and borrower dependent |
|
Processing fees |
Check individual offer and KFS |
Check individual offer and KFS |
|
Loan tenure |
Product dependent |
Product dependent |
|
Credit assessment |
Lender-specific underwriting |
Bank-specific underwriting |
Do not choose between a bank and an NBFC based only on application speed.
Compare the APR, net amount received, repayment period, EMI or instalment, fees, total repayment amount and lender identity.
Who Can Apply for an NBFC Personal Loan?
Eligibility varies between NBFCs and loan products.
For our applicable Pocketly loan journey, the current website information identifies eligibility/documentation elements including personal information, address proof based on Aadhaar, verified email ID, video KYC and PAN details. Our salaried-loan information currently states an age range of 18–40 years.
Borrowers can broadly include:
-
salaried employees
-
self-employed professionals
-
freelancers
-
eligible non-salaried income earners
-
first-jobbers
-
other applicants meeting the lender's criteria
If you're salaried, you can explore our personal loan for salaried applicants.
If you run your own business or work independently, explore our personal loan for self employed applicants. Our current self-employed loan information describes a digital application journey and loans up to ₹50,000, subject to applicable criteria.
Applicants with eligible income who do not receive a conventional monthly salary can explore our personal loan for non salaried option.
What Documents May Be Required?
Document requirements depend on the lender, product and KYC process.
For our applicable Pocketly application journey, the current product pages identify:
-
personal details
-
address proof as per Aadhaar
-
verified email ID
-
video KYC
-
PAN card number
Providing PAN or Aadhaar details does not guarantee that a personal loan will be approved.
These documents help with identity, KYC and verification. Lending decisions remain subject to applicable eligibility and underwriting.
How Much Can You Borrow With Pocketly?
Our current general loan disclosures show personal-loan amounts ranging from ₹1,000 to ₹50,000, with repayment periods from 61 days to 9 months. The same disclosure currently lists interest at 2%–3% per month, processing fees of 0%–7.5% of the loan amount plus applicable GST, and an APR range of 30%–121%. Actual terms depend on the applicable offer and borrower profile.
These figures should be checked against your individual loan offer and KFS before borrowing because your actual cost can differ.
Example
Suppose you need money for an unexpected ₹8,000 expense.
Do not ask only:
"Can I get ₹8,000?"
Also check:
-
How much will reach my bank account after applicable deductions?
-
What is the APR?
-
What is my repayment schedule?
-
What will I repay in total?
-
Can my current income comfortably support that repayment?
That gives you a better view of affordability.
Is an NBFC Personal Loan Available Online?
Yes. An NBFC personal loan online can be offered through digital channels, subject to the lender's processes and applicable regulation.
Digital lending can cover activities such as customer acquisition, credit assessment, approval, disbursement, repayment and customer service through digital technologies.
RBI's digital-lending framework has addressed borrower protection areas including disclosures, creditworthiness assessment, disbursal and repayment, data handling, grievance redressal and digital lending apps.
With Pocketly, our loan journey is designed to be digital. Our current website also describes the application journey as 100% digital.
A digital application can make applying quicker, but:
Application speed ≠ approval speed ≠ disbursal speed.
Every application remains subject to the applicable checks.
What About an Instant Personal Loan Online in 2 Minutes?
You may see searches such as instant personal loan online in 2 minutes, particularly when borrowers need short-term access to funds.
Treat "2 minutes" carefully.
A borrower may be able to complete certain application steps quickly, but that does not mean every applicant will receive approval or money in exactly two minutes.
At Pocketly, we recommend checking your eligibility and the complete borrowing terms rather than making a decision based only on speed.
What Costs Should You Compare Before Taking an NBFC Loan?
Before accepting an NBFC loan, compare the complete borrowing cost.
|
Cost |
What to check |
|
Interest rate |
Rate charged on the loan |
|
APR |
Annualised cost incorporating applicable charges |
|
Processing fee |
Upfront processing charge, if applicable |
|
GST |
Applicable tax on relevant fees/charges |
|
Instalment |
Amount due according to repayment schedule |
|
Tenure |
How long you have to repay |
|
Penal charges |
Charges applicable for specified defaults/non-compliance |
|
Total repayment |
Total amount payable under the loan terms |
Do not compare loans only by their monthly interest rate.
RBI's KFS requirements are intended to give borrowers key loan information, including costs, in a standardised and understandable form.
Before selecting your loan amount with us, use our personal loan EMI calculator to estimate the repayment impact.
How Can You Check Whether an Online Loan Is Legitimate?
Before applying through any loan app or website:
-
identify the regulated lender
-
check whether the claimed lender can be verified
-
read the KFS
-
examine APR and charges
-
read the privacy policy
-
check grievance-redressal information
-
avoid apps asking for unnecessary device permissions
-
never pay money based solely on a promise of guaranteed approval
-
avoid offers that hide the lender's identity
RBI has taken measures around digital lending apps partly in response to concerns involving unauthorised apps, misleading claims, data practices and borrower protection.
With Pocketly, our responsible-lending disclosure identifies Speel Finance Company Private Limited as the RBI-registered NBFC lending through our Pocketly technology platform.
Common Mistakes to Avoid Before Taking an NBFC Personal Loan
Avoid these borrowing mistakes:
-
choosing a loan only because the application looks fast
-
borrowing more than you need
-
comparing only the interest rate and ignoring APR
-
skipping the KFS
-
ignoring processing charges
-
overlooking repayment dates
-
assuming Aadhaar or PAN guarantees approval
-
taking a second loan simply to manage an existing unaffordable repayment
-
applying through an app without checking the actual lender
-
assuming every "loan app" is itself an NBFC
A personal loan creates a repayment obligation. Borrow only when the repayment can reasonably fit your budget.
Final Takeaway
An NBFC personal loan in India can provide access to unsecured personal credit through a Non-Banking Financial Company, including through digital platforms. The key is to understand who the regulated lender is and compare the APR, fees, repayment period, KFS and total repayment obligation before accepting an offer.
With Pocketly, personal loans are lent by Speel Finance Company Private Limited, an RBI-registered NBFC, through our Pocketly technology platform.
Before You Apply: 7-Point Checklist
Before taking an NBFC personal loan, ask yourself:
-
Who is providing the credit?
-
How much money do I genuinely need?
-
What amount will I receive?
-
What is the APR?
-
What fees and charges apply?
-
What is my total repayment obligation?
-
Can I make the scheduled repayments from my expected income?
If those answers are clear, you can make a more informed borrowing decision.
FAQs
1. What is an NBFC personal loan?
An NBFC personal loan is a personal loan provided by a Non-Banking Financial Company. The loan may be offered through physical or digital channels and remains subject to the lender's eligibility, underwriting, pricing and repayment conditions.
2. What does NBFC loan mean?
An NBFC loan means credit provided by a Non-Banking Financial Company rather than a conventional bank. NBFCs can undertake lending and other permitted financial activities under the applicable regulatory framework.
3. Is Pocketly an NBFC?
Pocketly is our technology platform. Speel Finance Company Private Limited is the RBI-registered NBFC that lends personal loans through Pocketly.
4. Can I apply for an NBFC personal loan online?
Yes. An NBFC personal loan online can have a digital application, verification and loan-management process. Approval remains subject to the lender's applicable eligibility and underwriting criteria.
5. Is an NBFC personal loan better than a bank loan?
Neither option is automatically better for every borrower. For an NBFC vs bank personal loan comparison, examine APR, fees, repayment period, total repayment, eligibility and the terms offered specifically to you.
6. Can salaried applicants apply with Pocketly?
Yes. If you're salaried, you can explore our personal loan for salaried applicants, subject to applicable eligibility and underwriting requirements.
7. Can self-employed applicants apply with Pocketly?
If you're self-employed, you can explore our personal loan for self employed applicants. Our current self-employed product information includes a digital application journey and loans up to ₹50,000, subject to applicable eligibility and underwriting.
8. Can non-salaried applicants apply for a personal loan?
Applicants with eligible income who do not receive a conventional salary may explore our personal loan for non salaried option, subject to applicable eligibility, income assessment and underwriting.
9. Does an instant personal loan online in 2 minutes guarantee disbursal?
No. A quick digital application does not guarantee approval or disbursal within two minutes. Verification, eligibility and underwriting requirements still apply.
10. How do I choose the best loan app in India?
If you're comparing options to find the best loan app in India for your needs, check the identity of the regulated lender, APR, processing fees, repayment period, KFS, total repayment obligation, privacy practices and grievance-redressal process rather than relying on a "best" claim.
11. Should I calculate my EMI before applying?
Yes. Use our personal loan EMI calculator to understand how a proposed loan amount and repayment schedule could affect your budget before proceeding.