

NBFC Personal Loan for Bad Credit: Apply Online 2026
Although a low CIBIL score will not be a negative indicator for getting an NBFC personal loan for bad credit, it does not necessarily assure either approval or rejection. A lender can look at your credit history and other information like income, current obligations, verification and their own underwriting standards.
With Pocketly, eligible borrowers can apply online for a personal loan through our digital platform. Personal loans through Pocketly are lent by Speel Finance Company Private Limited, an RBI-registered NBFC. Approval, the eligible loan amount and the final terms depend on applicable eligibility and underwriting criteria.
Quick Answer
|
Question |
Answer |
|
Can I apply for an NBFC loan with bad credit? |
Yes, you can apply, but approval is not guaranteed. |
|
Does a low CIBIL score mean automatic rejection? |
Not necessarily. The lender makes the final credit decision based on its applicable criteria. |
|
Can I apply for an NBFC loan online? |
Yes. Many NBFC loan journeys are available digitally. |
|
Who provides personal loans through Pocketly? |
Speel Finance Company Private Limited, an RBI-registered NBFC. |
|
How much can I apply for through Pocketly? |
Our published loan range is ₹1,000 to ₹50,000, subject to eligibility. |
|
Does applying guarantee a loan? |
No. Every application remains subject to applicable verification, eligibility and underwriting. |
Also Read: 7 Days Loan App in India: Short-Term Loan Options in 2026
What Is an NBFC Personal Loan for Bad Credit?
An NBFC personal loan for bad credit typically means a person who requires a personal loan from an NBFC and has a poor or less than good credit history.
There are various situations which can lead to a low credit score. This can be because of previous late payments, lack of payments, high levels of outstanding debt, or a short credit history.
But a credit score doesn't necessarily mean a loan will be granted.
The lender will still review the application based on their underwriting and lending policies.
If you want a broader explanation of how this type of lending works, read our guide on what is an NBFC personal loan.
Can You Get an NBFC Personal Loan With a Low CIBIL Score?
An NBFC personal loan can be applied to even with a low CIBIL score, although it is not a guarantee for loans to be approved. Your credit information may be part of the lender's assessment, in addition to other information that is necessary under the lender's applicable lending criteria.
The RBI has mandated that credit institutions and CICs maintain up to date credit information every fortnight. The regulation has been in effect since January 1, 2025, and will ensure lenders have more up-to-date information to use in their credit decisions.
This makes your recent repayment behaviour relevant as well as your older credit history.
If your credit score is currently low, avoid assuming that any lender or loan app will approve the application solely because it advertises digital or quick processing.
Low CIBIL does not mean the same thing for every borrower
Consider two applicants:
Applicant A: Has a low score following previous delayed repayments and already has several outstanding loans.
Applicant B: Has a limited credit history and has only recently started using credit.
Both applicants may have a less-than-ideal credit profile, but their financial situations are different.
The lender makes the final decision based on the information available and its underwriting requirements.
What Do NBFCs Check When Your Credit Score Is Low?
Credit assessment can vary between lenders and products. A lender may consider information relevant to your ability and willingness to repay.
This can include:
-
Credit history and available credit information
-
Existing loans and repayment obligations
-
Past repayment behaviour
-
Income or source of income
-
Information provided during the application
-
KYC and identity verification
-
Existing indebtedness
-
Applicable internal underwriting criteria
Do not assume that meeting one condition guarantees approval.
For example, having regular income does not erase previous missed repayments. Similarly, having a low credit score does not by itself tell you the outcome of a new application.
How to Apply for an NBFC Loan Online
If you are searching for NBFC loan apply online options, the digital process can reduce the need for branch visits and physical paperwork.
A typical online application involves:
-
Choose a regulated lending option
Identify the actual lender behind the loan or lending platform. -
Check the basic eligibility requirements
Review age, income, KYC and other applicable requirements before submitting an application. -
Enter your application details
Provide accurate personal, financial and verification information. -
Complete the required verification
The exact verification process depends on the lender and your application. -
Wait for the credit assessment
Submitting an application does not mean it has been approved. -
Review the offer and KFS
If an offer is made, check the interest rate, APR, applicable charges, repayment schedule and total repayment obligation. -
Accept only if you can manage the repayment
Borrow an amount that fits your expected cash flow rather than automatically taking the maximum amount available to you.
Check Your Eligibility With Pocketly
With Pocketly, eligible borrowers can complete the personal-loan application process digitally. Our published personal-loan range is ₹1,000 to ₹50,000, subject to applicable eligibility and underwriting criteria.
[Check Your Eligibility With Pocketly]
Can You Apply Through Pocketly If You Have a Low CIBIL Score?
You can check your eligibility with us even if your credit profile is not ideal. However, we do not promise approval based on a particular CIBIL score.
Your application remains subject to applicable verification, eligibility and underwriting criteria.
Pocketly is our digital lending platform, while Speel Finance Company Private Limited is the RBI-registered NBFC lending personal loans through Pocketly.
This distinction matters when you compare digital loan options. Always identify the entity actually providing the credit rather than judging a loan only by the name of the app or platform.
Pocketly Personal Loan NBFC Features
If you are comparing an NBFC personal loan for low CIBIL score requirements or other personal-loan options, consider the complete borrowing terms rather than only the application speed.
Our currently published product information includes:
|
Feature |
Pocketly Published Information |
|
Loan amount |
₹1,000 to ₹50,000, subject to eligibility |
|
Application |
Online |
|
Regulated lender |
Speel Finance Company Private Limited |
|
Lender type |
RBI-registered NBFC |
|
Collateral |
Not required for the published personal-loan product |
|
Approval |
Subject to eligibility and underwriting |
|
Loan terms |
Review the specific terms offered before accepting |
The exact offer available to you can depend on your application and applicable lending criteria.
How to Choose the Best NBFC for a Personal Loan
There is no single best NBFC for personal loan requirements for every borrower. The better option depends on the actual offer, your eligibility and whether you can comfortably meet the repayment obligation.
Before choosing an NBFC personal loan, compare:
-
Identity of the regulated lender
-
Eligible loan amount
-
Interest rate
-
Annual Percentage Rate (APR)
-
Processing and other applicable fees
-
Amount actually disbursed
-
Repayment period
-
Scheduled repayment amount
-
Total repayment obligation
-
Late-payment consequences
-
Foreclosure or prepayment conditions
-
Key Fact Statement
-
Customer support and grievance-redressal details
The lowest advertised interest rate should not be the only factor you consider.
Also Read: How Much CIBIL Score Is Good to Get an Personal Loan?
Why APR and the Key Fact Statement Matter
The Annual Percentage Rate (APR) is a measure to help you understand the annualised cost of credit. According to the RBI rules, the APR is the annual cost of credit which incorporates any charges that are related to the credit facility and the interest rate.
The Key Fact Statement (KFS) gives you important information about the loan in a standardised, easier-to-understand format.
Before accepting a personal loan, read your KFS carefully.
Pay particular attention to:
-
Loan amount
-
Interest rate
-
APR
-
Fees and charges
-
Net amount you will receive
-
Repayment amount
-
Repayment dates
-
Loan tenure
-
Total interest
-
Total repayment obligation
RBI's framework also requires applicable retail borrowers to receive key loan information so they can make a more informed financial decision.
Do not accept a loan simply because the application was quick.
Application speed, approval and disbursal are different stages of the lending process.
Low CIBIL Score vs No Credit History
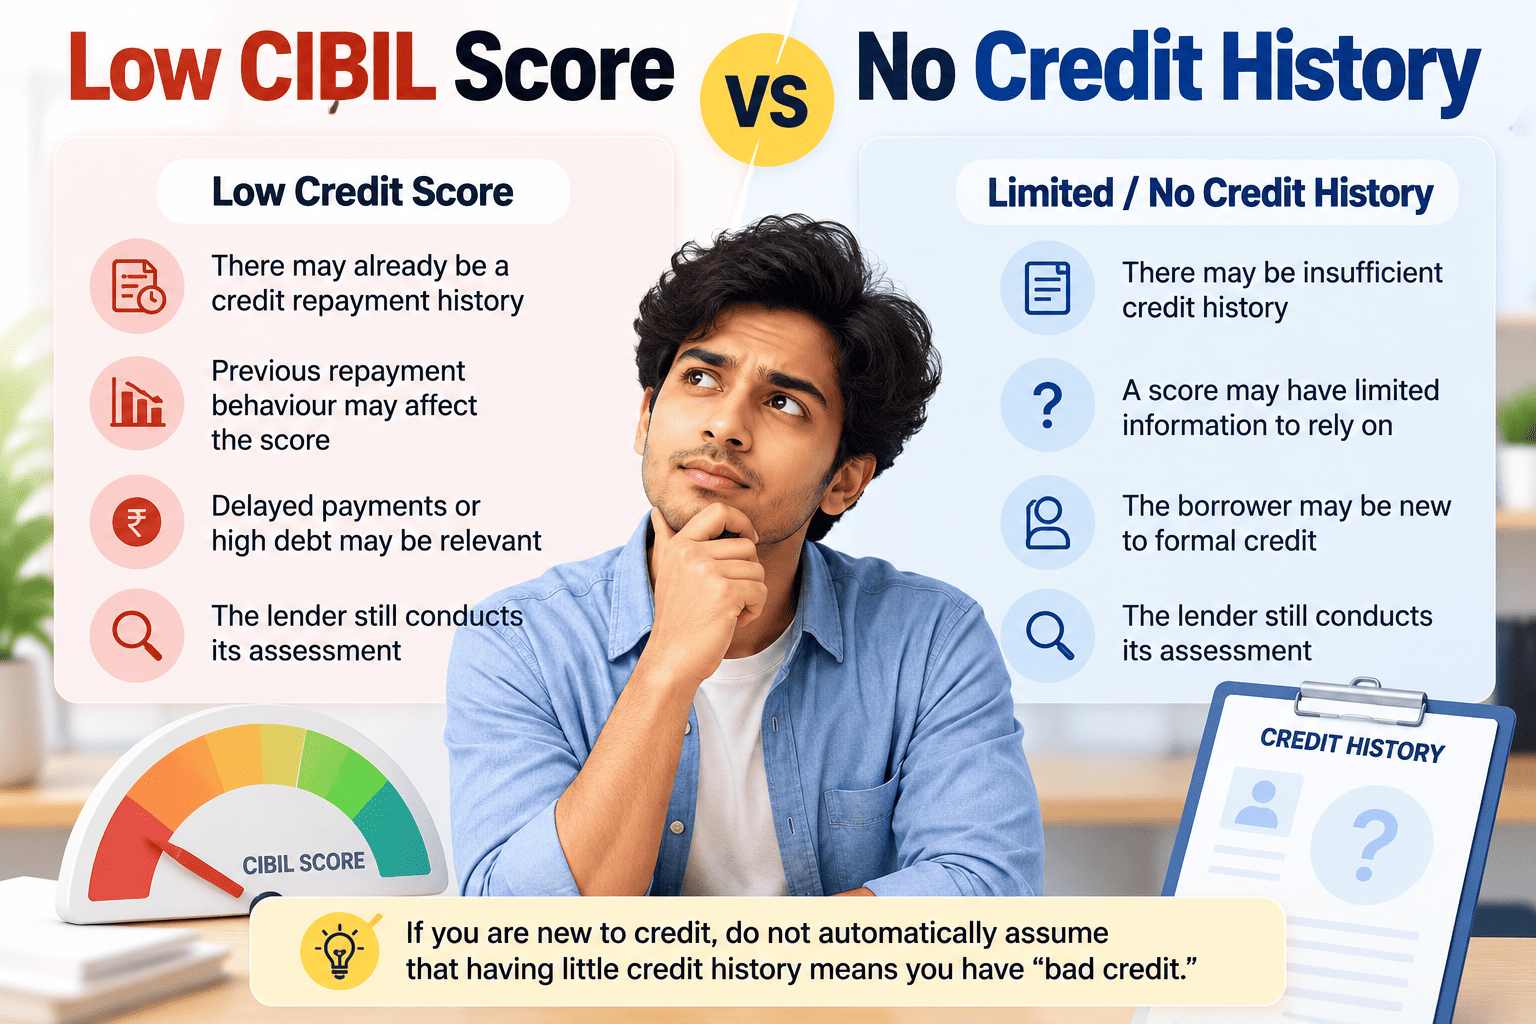
A low credit score and having little or no credit history are not necessarily the same situation.
|
Low Credit Score |
Limited/No Credit History |
|
There may already be a credit repayment history |
There may be insufficient credit history |
|
Previous repayment behaviour may affect the score |
A score may have limited information to rely on |
|
Delayed payments or high debt may be relevant |
The borrower may be new to formal credit |
|
The lender still conducts its assessment |
The lender still conducts its assessment |
If you are new to credit, do not automatically assume that having little credit history means you have “bad credit.”
Similarly, a low score should not be treated as permanent. Your credit information can change as newer repayment information is reported.
How Can You Improve Your Position Before Applying?
If you have bad credit, repeatedly submitting applications is not necessarily the best first step.
Before applying:
-
Check your credit report
Look for incorrect information and understand what may be affecting your credit profile. -
Clear overdue payments where possible
Unpaid or overdue credit obligations can affect your overall credit profile. -
Pay current obligations on time
Recent repayment behaviour becomes part of your credit history. -
Review your existing debt
Consider whether adding another repayment obligation is affordable. -
Avoid borrowing more than you need
A larger loan also means a larger repayment obligation. -
Provide accurate application information
Do not alter income, employment or other details to improve your chances of approval. -
Check affordability before accepting an offer
Calculate whether the repayment will fit within your expected income and essential monthly expenses.
You can use our personal loan EMI calculator to estimate repayments before deciding how much to borrow.
Common Mistakes to Avoid When Looking for a Bad-Credit Loan
A low credit score can make borrowers focus heavily on getting approved. The cost and repayment obligation still matter.
Avoid these mistakes:
-
Applying to multiple lenders without checking eligibility
-
Believing “100% approval” claims
-
Borrowing solely because an app advertises fast processing
-
Ignoring the regulated lender behind the platform
-
Looking only at the interest rate instead of APR
-
Ignoring processing fees and other applicable charges
-
Taking the maximum amount offered when you need less
-
Skipping the KFS
-
Borrowing without checking the repayment schedule
-
Using another expensive loan simply to cover an existing repayment without assessing the total debt burden
A loan should solve a genuine short-term financial requirement without creating an unaffordable repayment obligation.
Before You Apply: 8-Point Checklist
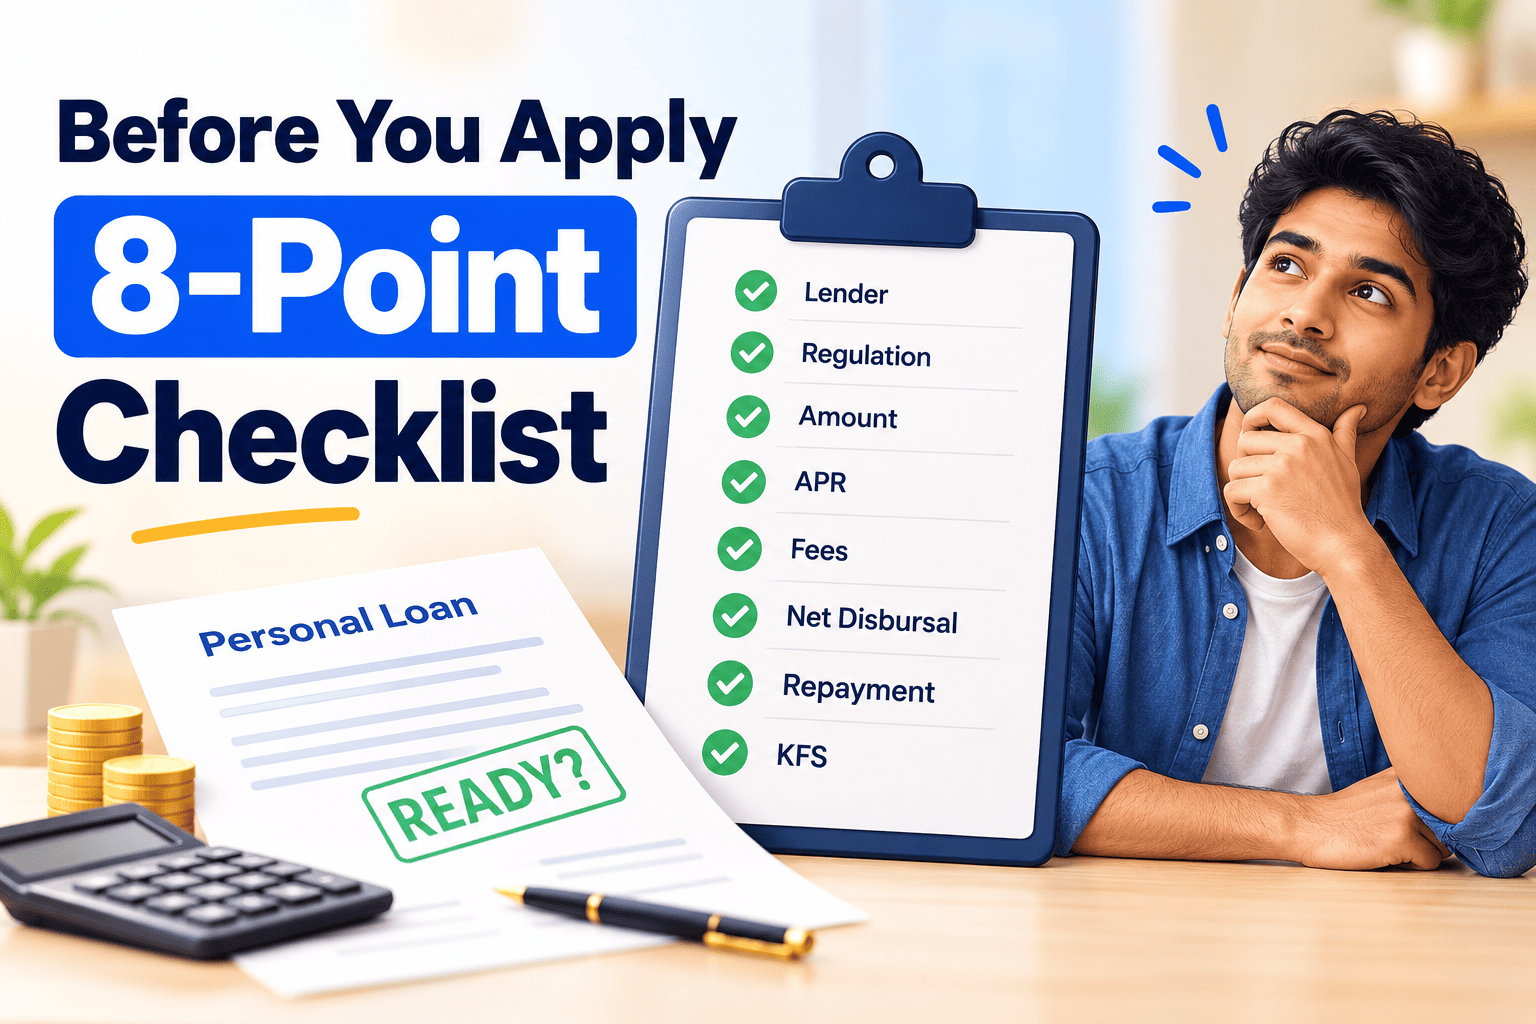
Ask these questions before submitting or accepting an NBFC loan apply request:
|
Check |
Question to Ask |
|
Lender |
Who is actually providing the loan? |
|
Regulation |
Is the lender appropriately regulated? |
|
Amount |
How much do I genuinely need? |
|
APR |
What is the annualised cost of the loan? |
|
Fees |
What charges will I pay? |
|
Net disbursal |
How much money will actually reach me? |
|
Repayment |
Can I comfortably make every scheduled repayment? |
|
KFS |
Have I read the Key Fact Statement before accepting? |
If any of these details are unclear, understand them before accepting the loan.
Check Your Eligibility With Pocketly
A low credit score should not push you into accepting the first loan offer you find.
If you need an NBFC personal loan for bad credit, first understand your credit profile, compare the complete borrowing cost and choose an amount you can reasonably repay.
With Pocketly, eligible borrowers can apply digitally for personal loans lent by Speel Finance Company Private Limited, an RBI-registered NBFC. Our published personal-loan range is ₹1,000 to ₹50,000, subject to applicable eligibility and underwriting criteria.
Review the APR, applicable charges, repayment schedule and Key Fact Statement before accepting any offer.
[Check Your Eligibility With Pocketly]
Borrow responsibly. A personal loan creates a repayment obligation. Approval, loan amount and applicable terms are subject to eligibility, verification and underwriting criteria.
FAQs
1. Can I get an NBFC personal loan with bad credit?
You can apply for an NBFC personal loan for bad credit, but a low credit score does not guarantee approval or rejection. The lender assesses your application according to its applicable eligibility, verification and underwriting criteria.
2. Can I get an NBFC personal loan with a low CIBIL score?
It may be possible to apply for an NBFC personal loan for low CIBIL score situations. The lender ultimately determines the credit based on evaluating the application and pertinent credit information, however.
3. What CIBIL score is required for an NBFC personal loan?
Each NBFC personal loan has its own CIBIL score criteria. Requirements and underwriting guidelines are different for lenders and loans. Review any applicable requirements for the lender and product that you are interested in.
4. Which is the best NBFC for a personal loan with bad credit?
There is no single best NBFC for every borrower. Compare the regulated lender, eligibility requirements, APR, processing fees, repayment period, total repayment obligation and KFS rather than choosing solely on a “best” claim.
5. Can I apply for an NBFC loan online?
Yes. Digital lending allows eligible borrowers to complete various stages of the loan journey online. With Pocketly, you can apply digitally for a personal loan, subject to applicable eligibility, verification and underwriting criteria.
6. Can I apply through Pocketly if my credit score is low?
You can check your eligibility with us, but we do not guarantee approval based on a particular credit score. Your application is assessed according to applicable eligibility, verification and underwriting criteria.
7. Is Pocketly an NBFC?
Pocketly is our digital lending platform. Personal loans through Pocketly are lent by Speel Finance Company Private Limited, an RBI-registered NBFC.
8. How much personal loan can I apply for through Pocketly?
Our currently published personal-loan range is ₹1,000 to ₹50,000, subject to applicable eligibility and underwriting criteria. The amount available to an individual borrower can vary.
9. Does applying for an NBFC loan guarantee approval?
No. Completing an application does not guarantee approval. Application, approval and disbursal are separate stages, and the final decision remains subject to the lender's applicable criteria.
10. What should I check before accepting an NBFC personal loan?
Check the lender, loan amount, APR, interest rate, processing fees, net disbursal, repayment period, scheduled repayments, total repayment obligation and KFS. Make sure the repayments fit your budget before accepting an offer.