

Online Loans vs Traditional Loans: Which Is Better in 2026?
When an unexpected expense arrives before payday, the difference between online loans and traditional borrowing becomes very real. A medical bill, urgent travel, laptop repair or month-end expense can leave you searching for an instant loan online rather than waiting days for a conventional application.
But is faster always better?
Not necessarily.
In 2026, borrowers should compare more than approval speed. Interest rates, APR, processing fees, repayment tenure, eligibility, lender transparency and repayment capacity all matter.
For students, first-jobbers, salaried professionals, freelancers and self-employed individuals, understanding these differences can make borrowing more manageable.
Online Loans vs Traditional Loans: Quick Answer
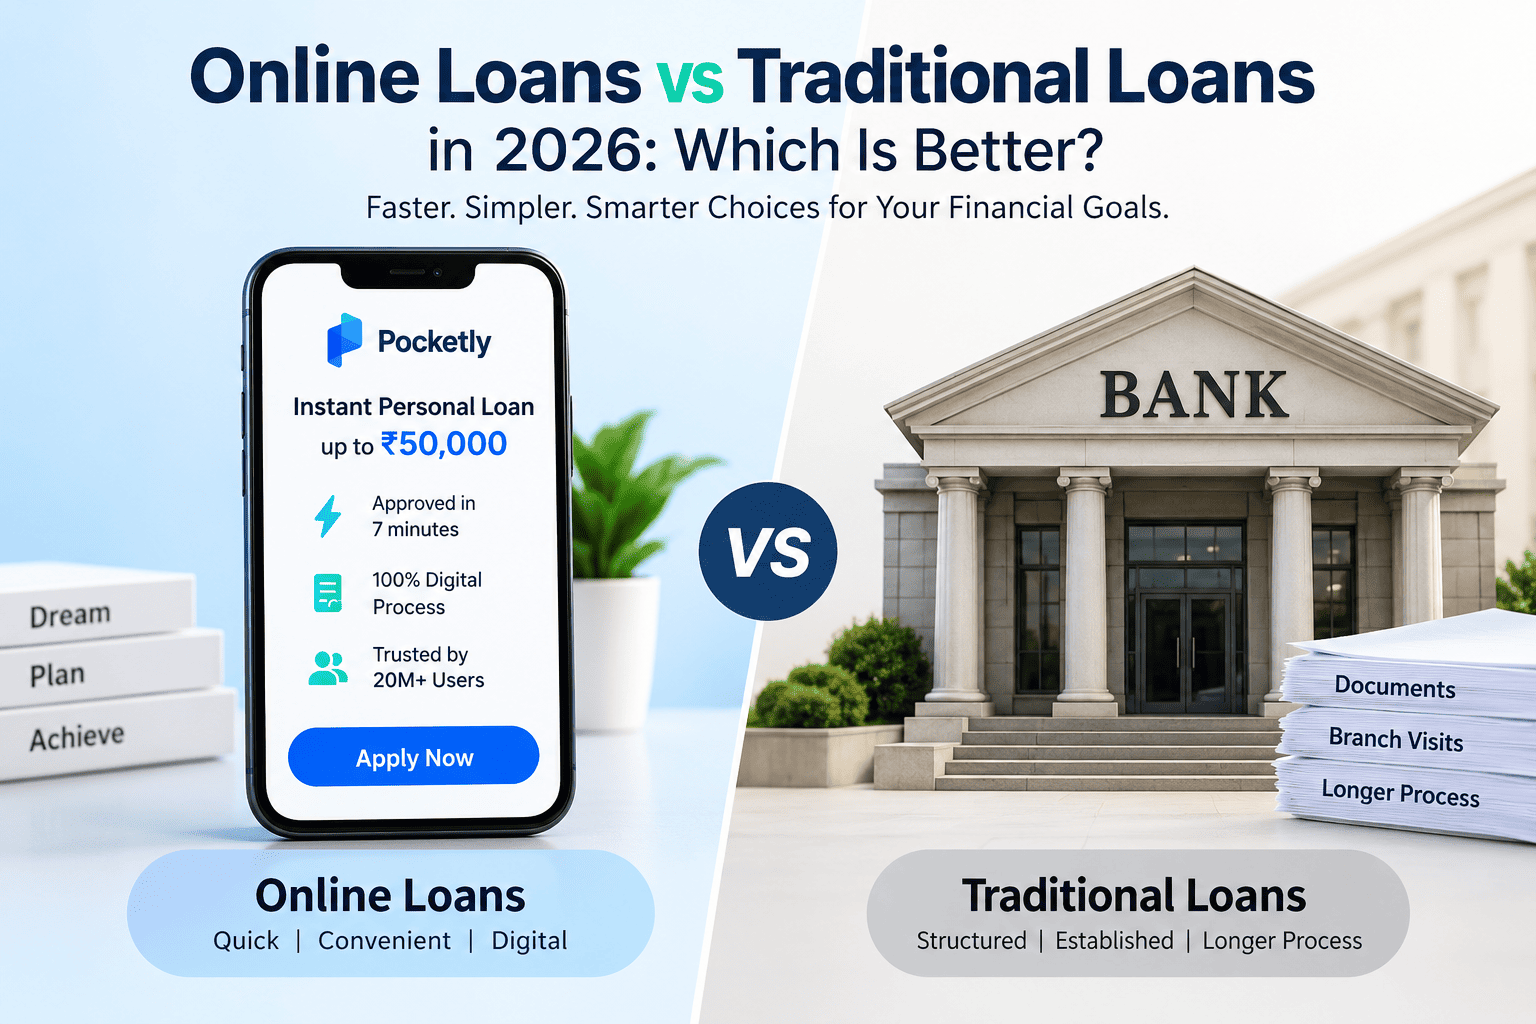
Online loans are designed for borrowers who prefer a digital application and potentially faster processing, particularly for smaller personal-loan requirements. Traditional loans may involve more conventional documentation and lender interactions. The right choice depends on your loan amount, urgency, eligibility, total borrowing cost and ability to repay.
What Are Online Loans?
Online loans are loans where the application process is completed digitally through a website or mobile application.
Depending on the lender, borrowers can:
-
Check eligibility online
-
Submit personal details
-
Complete KYC digitally
-
Upload required documents
-
Review loan terms
-
Accept the agreement
-
Receive funds directly into their bank account
-
Track repayments digitally
An online personal loan can therefore be convenient when you need access to funds without visiting a branch.
What is an instant loan online?
An instant loan online generally refers to a digital loan process designed for quick application, verification and disbursal.
However, instant does not mean guaranteed approval. Approval remains subject to the lender's eligibility and verification process.
Also read: Best Emergency Loan Apps for ₹5,000 to ₹50,000 in India
What Is a Traditional Loan?
A traditional loan generally involves borrowing through a conventional bank or financial institution.
Depending on the loan type, you may need:
-
Income documents
-
Identity and address proof
-
Bank statements
-
Employment information
-
Credit information
-
Verification
-
Additional documentation
Traditional lending can be relevant for larger and long-term financial requirements such as home loans, vehicle loans and certain business loans.
Online Loans vs Traditional Loans: Key Differences
|
Feature |
Online Loans |
Traditional Loans |
|
Application |
Digital |
Branch/assisted or digital |
|
Convenience |
High |
Depends on lender |
|
Paperwork |
Usually digital |
May involve physical documents |
|
Application availability |
Generally online |
Often institution-dependent |
|
Processing |
Designed for faster processing |
May take longer |
|
Physical visit |
Usually not required |
May be required |
|
Loan size |
Often suited to smaller requirements |
Can support larger borrowing |
|
Repayment tracking |
Usually online |
Online/branch depending on lender |
|
Best for |
Quick, smaller financial needs |
Structured/larger requirements |
Note: Actual processing time, eligibility, interest rates and loan amounts vary by lender and borrower.
Why Are Online Loans Becoming Popular?
The biggest change is convenience.
Consider a first-jobber whose salary arrives in five days but an unexpected ₹8,000 bill needs to be paid today.
Instead of spending hours travelling to a branch, a digital lender may allow the borrower to begin the application from a smartphone.
For young borrowers, this can mean:
-
Less paperwork
-
No branch queues
-
Digital KYC
-
Faster application
-
Easier repayment tracking
-
Access from almost anywhere
But convenience should never replace financial due diligence.
5 Things to Check Before You Loan Apply Online
Before you loan apply online, don't focus only on the advertised loan amount.
1. Check the total cost
Look at:
-
Interest rate
-
APR
-
Processing fee
-
GST, where applicable
-
Other charges
-
Foreclosure charges
-
Late-payment consequences
2. Check the repayment period
A longer tenure can reduce the periodic repayment amount but may increase the overall interest cost.
3. Borrow only what you need
If your requirement is ₹10,000, don't automatically borrow ₹50,000 simply because you qualify for a higher amount.
4. Verify the lender
Understand who is actually providing the credit and read the applicable terms before accepting the offer.
5. Protect your personal information
Never share OTPs, PINs or banking passwords with individuals claiming they can speed up loan approval.
Pocketly: A Digital Option for Young Indian Borrowers
For borrowers looking specifically for a digital personal-loan experience, Pocketly is designed around the needs of young Indians, including students, first-jobbers, freelancers and salaried professionals.
Pocketly's published information states that borrowers can access loans of ₹1,000 to ₹50,000, with repayment periods ranging from 61 days to 9 months, subject to eligibility and applicable terms. The published interest rate is 2%–3% per month, with processing fees of 0%–7.5% plus GST as applicable and an APR range of 30%–121%.
Pocketly also states that its digital journey uses minimum KYC and is designed to be 100% online.
For salaried borrowers dealing with unexpected bills before payday, Pocketly publishes loan access of up to ₹50,000, subject to eligibility.
For self-employed borrowers, Pocketly provides information about an online application process, flexible installments and loans up to ₹50,000, subject to eligibility.
Why borrowers may consider Pocketly
-
Loans up to ₹50,000
-
100% digital application journey
-
Minimum KYC
-
Flexible repayment options
-
Digital repayment tracking
-
Fast loan processing
-
No collateral mentioned for its published instant personal-loan offering
Pocketly’s Speel Finance Company Private Ltd. is an RBI-registered NBFC lending personal loans through the Pocketly technology platform and describes its responsible-lending commitments around transparency, borrower information and fair practices.
Important: Borrowers should always review the specific offer, applicable fees, APR, tenure and repayment schedule shown before accepting a loan.
Online Loan or Traditional Loan? Use This Checklist
Ask yourself these five questions:
-
How much do I actually need?
-
How urgently do I need the money?
-
What is the complete borrowing cost?
-
Can I comfortably repay the loan on time?
-
Have I verified the lender and understood the agreement?
If you need a relatively small amount urgently and prefer a digital process, an online personal loan may fit your requirements.
If you need substantial long-term financing, compare traditional lending products as well.
Common Mistakes to Avoid
Don't:
-
Choose a loan only because it says "instant"
-
Ignore APR
-
Skip the loan agreement
-
Borrow more than necessary
-
Take multiple loans simultaneously without assessing your repayment capacity
-
Share OTPs or banking credentials
-
Assume approval is guaranteed
Responsible borrowing starts before you click Apply Now.
Final Word
The online loans vs traditional loan debate isn't really about choosing "old" banking or "new" technology.
It is about choosing a borrowing process that matches your urgency, loan amount, eligibility, total cost and repayment ability.
For students, first-jobbers, salaried professionals, freelancers and self-employed individuals who prefer a digital borrowing journey, Pocketly offers personal loans up to ₹50,000, subject to eligibility and applicable terms.
Before you apply for an instant personal loan online, compare the numbers—not just the speed.
Need a digital personal-loan option? Explore Pocketly, review your available offer and understand the repayment terms before proceeding.
FAQs
Are online loans safe?
Online loans can be safe when obtained through legitimate lenders and borrowers verify the lender, understand the terms and protect their personal information.
What is an online personal loan?
An online personal loan is a personal loan where the application and much of the borrowing journey are completed digitally.
Can I loan apply online?
Yes. Many banks, NBFCs and digital lending platforms allow borrowers to submit personal-loan applications online, subject to eligibility.
Is an instant loan online guaranteed?
No. "Instant" generally describes the speed of the application or processing experience, not guaranteed approval.
Are online loans cheaper than traditional loans?
Not automatically. Compare the complete borrowing cost, including interest, APR, processing fees and applicable charges.
Can salaried employees apply for online loans?
Yes, depending on the lender's eligibility criteria. Pocketly provides a digital loan option for eligible salaried borrowers.
Can self-employed people get online loans?
Some lenders offer online loans to self-employed borrowers. Pocketly publishes a self-employed loan option subject to eligibility.
How much should I borrow?
Borrow only the amount you genuinely need and can comfortably repay within the agreed tenure.