

How Has Inflation Affected Indian Households Over the Years?
India has experienced several periods of elevated inflation, each highlighting how rising prices can affect household finances.
During 2008–09, higher international commodity and crude oil prices contributed to inflationary pressures. The Reserve Bank of India Annual Report (RBI) states that wholesale price inflation reached an intra-year peak of 12.9% in August 2008. Consumer price inflation also remained elevated, particularly for food and fuel.
In 2013–14, India's average retail inflation, measured by the Consumer Price Index (CPI), stood at 9.4%. Years later, the COVID-19 pandemic brought income uncertainty for many households, while average CPI inflation reached 6.2% in 2020–21. Inflation remained elevated at 6.7% in 2022–23, reflecting continued pressure on household budgets.
These periods illustrate a common financial challenge. As essential expenses increase, households may have less money available for savings and unexpected payments. If income does not keep pace, a personal loan for salaired individuals may become an option for managing a financial shortfall.
In India, inflation trends in 2025 showed that rising prices can fluctuate throughout the year. Retail inflation fell from 4.26% in January to 0.71% in November, while December inflation stood at 1.33%, according to government data. At the same time, personal loan credit growth slowed to 14% in March 2025 from 17.6% a year earlier. These trends highlight why it is important to understand both the cost of living and borrowing patterns when discussing personal loans. However, inflation figures alone do not establish why an individual chooses to borrow.
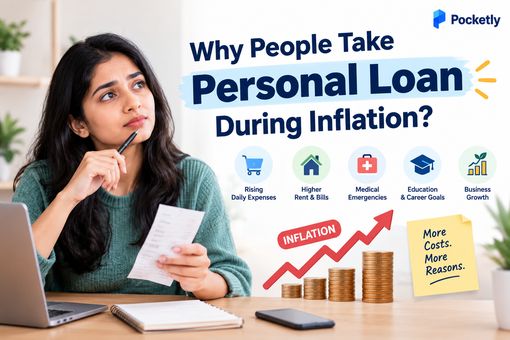
Why Do People Take Personal Loans During Inflation?
1. To Manage Rising Household Expenses
One of the most direct effects of inflation is the increase in everyday expenses. Groceries, electricity, fuel, rent and transportation can take up a larger share of monthly income, leaving less money for other financial commitments.
For households whose salaries have not increased at the same pace, managing these expenses can become challenging. Some may consider a personal loan to cover an unavoidable short-term gap while keeping other payments on track.
However, borrowing to meet recurring monthly expenses can create a debt cycle. A personal loan is generally more suitable for a manageable, temporary shortfall than for a budget that consistently exceeds income.
2. To Cover Medical Emergencies and Unexpected Expenses
Financial emergencies can become harder to manage when inflation has already reduced the amount a household can save each month.
An unexpected hospital bill, urgent home repair or essential vehicle repair can require funds that are not immediately available. A personal loan may provide access to money without requiring the borrower to pledge an asset as collateral.
For eligible borrowers, this can help address an urgent expense while spreading repayment over a chosen tenure. Before applying, it is important to compare the interest rate, fees and EMI with other available funding options.
3. To Avoid Depleting Emergency Savings
Emergency savings provide a financial cushion for unexpected events. During inflationary periods, households may already be drawing on these savings to manage higher living costs.
Some borrowers may consider a personal loan to preserve part of their savings for future emergencies. However, this approach needs careful evaluation. If the interest paid on a loan exceeds the benefit of keeping money in a savings account, borrowing may prove more expensive than using available funds.
The decision depends on the urgency of the expense, the amount of savings remaining after payment and the total cost of the loan.
4. To Manage a Temporary Cash-Flow Gap
Inflation does not always cause a permanent financial problem. Sometimes, people face a temporary mismatch between when money comes in and when expenses need to be paid.
For example, a salaried employee may be waiting for a delayed payment, or a self-employed individual may experience an unusually slow month. If an essential expense cannot be postponed, a personal loan may help bridge the gap.
This option is more manageable when the borrower has a reasonably predictable source of income and a clear repayment plan. If income is uncertain or the shortfall continues month after month, taking on additional debt may increase financial pressure.
5. To Consolidate High-Interest Debt
Rising living costs can make it more difficult to pay off existing credit card balances and other outstanding debts. Some borrowers may consider a personal loan to consolidate these obligations into a single EMI.
If the new loan has a lower effective borrowing cost than the existing debt, consolidation may reduce interest expenses and simplify monthly payments.
However, a lower EMI does not always mean a cheaper loan. A longer repayment tenure may increase the total interest paid. Borrowers should compare the overall repayment cost, processing fees and other charges before making a decision.
6. To Pay for Essential Large Expenses
Inflation can also increase the cost of education, home repairs and other important household needs. When an expense is necessary and savings are insufficient, paying the full amount upfront may not be practical.
A personal loan allows eligible borrowers to spread the cost across monthly instalments rather than arranging the entire amount immediately.
The key consideration is affordability. Borrowing may be reasonable when the expense is essential, the loan terms are competitive and the EMI fits comfortably within the monthly budget.
Personal Loans During Inflation: Benefits and Risks
|
Potential benefits |
Potential risks |
|
Helps cover urgent expenses when savings are limited |
Adds monthly EMI commitments |
|
Can help manage a temporary cash-flow gap |
Interest increases the total repayment amount |
|
Spreads a large expense across manageable instalments |
Missed payments can negatively affect credit scores |
|
May help cover unexpected medical or household expenses |
Borrowing more than necessary can increase financial stress |
- What Makes Personal Loans an Option During Inflation?
Personal loans can appeal to borrowers because they generally do not require collateral, offer flexibility in how funds are used and provide a defined repayment schedule. Depending on the lender, borrowers may also be able to choose a repayment tenure that suits their financial circumstances.
These features can make personal loans useful for addressing certain financial needs. However, approval is not guaranteed, and interest rates, fees and eligibility requirements vary between lenders.
It is also important to remember that inflation does not automatically make borrowing more affordable. If household expenses continue to rise, borrowers may find it harder to manage their EMIs alongside rent, groceries, utilities and existing financial commitments.
Is Taking a Personal Loan During Inflation a Good Decision?
A personal loan may be worth considering when it addresses a genuine financial need, the cost of borrowing is reasonable and repayment is manageable. It may help with an unexpected expense or a temporary cash-flow gap when other options are unsuitable.
On the other hand, using loans to cover a persistent gap between income and expenses can worsen financial difficulties. Borrowing for discretionary purchases without a clear repayment plan can also add unnecessary pressure.
Before applying, borrowers should compare interest rates, processing fees, repayment tenures and total borrowing costs. They should also assess existing EMIs and ensure that the additional repayment will not compromise essential expenses.
Conclusion
Inflation can put pressure on household finances by reducing purchasing power and leaving less money available for savings and emergencies. When these pressures coincide with an unexpected expense or temporary cash shortage, people may consider personal loans as a way to manage their financial needs.
The decision, however, should depend on more than the prevailing inflation rate. A personal loan is most useful when it addresses a specific need and comes with a repayment plan the borrower can realistically maintain. Ultimately, the goal should not simply be to access funds during inflation, but to manage the immediate expense without creating a larger financial burden in the future.
Frequently Asked Questions
1. Why do people take personal loans during inflation?
People may take personal loans during inflation to manage rising household expenses, cover medical emergencies, handle temporary cash-flow gaps or consolidate high-interest debt. When expenses rise faster than income, borrowing may help address an immediate financial need.
2. Is taking a personal loan during inflation a good idea?
A personal loan may be useful during inflation if it covers a necessary expense and the borrower can comfortably afford the EMIs. However, borrowing to meet recurring expenses without addressing a budget shortfall can increase financial stress.
3. How does inflation affect personal loan repayments?
Inflation does not automatically increase the EMI on an existing fixed-rate personal loan. However, rising living costs can leave borrowers with less money available for repayments. For loans with variable interest rates, changes in the applicable rate may also affect repayment terms.
4. Can a personal loan help manage rising household expenses?
A personal loan can help cover an unavoidable short-term expense when available funds are insufficient. However, it is generally not a sustainable solution for recurring expenses that consistently exceed monthly income.
5. Should I use my savings or take a personal loan during inflation?
The decision depends on your emergency fund, the urgency of the expense and the total cost of borrowing. Using savings can help avoid interest charges, while a loan may preserve some funds for future emergencies. Compare both options before deciding.
6. What should I check before taking a personal loan during inflation?
Check the interest rate, processing fees, total repayment amount, loan tenure and monthly EMI. Also assess your existing financial commitments and ensure that you can afford the repayments even if your everyday expenses increase further.
7. Can a personal loan help consolidate debt during inflation?
Yes, a personal loan may help consolidate credit card balances or other high-interest debt into a single repayment. However, compare the total borrowing costs, including fees and interest over the entire tenure, to ensure that consolidation offers a genuine financial benefit.