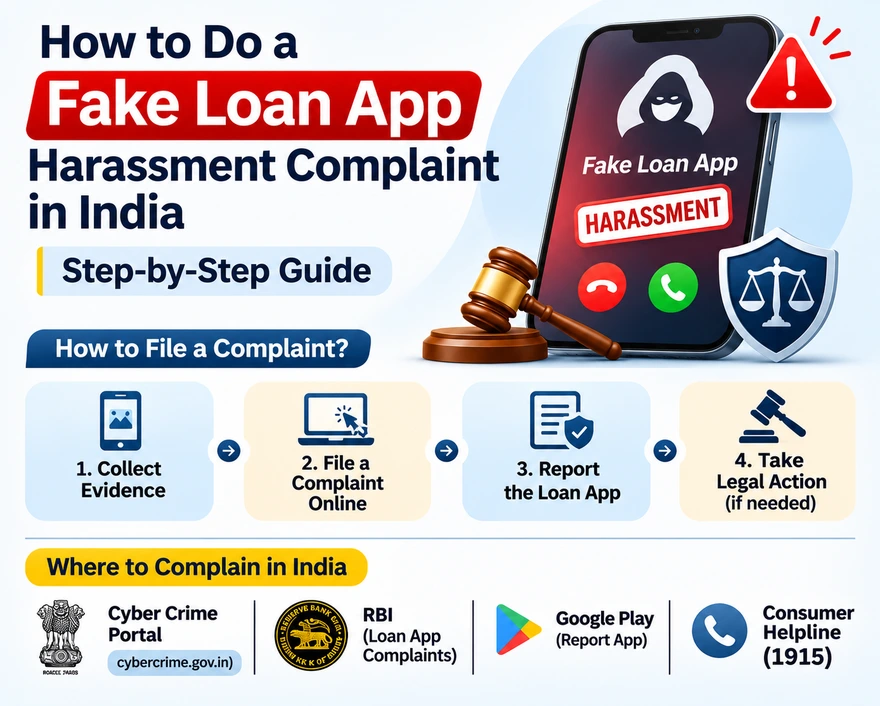


To file a fake loan app harassment complaint in India, immediately stop paying extortion demands, take screenshots of threatening messages and transaction receipts, dial the National Cyber Crime Helpline at 1930, log an online report at cybercrime.gov.in, and submit the unauthorised app on the RBI Sachet Portal (sachet.rbi.org.in). While the Reserve Bank of India (RBI) Ombudsman resolves disputes against registered banks and NBFCs, illegal loan scams fall under cybercrime and State Level Coordination Committee enforcement. At Pocketly, we operate strictly as a regulated digital lending platform backed by Speel Finance Company Private Limited, an RBI-registered NBFC, offering eligible borrowers transparent personal loans from ₹1,000 to ₹50,000 subject to KYC and underwriting checks.
Quick Answer: At a Glance
-
Emergency Fraud Helpline: Call 1930 immediately (especially within the first hour if money was debited) to freeze the scammer's receiving bank or UPI account.
-
Cybercrime & Extortion Report: File a formal fake loan app harassment complaint with screenshots, call logs, and UPI UTR numbers on cybercrime.gov.in.
-
Unregulated Lender Reporting: Log sachet rbi org in complaints at sachet.rbi.org.in so the RBI and state police can investigate and block illegal lending apps.
-
Regulated NBFC Escalation: If harassment involves an RBI-registered NBFC, escalate to its Grievance Redressal Officer (GRO) first, and approach the RBI Integrated Ombudsman (cms.rbi.org.in or 14448) if unresolved after 30 days.
What Is a Fake Loan App Harassment Complaint and When Should You File One?
A fake loan app harassment complaint is a formal legal and regulatory report filed by a borrower or victim against an unauthorised digital lending application engaging in extortion, contact-list shaming, morphed photo threats, or advance-fee loan scams. You should file loan fraud complaints the moment an app demands upfront "processing" money via personal UPI IDs, forces predatory 7-day repayment cycles, or contacts your family and colleagues.
According to the Reserve Bank of India's Digital Lending Guidelines, legitimate lending apps are strictly prohibited from accessing your mobile phone's contact list, call logs, SMS inbox, or media gallery. Any platform threatening to message your contacts or circulating edited images is committing criminal intimidation and data theft under the Information Technology Act, 2000. For deeper awareness of common digital traps, you can explore our guides on identifying fake loan apps and 7 personal loan scams to watch out for.
Which Portal Should You Use? Choosing the Right Complaint Channel
Filing fraud loan complaints on the wrong portal can delay action. Use the decision table below to route your loan harassment report to the exact authority with jurisdiction:
|
Type of Issue / Entity |
Primary Official Portal / Helpline |
Jurisdiction & Action Taken |
|
Unregistered / Illegal Loan App (7-day APK traps, no RBI-registered NBFC partner) |
RBI Sachet Portal (sachet.rbi.org.in) + Cyber Crime Portal (cybercrime.gov.in) |
Routes sachet rbi org in complaints to the State Level Coordination Committee (SLCC) and state police to block illegal operators. |
|
Contact Shaming, Morphed Photos & Threats |
National Cyber Crime Helpline (1930) & cybercrime.gov.in + Local Police FIR |
Investigates criminal extortion, identity theft, and privacy violations under the IT Act and Bharatiya Nyaya Sanhita. |
|
UPI / Bank Money Lost to Advance-Fee Fraud |
Dial 1930 Immediately + Report to Your Bank's Fraud Desk |
Initiates an urgent lien/freeze on the fraudster's bank or UPI merchant account during the golden hour. |
|
RBI-Registered NBFC or Bank Misconduct |
Lender's GRO → RBI Integrated Ombudsman (cms.rbi.org.in / 14448) |
Enforces RBI Fair Practices Code; resolves recovery misconduct if the regulated lender fails to reply within 30 days. |
|
Spam Loan Calls / Unsolicited SMS Links |
TRAI DND (1909) & Chakshu Portal (sancharsaathi.gov.in/sfc) |
Blocks telemarketing numbers and fraudulent SMS headers used to distribute fake loan APKs. |
Step-by-Step Process: How to File a Fake Loan App Harassment Complaint Online
If you are experiencing loan app harassment or have fallen victim to loan scams, follow these seven steps in order to protect yourself and build an actionable case file:
-
Stop Paying Extortion or "Extension" Demands: Never transfer additional money to personal UPI IDs or QR codes to "close" or "extend" an illegal loan. Fraudulent operators rarely stop loan harassment after receiving payment and typically escalate demands.
-
Collect and Back Up Digital Evidence: Before uninstalling anything, capture clear screenshots of the app's Play Store or APK download link, the loan sanction screen, threatening WhatsApp/SMS chats, call logs, morphed images, and bank/UPI transaction receipts showing UTR numbers.
-
Call the National Cyber Crime Helpline (1930): Dial 1930 (available 24×7) to register an immediate alert. If you transferred money to scammers, calling 1930 quickly helps cybercrime teams flag and freeze the recipient account.
-
Register a Formal Report on cybercrime.gov.in: Visit cybercrime.gov.in, click File a Complaint, select Report Other Cyber Crime (or Report Financial Fraud), log in with your mobile number via OTP, enter incident details, upload your evidence screenshots, and save the acknowledgement number.
-
Submit Sachet RBI Org In Complaints: Go to sachet.rbi.org.in, click File a Complaint, select your state, choose Loan App or Unknown / Suspicious Entity, enter the app name, phone numbers, and website/APK links, attach your evidence, and note your Sachet reference number.
-
Revoke App Permissions and Secure Your Phone: Open your phone's Settings → Apps, select the fraudulent application, revoke access to Contacts, Storage/Photos, Location, SMS, and Camera, and uninstall the app. Immediately reset your UPI PIN and mobile banking passwords.
-
Alert Your Contacts and Flag the App: Send a brief message to close family members and colleagues warning them that an unauthorised app is spoofing your details, and report the app using the Flag as inappropriate option on the Google Play Store.
Evidence Checklist Before Submitting Loan Fraud Complaints
Incomplete submissions are the primary reason loan fraud complaints stall during police or regulatory review. Keep these items ready before logging your fake loan app harassment complaint:
-
App & Developer Identifiers: Exact app name, package name/URL, developer email, or WhatsApp link from which you downloaded the APK.
-
Financial Trail: Bank account statements, UPI transaction IDs (12-digit UTR numbers), and beneficiary UPI IDs or account numbers.
-
Harassment Proof: Uncropped screenshots showing caller phone numbers, timestamps, abusive text messages, and any doctored images sent to you or your contacts.
-
KYC Exposure Record: Note whether you uploaded your PAN, Aadhaar, or selfie so you can monitor your credit bureau reports for unauthorised inquiries.
Regulated Digital Lending vs. Predatory Loan Scams
Understanding how RBI-compliant platforms operate helps you avoid loan scams altogether. Compare verified digital lending standards against illegal loan app harassment operators:
|
Key Parameter |
RBI-Regulated Platform (e.g., Pocketly) |
Illegal / Fake Loan App |
|
Regulated Lending Partner |
Clearly names its RBI-registered NBFC or bank partner (Speel Finance Company Private Limited for Pocketly). |
Conceals lender identity or lists an unregistered shell company. |
|
Upfront Fee Demands |
Zero advance cash fees; applicable processing fees (0% to 9.4% inclusive of 18% GST on Pocketly) are disclosed upfront. |
Demands upfront "file charges," "GST," or "insurance" via personal UPI before disbursal. |
|
Key Fact Statement (KFS) |
Provides a mandatory KFS displaying exact APR, interest rate, tenure, and total repayment obligation before acceptance. |
Issues no KFS or written contract, hiding arbitrary daily penalties. |
|
Repayment Window |
Realistic multi-month tenures (61 days to 9 months on Pocketly). |
Predatory 7-day or 14-day debt traps. Compare costs in our guide on 7 days loan vs 30 days loan. |
|
Data Privacy & Permissions |
Never scrapes contacts or photo galleries; certified under ISO 27001:2023 security standards. |
Harvests contact lists and media files to enable loan harassment. |
|
Grievance Redressal |
Publishes a Grievance Redressal Officer (GRO) and adheres to RBI's Fair Practices Code. |
Uses untraceable VoIP numbers and blocks complainants. |
How We Ensure Safe, Transparent Digital Credit at Pocketly
If you are comparing options to find the best loan app in India for your requirements, check the regulated lender, APR, processing fees, repayment tenure, eligibility criteria, Key Fact Statement, and total repayment obligation rather than promotional claims.
At Pocketly, we built our platform to give students, first-jobbers, salaried professionals, freelancers, and self-employed earners a safe, compliant alternative to unverified lenders under our responsible lending commitment:
-
RBI-Registered NBFC Backing: All personal loans on Pocketly (from ₹1,000 to ₹50,000) are sanctioned and disbursed directly to your bank account by Speel Finance Company Private Limited (CIN: U65920MH1995PTC090558), an RBI-registered NBFC.
-
Upfront Cost & KFS Disclosures: Our monthly reducing interest ranges from 2% to 3% per month, with processing fees between 0% and 9.4% (inclusive of 18% GST), repayment tenures of 61 days to 9 months, and a standardized Key Fact Statement showing your exact APR before you accept funds.
-
Dedicated Borrower Categories:
-
If you receive a regular monthly paycheck, explore our personal loan for salaried applicants.
-
If you run a business or freelance, explore our personal loan for self employed applicants.
-
If you earn through stipends, gigs, or regular allowances without corporate payslips, our personal loan for non salaried option may be relevant.
-
Verified Support Channels: You can reach our customer care team directly via our toll-free helpline at 1800 889 8941, WhatsApp at +91 89040 51555, or email at care@support.pocketly.in, or review our grievance redressal policy anytime.
-
Realistic Digital Processing: While phrases like instant personal loan online in 2 minutes describe how quickly you can complete digital onboarding and Video KYC on our app, final approval and bank disbursal always depend on automated verification and underwriting criteria.
Before choosing any loan amount, plan your monthly budget with our personal loan EMI calculator and check your debt-to-income comfort level using our FOIR calculator.
Common Mistakes to Avoid When Dealing with Loan App Harassment
-
Sending Money to "Stop" Contact Messages: Paying scammers never deletes your data from their servers; it only marks your number as an active target for repeat loan app harassment.
-
Filing Unregulated App Complaints on RBI CMS Instead of Sachet: The RBI Integrated Ombudsman (cms.rbi.org.in) handles complaints only against RBI-regulated banks and NBFCs. Use sachet rbi org in complaints (sachet.rbi.org.in) and cybercrime.gov.in for illegal, unregistered apps.
-
Downloading APK Files from WhatsApp or SMS Links: Never install lending apps outside the official Google Play Store or Apple App Store.
-
Ignoring Legitimate EMI Due Dates: Unlike illegal loan scams, regulated NBFCs report repayment behaviour to credit bureaus. If you ever face temporary cash flow pressure on a regulated loan, read our guide on loan ki kissht nahi bhar pa rahe and understand automated debits via UPI mandate explained.
Also Read: Latest Guides & News on Pocketly
-
Loan Ki Kissht Nahi Bhar Pa Rahe? EMI Late Hone Par Kya Hoga?
-
Gold Loan Defaults Rise in India: Key Takeaways from CIBIL Report 2026
Final Takeaway: Report Loan App Harassment Fast & Borrow Only from Regulated Platforms
Filing a fake loan app harassment complaint promptly across 1930, cybercrime.gov.in, and sachet.rbi.org.in creates an official enforcement record and helps authorities block predatory loan scams. Protect your personal data by never installing unverified APK links, refusing advance-fee demands, and verifying the RBI-registered NBFC behind every digital lending platform.
When you need transparent, small-ticket personal credit from ₹1,000 to ₹50,000 backed by an RBI-registered NBFC and clear Key Fact Statement disclosures, we are here to help:
Frequently Asked Questions (FAQs)
1. How do I file a fake loan app harassment complaint online in India?
To file a fake loan app harassment complaint, gather screenshots of threatening messages and UPI receipts, call the National Cyber Crime Helpline at 1930, log a detailed cybercrime report on cybercrime.gov.in, and report the unauthorised app on the RBI Sachet Portal (sachet.rbi.org.in).
2. What is the difference between sachet rbi org in complaints and the RBI Ombudsman?
Sachet rbi org in complaints (sachet.rbi.org.in) are meant for reporting illegal, unregistered loan apps and unauthorised financial schemes so regulators and state police can block them. In contrast, the RBI Integrated Ombudsman (cms.rbi.org.in) handles complaints against RBI-registered banks and NBFCs if your grievance remains unresolved after 30 days.
3. Should I pay the money demanded by a fake loan app to stop loan harassment?
No, you should never pay extortion demands or "extension fees" to stop loan harassment. Fraudulent operators keep demanding repeated payments even after receiving money; instead, stop all communication, preserve screenshots, and file fraud loan complaints on cybercrime.gov.in.
4. Is it legal for loan recovery agents to call my contacts or send morphed photos?
No, contacting your relatives, colleagues, or employer, or circulating morphed images is strictly illegal under RBI Digital Lending Guidelines and Indian cybercrime laws. If you experience such loan app harassment, submit the call logs and screenshots as evidence on cybercrime.gov.in and at your local police station.
5. How can I verify whether a loan app is genuine before applying?
Check whether the app clearly names an RBI-registered NBFC or bank partner, provides a standardized Key Fact Statement (KFS) upfront, disburses funds directly from the NBFC's bank account, and never requests access to your contacts or photo gallery. You can cross-check regulated apps on the RBI's official Digital Lending Apps directory on rbi.org.in.
6. How does Pocketly protect borrowers from loan scams and data misuse?
At Pocketly, all personal loans from ₹1,000 to ₹50,000 are underwritten and disbursed directly by our RBI-registered NBFC partner, Speel Finance Company Private Limited (CIN: U65920MH1995PTC090558), with ISO 27001:2023 security certification, zero contact scraping, and upfront KFS disclosures.
7. Can I get an instant personal loan online in 2 minutes safely without falling for fraud?
Completing digital KYC and application steps on our app takes only a few minutes, though the phrase instant personal loan online in 2 minutes refers to application speed rather than guaranteed approval or disbursal. Legitimate lenders always perform identity verification and underwriting checks before transferring funds.
8. What should I check when comparing options for the best loan app in India?
If you are comparing platforms to find the best loan app in India for your needs, verify the RBI-registered NBFC partner, annualized APR, processing fees, repayment tenure, Key Fact Statement disclosures, and published Grievance Redressal Officer details.
9. Can salaried, self-employed, and non-salaried applicants apply for a loan with Pocketly?
Yes. You can explore our personal loan for salaried, personal loan for self employed, or personal loan for non salaried options for credit lines from ₹1,000 to ₹50,000, subject to our applicable eligibility and underwriting criteria.
10. How can I estimate my monthly EMI before applying with Pocketly?
Before applying, use our personal loan EMI calculator to check your estimated monthly installment and total repayment obligation so your loan fits comfortably within your monthly income.