

Staring at an automated loan rejection sms on your smartphone right when you urgently need ₹10,000 for a medical bill, month-end rent, or a sudden family trip is genuinely frustrating. One moment you are expecting funds to land in your savings account; the next second, your phone buzzes with a cold message rejected notification stating: "We regret to inform you that your application cannot be processed due to internal policy norms."
If you have recently been rejected for loan approval by a traditional bank, take a breath—you are far from alone. In 2026, automated credit underwriting engines reject millions of applications across India every quarter, often over minor technical mismatches rather than genuine repayment inability. Understanding the exact reason for personal loan rejection puts you back in control so you don't trigger repeated hard bureau inquiries that damage your financial profile.
At Pocketly, we speak every day with salaried first-jobbers, freelancers, and students who felt locked out by legacy bank gatekeeping. While conventional banks routinely decline thin-file borrowers, Pocketly is India's Most Trusted Financial App used by 20M+ of Happy Users, built to evaluate real-time cash flows rather than penalizing young applicants over missing credit histories.
Quick Answer: Why Was My Personal Loan Rejected?
When a loan rejected alert arrives, the most common reasons for personal loan rejection in India include a low or zero CIBIL score (under 700), a high Fixed Obligation to Income Ratio (FOIR above 50%), incomplete KYC or address mismatches, unstable employment history, or multiple simultaneous loan inquiries. If your traditional bank application was declined, you can explore small-ticket digital credit from ₹1,000 up to ₹50,000 with Pocketly, where eligible users can apply for instant personal loans, no CIBIL score needed at Pocketly, through a 100% digital process approved in roughly 7 minutes.
Decoding Your Loan Rejection SMS: What Cryptic Bank Alerts Really Mean
Under Reserve Bank of India (RBI) fair practices guidelines, regulated lenders must communicate application outcomes transparently. However, automated system templates often use vague phrasing when your loan rejected alert lands:
|
SMS / Email Notification Text |
Underlying Underwriting Trigger |
Practical Next Step |
|
"Loan parameters not meeting the loan criteria" |
Age, minimum monthly salary, city pin code, or employer category falls outside the lender's internal policy matrix. |
Check eligibility thresholds beforehand using our personal loan eligibility calculator before reapplying. |
|
"Application declined due to credit bureau norms" |
CIBIL/Experian score is below the bank's 700–750 cutoff, or you have a "zero/thin" credit history. |
Download your bureau report to check for errors, or explore cash-flow-based micro-credit up to ₹50,000. |
|
"Unable to verify KYC / demographic details" |
Spelling mismatch between PAN and Aadhaar, blurry Video KYC, or unserviceable residential pin code. |
Align your PAN and Aadhaar records through official UIDAI/NSDL portals before submitting fresh forms. |
|
"High existing debt obligations observed" |
Existing EMIs and credit card dues consume over 50% of your net monthly paycheck. |
Pay down small revolving card dues first and check your safe borrowing ratio via our FOIR calculator. |
Top 8 Personal Loan Rejection Reasons in India (2026)
When analyzing loan rejection reasons across urban and semi-urban Indian borrowers, eight recurring triggers explain nearly 90% of automated declines:
1. Low or Non-Existent CIBIL Score (Thin Credit File)
Conventional banks rely heavily on bureau scores ranging from 300 to 900. If past late payments dragged your score below 680—or if you are a 22-year-old graduate with "-1" or "NH" (No History)—traditional scoring models automatically mark your application high risk.
2. High Fixed Obligation to Income Ratio (FOIR)
Lenders calculate how much of your monthly salary is already locked into existing EMIs and rent. When existing commitments exceed 45% to 50% of take-home income, automated engines flag repayment strain as a primary reason for personal loan rejection.
3. Too Many Simultaneous Loan Inquiries ("Credit Hunger")
Every time you submit a formal loan application, the lender pulls a "hard inquiry" from credit bureaus. Submitting five applications across different portals in 48 hours signals financial desperation and lowers your score, creating a self-reinforcing cycle of reasons for loan rejection.
4. Frequent Job Switches or Probation Periods
Salaried applicants who have spent fewer than 3 to 6 months with their current employer—or those still on corporate probation—frequently face automated rejection from legacy retail banks.
5. Inconsistent Bank Cash Flows or Frequent Cheque/NACH Bounces
Even with a decent salary, recent inward auto-debit bounces or near-zero month-end balances signal cash-flow stress. Learn how failed mandates impact your profile in our breakdown of unexpected EMI bounce charges.
6. Unverified Employer or Non-Salaried Income Structure
Banks maintain internal lists of categorized corporate employers. Freelancers, gig workers, independent consultants, and students without formal salary slips routinely get rejected for loan applications at conventional branches.
7. KYC & Documentation Mismatches
Minor discrepancies—such as an initial instead of a full middle name on your PAN card versus your bank account, or an outdated residential address—cause instant automated message rejected failures during digital onboarding.
8. High Credit Card Utilization Ratio
Consistently using more than 30% to 40% of your sanctioned credit card limit signals heavy reliance on revolving debt, which drags down your bureau standing even if you pay the minimum amount due on time.
What "Bank Does Not Provide Loan For" & "Loan Parameters Not Meeting the Loan Criteria" Mean
Borrowers frequently encounter two confusing phrases when speaking with customer support after a decline:
-
"Bank does not provide loan for..." — Regulated banks restrict unsecured personal loans for speculative purposes, margin trading in equities/crypto, gambling, or business setups lacking vintage proof. Additionally, if your residential pin code falls outside a bank's physical collection radius, their system automatically flags the location as non-serviceable.
-
"Loan parameters not meeting the loan criteria" — Every lender programs hard rule-engine filters (e.g., minimum age 21, minimum net salary ₹25,000, or minimum loan ticket ₹50,000). If you only need ₹8,000 for a quick emergency, applying at a bank whose minimum floor is ₹50,000 results in an automatic parameter mismatch.
Traditional Bank Underwriting vs. Pocketly Cash-Flow Credit
Understanding why a legacy bank declined your request—and how modern digital micro-credit evaluates applicants differently—helps you pick the right platform:
|
Evaluation Factor |
Conventional Commercial Bank |
Pocketly Digital Personal Credit |
|
Minimum Loan Amount |
₹50,000 – ₹1,00,000 (Declines small requests) |
₹1,000 – ₹50,000 (Built for exact micro-needs) |
|
Credit Score Cutoff |
Rigid 700–750+ CIBIL score required |
No prior CIBIL score needed to apply |
|
Underwriting Focus |
Historical bureau records & corporate category |
Real-time banking continuity & digital KYC |
|
Income Proof Needed |
3–6 months salary slips, Form 16, ITR |
100% paperless PAN, Aadhaar & Video KYC |
|
Approval Turnaround |
3 to 7 working business days |
Approved in roughly 7 minutes; direct bank credit |
|
Regulated Lending Partner |
Scheduled Commercial Bank |
Speel Finance Co. Pvt. Ltd. (RBI-Registered NBFC) |
Real-World Scenarios: How Indians Recover After Getting Rejected for Loan
Seeing how borrowers navigate personal loan rejection reasons in everyday Indian situations turns frustration into a clear action plan: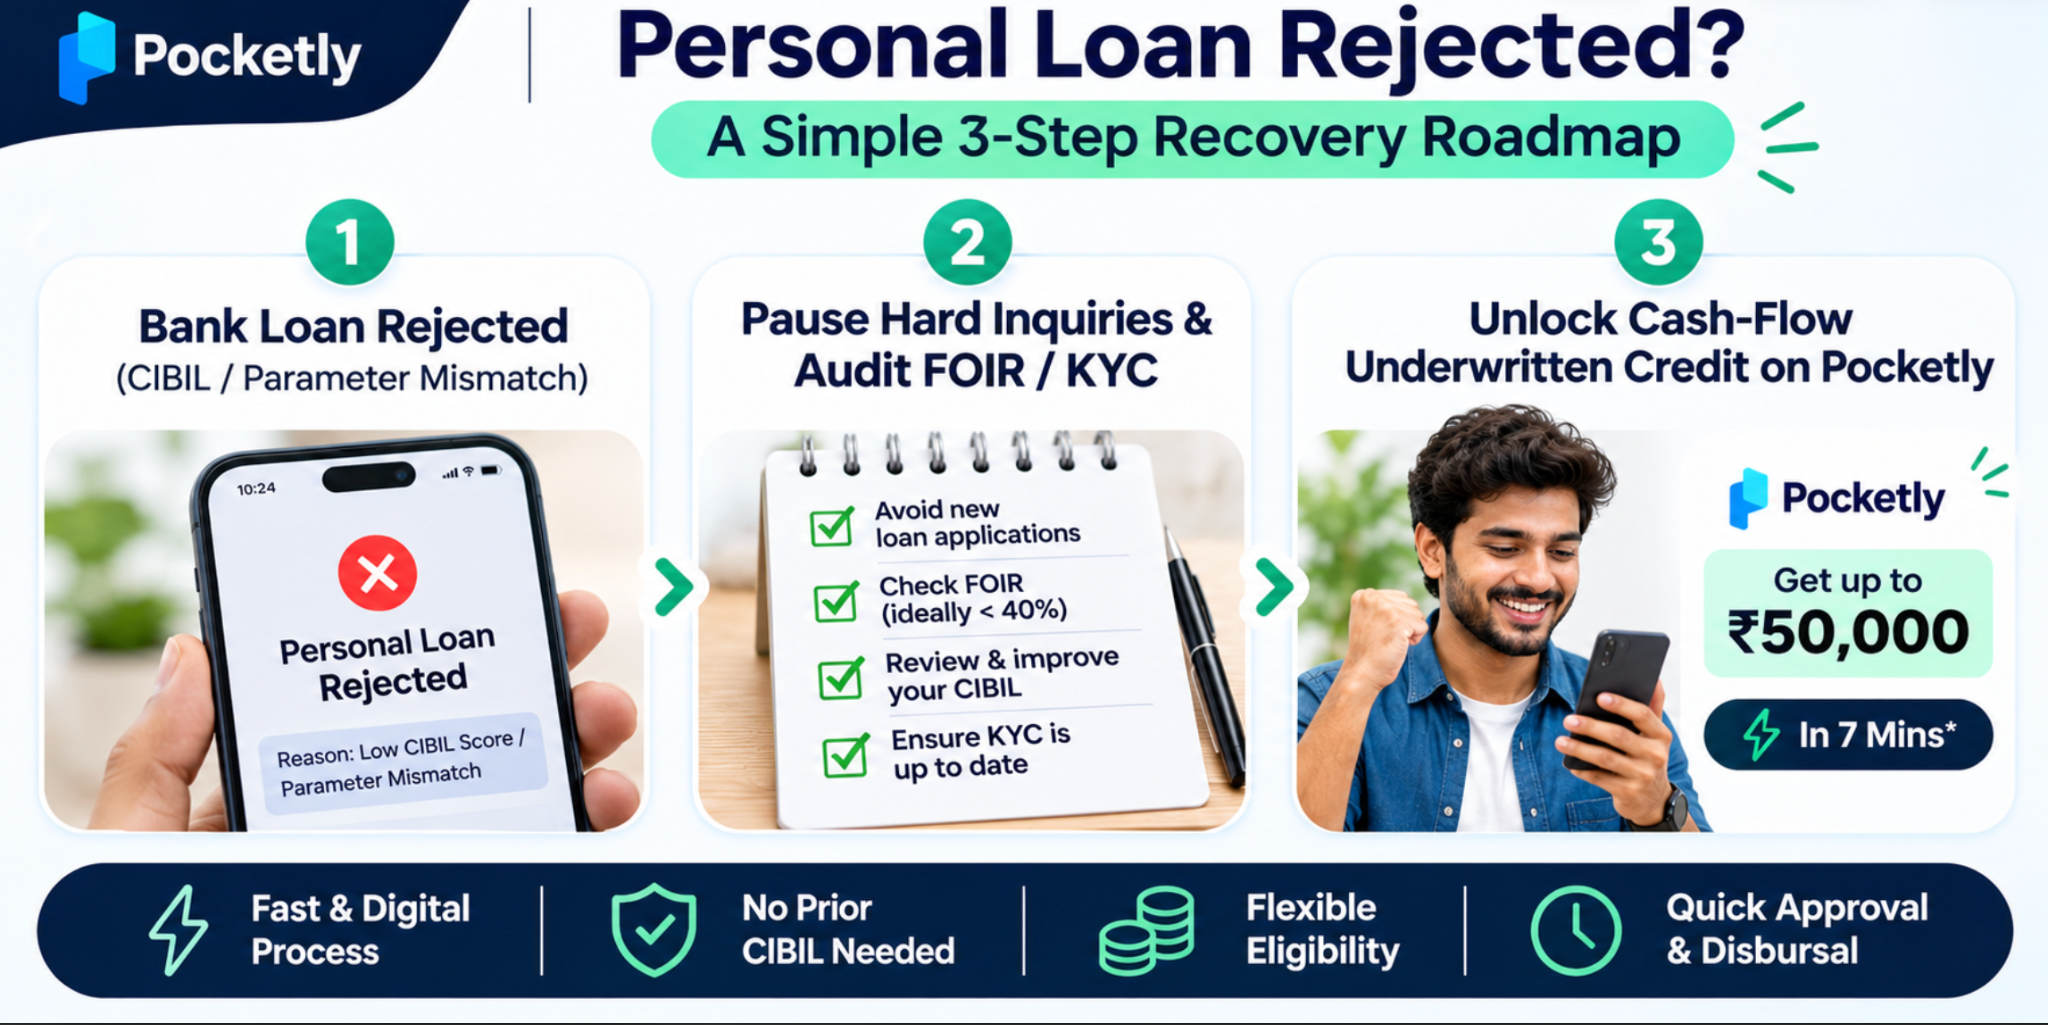 Scenario 1: The First-Jobber With Zero Credit History ("NH" Score)
-
The Situation: Siddharth, a 23-year-old analyst in Bengaluru drawing ₹32,000 per month, applied at a major private bank for ₹18,000 to cover a rental security deposit shortfall. Because he had never owned a credit card, his application triggered an immediate loan rejection sms citing insufficient bureau history.
-
The Smart Solution: Instead of applying blindly at three more banks, Siddharth explored our personal loan for salaried option. Because you can apply for instant personal loans, no CIBIL score needed at Pocketly, his application was evaluated on banking continuity and approved within minutes.
Scenario 2: The Freelancer Facing "Loan Parameters Not Meeting the Loan Criteria"
-
The Situation: Meera, a freelance content strategist in Mumbai, needed ₹15,000 for urgent laptop repairs while waiting on a client invoice. Her bank declined her request because she lacked corporate salary slips.
-
The Smart Solution: Meera checked her monthly repayment comfort using our personal loan EMI calculator and applied through our dedicated personal loan for self-employed tier, accessing transparent credit without branch paperwork.
Scenario 3: Active Trader Protecting Capital Without Triggering Hard Inquiries
-
The Situation: An active retail trader in Pune needed ₹20,000 in short-term personal liquidity during a temporary market dip so he wouldn't have to sell core equity positions at a loss. After a bank rejected his small-ticket request due to minimum amount rules, he paused further bank applications to protect his credit score and used Pocketly's 100% digital credit line instead.
Step-by-Step Recovery Plan: What to Do Immediately After a Rejection
If your screen just flashed a loan rejected notice, follow this five-step checklist before submitting another application:
-
Stop Applying Elsewhere Immediately: Wait at least 30 to 60 days before applying to another traditional bank so multiple hard inquiries do not compound the damage to your CIBIL report.
-
Pull Your Free Credit Bureau Report: Download your latest report from CIBIL, Experian, Equifax, or CRIF High Mark to verify there are no erroneously reported late payments or unfamiliar accounts.
-
Fix KYC & Address Discrepancies: Ensure your name, date of birth, and mobile number match identically across your PAN card, Aadhaar records, and active savings bank account.
-
Lower Credit Card Utilization & Check FOIR: Pay down existing credit card balances below 30% of your limit and verify your debt-to-income ratio using our FOIR calculator and loan affordability calculator.
-
Explore Cash-Flow-Based Micro-Credit (Up to ₹50,000): If you need immediate funds between ₹1,000 and ₹50,000, Pocketly is India's Most Trusted Financial App used by 20M+ of Happy Users, offering 100% digital KYC, approval in roughly 7 minutes, and direct bank disbursal via our RBI-registered NBFC partner, Speel Finance Company Private Limited (CIN: U65920MH1995PTC090558).
Risk Management & Beginner Mistakes to Avoid
Recovering from a declined loan requires disciplined financial habits:
-
Never Fall for Predatory "Guaranteed Approval" 7-Day APKs: Desperate borrowers who get rejected for loan requests sometimes click sketchy links promising zero-check loans. These illegal apps deduct 35%–40% upfront and harass users within 7 days. Read our consumer guide on 7 days loan vs 30 days loan and explore safe alternatives in our guide to bad credit loans in India.
-
Review Your Key Fact Statement (KFS) Carefully: Under RBI Digital Lending Directions, every legitimate lender must disclose exact monthly interest (starting from 2% to 3% per month on Pocketly), processing fees (0% to 9.4% inclusive of 18% GST), repayment tenures (61 days to 9 months), and maximum APR upfront before acceptance.
-
Strengthen Long-Term Financial Resilience: Organize monthly spending with our 50 30 20 rule calculator, curb impulse spending via our guide on lifestyle inflation and savings, and build micro-reserves steadily in digital gold. Students and non-salaried earners can also explore starter credit through our loan for non-salaried pathway.
Bounce Back Stronger with Pocketly Today
A single bank rejection does not define your financial future—it simply means legacy underwriting wasn't built for your current cash-flow profile. By understanding the real reasons for loan rejection, protecting your credit score from unnecessary hard inquiries, and choosing transparent digital platforms, you can handle short-term liquidity needs with confidence.
Ready to experience fast, paperless digital credit built for young India?
-
👉 Apply Now for Instant Personal Loans up to ₹50,000 on Pocketly
-
👉 Check Your Eligibility Before Applying with Our Personal Loan Eligibility Calculator
-
👉 Plan Your Monthly Installments on the Personal Loan EMI Calculator
Frequently Asked Questions (FAQs)
1. Why did I get a loan rejection SMS even with a steady salary?
A loan rejection sms can occur even with steady income if your existing EMIs push your FOIR above 50%, you are still in your corporate probation period, you submitted multiple loan inquiries recently, or your KYC details have minor spelling mismatches.
2. What does "loan parameters not meeting the loan criteria" mean?
When a lender states loan parameters not meeting the loan criteria, it means one or more baseline rules—such as minimum loan ticket size (often ₹50,000 at banks), minimum age, residential pin code serviceability, or CIBIL cutoff—did not align with their automated policy filter.
3. Does getting rejected for loan approval lower my CIBIL score?
The rejection itself is not recorded as a negative mark on your CIBIL report. However, the hard credit inquiry triggered when you applied can lower your score by 3 to 5 points, and multiple back-to-back applications can signal credit hunger.
4. Can I get an instant personal loan up to ₹50,000 if my bank loan was rejected?
Yes. If a traditional bank declined your request due to thin credit history or small ticket size, you can apply for instant personal loans, no CIBIL score needed at Pocketly. Eligible users can access ₹1,000 to ₹50,000 with 100% digital KYC and approval in roughly 7 minutes.
5. What are the top reasons for personal loan rejection among young professionals?
The most common reasons for personal loan rejection among young earners include having a zero/thin CIBIL history, frequent job changes within 6 months, high credit card utilization above 40%, and incomplete digital KYC verification.
6. How long should I wait to reapply after receiving a message rejected alert?
After receiving a message rejected notification from a traditional bank, wait at least 30 to 60 days before reapplying to another bank so you can fix underlying credit or KYC issues and avoid clustering hard bureau inquiries.
7. What does "bank does not provide loan for" mean during application screening?
The phrase bank does not provide loan for usually refers to restricted end-use policies (such as speculative stock/crypto trading) or geographic and employer category exclusions where a bank does not service specific pin codes or non-salaried profiles.
8. Is Pocketly safe and regulated by the RBI?
Yes. Pocketly is India's Most Trusted Financial App used by 20M+ of Happy Users. All loans are sanctioned and disbursed directly to your bank account by our RBI-registered NBFC partner, Speel Finance Company Private Limited, in full compliance with published responsible lending norms.