

Instant Personal Loan for Trading in 2026–2027: Can You Get a Loan for Trading?
Trading often starts with a simple thought: “If I had more capital, I could take bigger opportunities.”
For students, first-jobbers, salaried professionals, freelancers and self-employed individuals, arranging additional funds can seem difficult. This is why searches such as loan for trading, loan for share trading, and personal loan for F&O trading are becoming increasingly relevant among young borrowers.
But there is an important distinction to understand.
There isn't necessarily a specific financial product called a “loan for trading.” Instead, an eligible borrower may consider a personal loan, depending on the lender's terms and the intended use of funds.
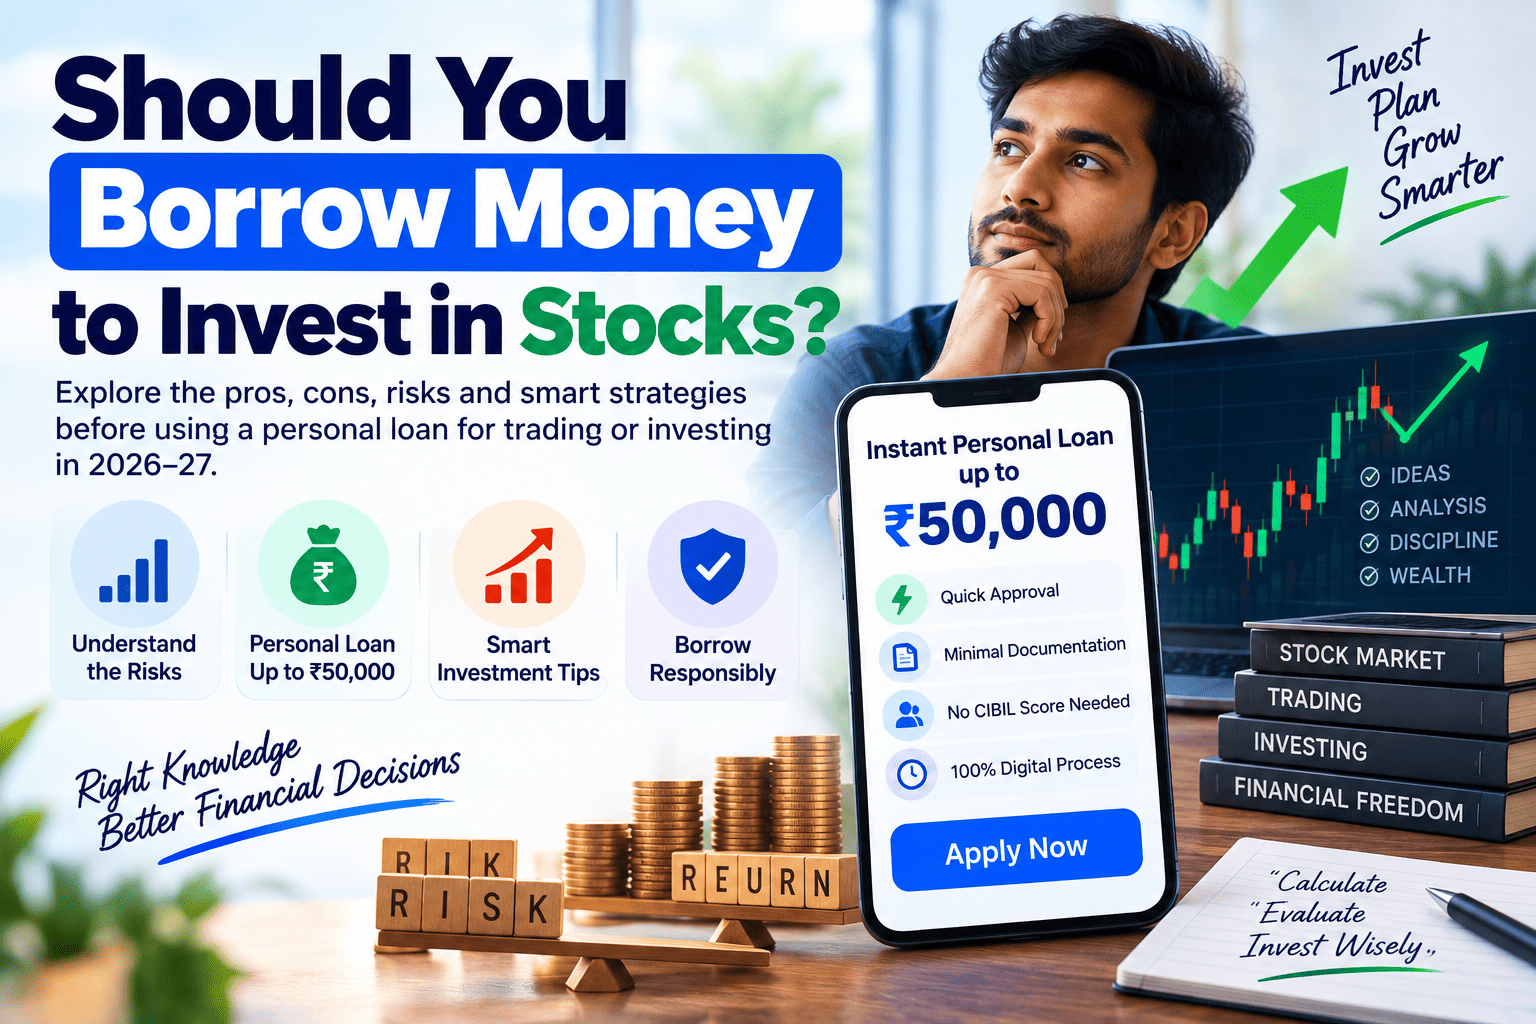
At Pocketly, eligible borrowers can access personal loans of up to ₹50,000, with a completely digital application journey. Pocketly’s personal loans do not require a CIBIL score and can be approved within minutes, subject to eligibility.
Quick Answer: Can I Get a Loan for Trading?
Yes, an eligible borrower may take a personal loan and use the funds for a personal requirement, including purposes that are permitted under the applicable loan terms. Pocketly does not offer a separate “loan for trading” product; it provides personal loans of up to ₹50,000 based on eligibility. Always check the loan agreement and understand the repayment cost before borrowing.
What Is a Loan for Trading?
A loan for trading generally refers to borrowing money that a person intends to use as trading capital.
However, borrowers should not confuse a personal loan with a dedicated trading facility.
With a personal loan:
-
You borrow a predetermined amount.
-
The lender charges interest and applicable fees.
-
You have a defined repayment period.
-
You must repay the borrowing regardless of whether your trading activity makes a profit or loss.
That last point is crucial.
The market can move down, but your loan repayment obligation doesn't move down with it.
This is why financial discipline is essential when considering borrowed funds.
Can I Get a Loan for Trading Stocks in India?
If you are searching “can i get a loan for trading stocks india”, the answer depends on the lender's eligibility requirements and applicable loan terms.
A personal loan is different from a trading account or broker-provided margin facility.
Before borrowing, consider:
-
Your monthly income.
-
Existing EMIs.
-
Total cost of the loan.
-
Your ability to repay if the investment loses money.
-
Whether the intended use complies with the loan agreement.
-
Your overall financial risk.
For Pocketly, eligibility is assessed before the loan is offered. Its published information includes an age range of 18–40 years and KYC requirements such as personal details, address proof, verified email, Video KYC and PAN information.
Personal Loan for F&O Trading: Think Twice Before Borrowing
The keyword personal loan for F&O trading reflects a particularly risky use case.
Futures and options can magnify market exposure. A beginner may see a small amount of capital and imagine significantly larger returns, but losses can also happen quickly.
Before using borrowed money for F&O, ask:
-
Can I repay the loan without trading profits?
-
Do I understand options and futures?
-
Can I tolerate a substantial loss?
-
Do I have an emergency fund?
-
Am I borrowing because I have a genuine need or because I want to recover previous losses?
Never take another loan simply to recover a previous trading loss.
Pocketly Personal Loan for Trading: Is There a Separate Product?
This is where borrowers should be precise.
Pocketly does not advertise a separate “loan for trading” product. Pocketly provides personal loans of up to ₹50,000 to eligible borrowers.
Because it is a personal loan, the borrower can use the funds for eligible personal requirements subject to the applicable loan agreement and terms.
Pocketly's published loan information includes:
|
Pocketly loan feature |
Published details |
|
Loan amount |
₹1,000–₹50,000 |
|
Tenure |
61 days to 9 months |
|
Interest rate |
2%–3% per month |
|
Processing fee |
0%–7.5% + applicable GST |
|
Published APR range |
30%–121% |
|
Foreclosure charge |
2.5% of principal outstanding |
Pocketly also states that its application process is 100% digital, with minimum KYC and fast loan processing.
Loan for Share Trading vs Using Your Own Money
|
Factor |
Own trading capital |
Borrowed personal loan |
|
Repayment obligation |
No |
Yes |
|
Interest cost |
No loan interest |
Yes |
|
Market loss |
Your capital falls |
Capital falls + loan remains |
|
Financial pressure |
Lower |
Higher |
|
Suitable for beginners |
Relatively safer |
Higher risk |
|
Emergency fund impact |
Can be separated |
Must maintain separately |
The key lesson is simple: don't assume access to more money automatically creates better trading results.
Example: What Happens With a ₹50,000 Loan?
Imagine an eligible borrower receives a ₹50,000 personal loan.
Suppose ₹20,000 is used for a permitted personal requirement and the borrower considers putting ₹30,000 into trading.
If the trading capital falls by 25%:
₹30,000 × 25% = ₹7,500 loss
The trading account has lost ₹7,500, but the loan repayment obligation remains.
That's why you should calculate affordability before applying, not after entering a trade.
Why Pocketly Can Be Useful for Young Borrowers
Pocketly is designed around small-ticket, digital personal credit for young Indians.
According to Pocketly's published information:
-
Personal loans of up to ₹50,000
-
No CIBIL score required, subject to its eligibility process
-
Digital application journey
-
Fast approval/disbursal
-
Flexible repayment options
-
Minimum KYC
-
Loans available to eligible salaried and self-employed borrowers
-
Responsible lending practices
-
RBI-registered NBFC lending partner/entity disclosed by Pocketly
Pocketly's responsible-lending policy also says borrowers should provide accurate information, understand the terms and conditions, and make repayments on time.
With 20M+ happy users highlighted in Pocketly's brand positioning, the platform aims to make personal borrowing simpler for India's young borrowers.
7 Things to Check Before Taking a Loan for Trading
-
Check your repayment capacity.
-
Understand the APR, not just the monthly interest rate.
-
Calculate processing fees and GST.
-
Keep emergency savings separate.
-
Never depend on trading profits to pay your EMI.
-
Avoid borrowing to chase market losses.
-
Read the loan agreement before accepting the offer.
Final Takeaway
Searching for a loan for trading doesn't necessarily mean you need a specialised trading loan.
If you're eligible, a Pocketly personal loan of up to ₹50,000 can provide access to personal credit for eligible needs, subject to the applicable loan terms. Pocketly is focused on making small-ticket personal borrowing digital, simple and accessible for young Indians.
However, trading is different from borrowing. Never assume that a market profit will pay your EMI.
If you are considering a personal loan, first understand the interest rate, APR, fees, tenure and repayment amount. Borrow only what you can comfortably repay.
Need funds for a personal requirement? Check your Pocketly eligibility and explore an instant personal loan of up to ₹50,000 subject to eligibility and applicable terms.
Frequently Asked Questions
1. Is there a specific loan for trading?
Not necessarily. A loan for trading is generally a description of how borrowed money may be intended to be used. Pocketly offers personal loans rather than a separate trading-loan product.
2. Can I get a loan for trading stocks in India?
Eligibility depends on the lender and loan terms. A personal loan may provide funds for eligible personal requirements, but you should check the applicable agreement before using borrowed funds for trading.
3. Can I get a personal loan for F&O trading?
You may search for a personal loan for F&O trading, but using borrowed money for derivatives can significantly increase financial risk.
4. Can I use a Pocketly personal loan for share trading?
Pocketly provides personal loans, not a dedicated share-trading loan. The permitted use of the loan is governed by the applicable loan agreement and terms.
5. How much personal loan can I get from Pocketly?
Pocketly's published loan details show loans ranging from ₹1,000 to ₹50,000, subject to eligibility.
6. Does Pocketly require a CIBIL score?
Pocketly's published information states that a CIBIL score is not required, subject to its eligibility process.
7. Is borrowing money to trade a good idea?
It can increase financial risk because the trading outcome is uncertain while loan repayment remains an obligation.
8. What is better: borrowed capital or own trading capital?
For most beginners, using money they can genuinely afford to lose avoids adding a fixed loan repayment obligation to uncertain market returns.
9. Can salaried people apply for Pocketly?
Pocketly provides personal loans for eligible salaried borrowers, with KYC and other eligibility requirements.
10. Can self-employed people apply for Pocketly?
Pocketly also provides personal loans for eligible self-employed borrowers, subject to its eligibility requirements.