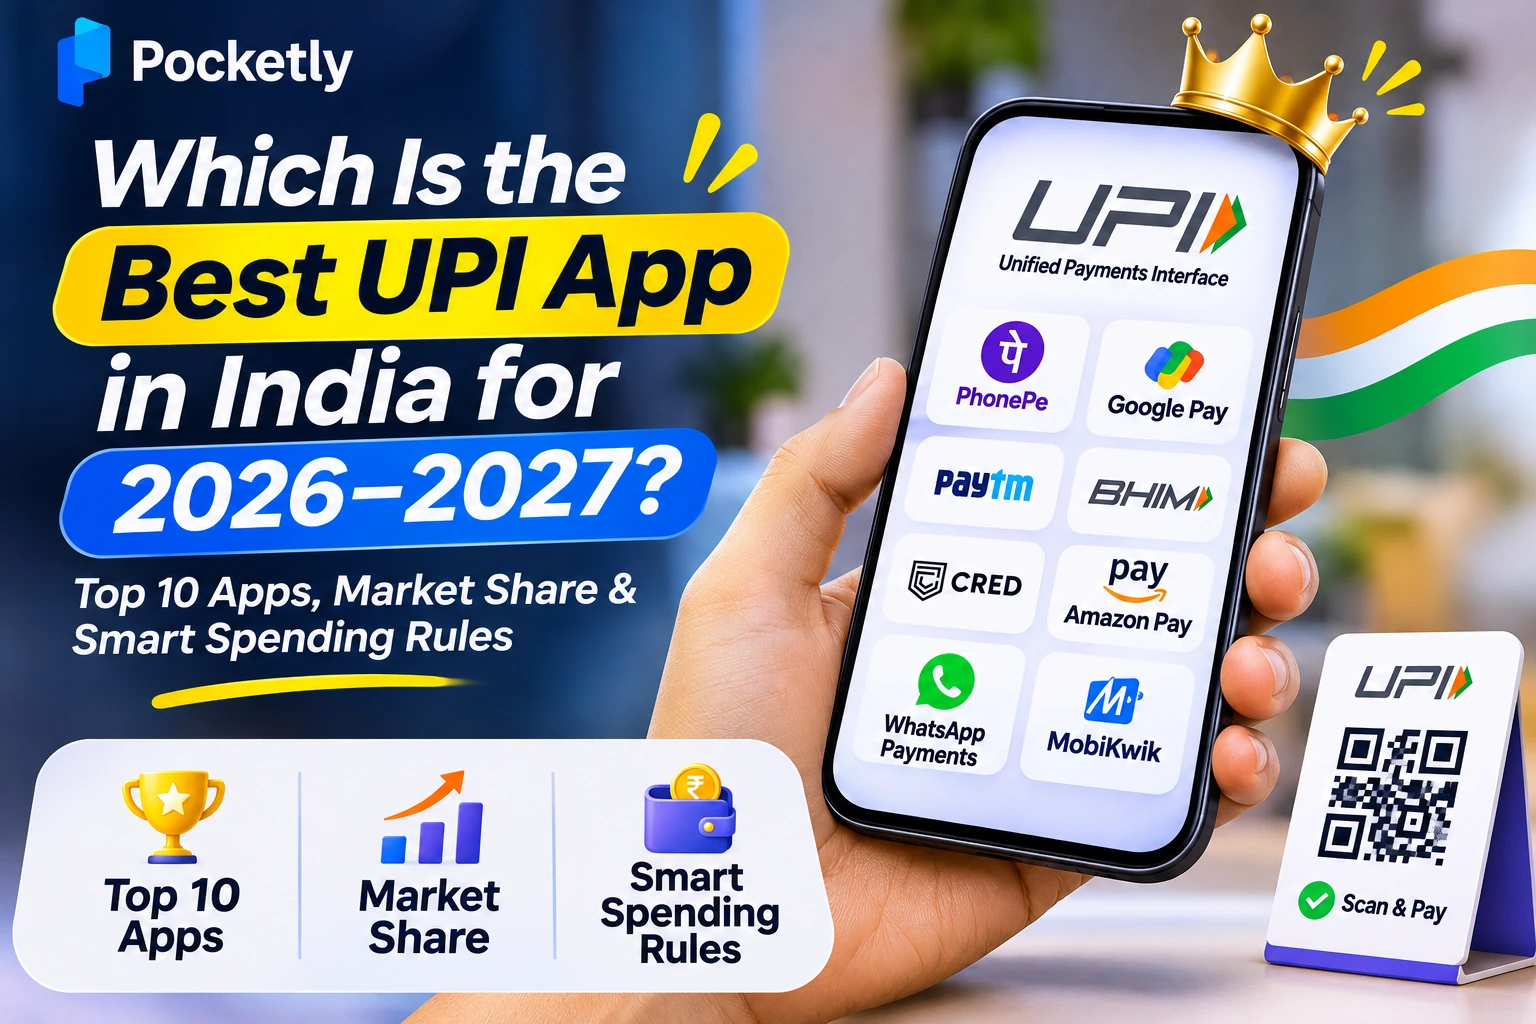


There is no single best UPI app in India for every user. The right choice depends on whether you prioritise merchant acceptance, RuPay credit card linking, cashback rewards, or a clean, ad-free interface. According to National Payments Corporation of India (NPCI) data, PhonePe and Google Pay remain the most used UPI apps in India, followed by Paytm, Navi, super.money, BHIM, CRED, and Amazon Pay. While UPI handles everyday bank-to-bank payments instantly, it only moves funds already sitting in your bank account or approved credit line meaning when month-end expenses exceed your balance, you still need a reliable short-term credit buffer like Pocketly.
Quick Answer: Which Is the Best UPI App in India?
If you are asking which is the best UPI app in India for 2026–2027, PhonePe and Google Pay lead in nationwide merchant reliability and transaction volume, BHIM offers the cleanest government-backed experience without clutter, CRED and super.money suit RuPay credit card and cashback seekers, and Navi stands out for fast, lightweight payments.
What Is a UPI App and How Does It Work in India?
A Unified Payments Interface (UPI) app is a mobile payment application built on the real-time inter-bank payment rail operated by the National Payments Corporation of India (NPCI) and regulated by the Reserve Bank of India (RBI).
Unlike legacy mobile wallets that required pre-loading cash, upi apps in india link directly to your savings bank account, overdraft account, or RuPay credit card using your registered mobile number and a 4- or 6-digit UPI PIN. When you scan a QR code or enter a Virtual Payment Address (VPA), NPCI's switch routes money instantly between banks 24/7.
Which Was the First UPI App in India?
BHIM (Bharat Interface for Money), developed by NPCI and launched on December 30, 2016, is widely recognised as the landmark first upi app in india designed for mass nationwide adoption.
NPCI initially piloted the UPI framework with 21 member banks on April 11, 2016, before rolling out BHIM later that year to simplify bank-to-bank transfers across urban and rural India without requiring IFSC codes or account numbers.
Most Used UPI App in India: NPCI Market Share Breakdown
According to NPCI ecosystem data reported in late 2026, UPI crossed 25.47 billion monthly transactions worth over ₹31.53 lakh crore and even logged a single-day peak of 97.58 crore payments during the Diwali 2026 festive corridor.
When evaluating the most used upi app in india, PhonePe leads with roughly 45.6% of listed-app transaction volume, followed by Google Pay at around 32.2% and Paytm at roughly 8.1%, while challengers like Navi and super.money continue gaining share ahead of NPCI's 30% third-party volume cap compliance timeline.
Top 10 UPI App in India (2026–2027): Side-by-Side Comparison
Comparing the top 10 upi app in india across core features helps you pick the platform that matches your daily spending habits:
|
Rank & App Name |
Developer / Backing |
Best Suited For |
Key Features (2026–2027) |
|
1. PhonePe |
PhonePe Pvt. Ltd. |
All-round daily & merchant payments |
Widest QR network, UPI Lite, RuPay credit on UPI, bill payments |
|
Google LLC |
Clean interface & P2P transfers |
Simple UI, UPI Circle, RuPay credit linking, bank-grade security |
|
|
3. Paytm |
One97 Communications |
Small-merchant QR & Soundbox ecosystem |
Fast QR scanner, UPI Lite, recurring mandates, utility bills |
|
4. BHIM |
NPCI BHIM Services Ltd. |
Clutter-free, ad-free banking |
Official NPCI app, 20+ Indian languages, UPI Lite, zero bloat |
|
5. Navi UPI |
Navi Technologies |
Fast payments & reward coins |
Lightweight interface, quick QR scans, digital financial services |
|
6. super.money |
Flipkart Group |
Cashback-focused everyday UPI |
Flat cashback on merchant scans, RuPay credit card integration |
|
7. CRED UPI |
Dreamplug Technologies |
Credit card holders & high-ticket spends |
RuPay credit on UPI, credit card bill tracking, Scan & Pay rewards |
|
Amazon India |
Frequent Amazon shoppers & bill payers |
One-tap e-commerce checkout, utility cashbacks, UPI Lite |
|
|
9. WhatsApp Pay |
Meta Platforms |
Sending money inside chats |
Zero extra app download, seamless peer-to-peer transfers |
|
One MobiKwik Systems |
Wallet + UPI combined users |
Pocket UPI without direct bank exposure, bill payments |
How to Choose the Best UPI App in India for Your Profile
Different earners rely on different payment workflows across upi apps in india:
-
College Students & First-Jobbers: Choose lightweight apps like BHIM, Google Pay, or Navi with UPI Lite enabled for small daily canteen, metro, and tea-stall payments under ₹500 without cluttering your bank statement.
-
Salaried Professionals: Pair PhonePe or Google Pay for rent and utility bills with UPI AutoPay mandates and read our guide on UPI mandate explained to manage recurring EMI debits smoothly.
-
Freelancers & Self-Employed Earners: Separate business QR collections from personal spends using Paytm or PhonePe so tax reconciliation and client tracking remain straightforward.
-
Credit Card Users: Link a RuPay credit card on CRED, PhonePe, or super.money to earn reward points on merchant QR scans while enjoying an interest-free billing window.
When UPI Isn't Enough: Bridging Cash-Flow Gaps with Pocketly
While finding the best upi app in india makes transferring money effortless, instant QR payments only work when your bank account holds enough funds. Frictionless digital scanning can quietly accelerate month-end spending, leaving students, freelancers, and salaried earners short before payday.
At Pocketly, we help you bridge temporary liquidity gaps responsibly without resorting to high-interest credit card cash withdrawals or unverified apps:
-
Small-Ticket Personal Credit (₹1,000 to ₹50,000): Apply online from your smartphone for an instant personal loan tailored to your actual need, with repayment tenures from 61 days to 9 months.
-
Regulated NBFC Transparency: Every loan on our platform is sanctioned and disbursed directly to your bank account by our RBI-registered NBFC partner, Speel Finance Company Private Limited (CIN: U65920MH1995PTC090558), with an upfront Key Fact Statement (KFS) showing exact monthly interest (2% to 3% per month), processing fees (0% to 7.5% plus applicable GST), and APR.
-
Options for Every Income Profile: Whether you earn a fixed monthly paycheck and want to explore our personal loan for salaried applicants, manage variable client invoices with our personal loan for self employed option, or receive stipends and allowances under our personal loan for non salaried category, we evaluate digital cash flows through paperless KYC.
-
Plan Before You Borrow: Estimate your exact monthly instalment using our personal loan EMI calculator and check your debt-to-income comfort level with our FOIR calculator before accepting any offer.
What Should You Check Before Linking Bank Accounts to UPI Apps?
Before installing any application from the top 10 upi app in india list, verify these essential safety and usability checkpoints:
-
Official App Store Listing: Download UPI apps exclusively from the Google Play Store or Apple App Store and verify the developer name (such as NPCI, Google LLC, or PhonePe Pvt. Ltd.).
-
Server Uptime & Bank Compatibility: Check how smoothly the app handles peak evening hours when major bank servers experience high traffic.
-
UPI Lite & RuPay Credit Support: Ensure the app supports on-device UPI Lite for PIN-less micro-payments and RuPay credit card linking if you use one.
-
In-App Dispute Resolution: Confirm that the app provides a built-in "Raise a Complaint" button compliant with NPCI's UDIR (Unified Dispute and Issue Resolution) framework for failed or pending transactions.
Common Mistakes to Avoid When Using UPI Apps in India
-
Entering Your UPI PIN to "Receive" Money: You never need to enter your UPI PIN to receive funds; a PIN is required solely to authorize an outgoing debit.
-
Scanning Unverified Payment Links or QR Codes: Fraudsters frequently send "collect requests" disguised as refunds or prize claims. Always read the transaction direction ("Paying" vs. "Receiving") before authenticating.
-
Retrying Immediately During a "Pending" Status: If a payment shows "Pending" due to bank server congestion, wait before initiating a duplicate transfer. Under RBI guidelines, failed auto-debits must reverse automatically within T+1 working days.
-
Overlooking Micro-Spend Accumulation: Small ₹50–₹200 QR scans add up quickly. Track monthly spending using our 50 30 20 rule calculator and read our guide on lifestyle inflation and savings to keep your savings intact.
Final Takeaway: Pick the Right UPI App & Borrow Smartly
Choosing the best upi app in india comes down to matching your daily payment routine whether that means PhonePe or Google Pay for universal merchant reach, BHIM for clean government-backed simplicity, or CRED and super.money for RuPay rewards. And whenever an unexpected expense outpaces your bank balance before payday, rely on regulated, transparent digital credit rather than unverified apps.
Also Read: Latest Guides & News on Pocketly
Frequently Asked Questions (FAQs)
1. Which is the best UPI app in India for 2026–2027?
PhonePe and Google Pay are widely considered the best upi app in india for overall merchant acceptance and server reliability, while BHIM is ideal for an ad-free interface and CRED or super.money suit RuPay credit card rewards.
2. Which is the most used UPI app in India right now?
According to NPCI transaction data, PhonePe is the most used upi app in india, processing over 45% of all third-party UPI transactions, followed by Google Pay (~32%) and Paytm (~8%).
3. Which was the first UPI app in India?
BHIM (Bharat Interface for Money), developed by NPCI and launched on December 30, 2016, was the first upi app in india built for nationwide consumer adoption after NPCI piloted UPI across member banks in April 2016.
4. Are all UPI apps in India free to use for bank-to-bank transfers?
Yes, peer-to-peer (P2P) bank transfers and standard merchant QR payments on upi apps in india carry zero transaction fees for consumers, though certain wallet-based PPI merchant transactions above ₹2,000 may involve interchange charges borne by merchants.
5. Can I link my RuPay credit card to the top 10 UPI app in India platforms?
Yes, all leading platforms in the top 10 upi app in india including PhonePe, Google Pay, Paytm, BHIM, CRED, and super.money allow you to link eligible RuPay credit cards to scan and pay merchant QR codes.
6. What should I do if a UPI payment fails or gets stuck in pending status?
Do not immediately repeat the payment; wait for your bank's server to update the status, and raise an in-app dispute ticket if the debited amount is not auto-reversed within T+1 working days under RBI guidelines.
7. Can I get an instant personal loan online in 2 minutes if my bank balance runs low before payday?
While our digital onboarding and Video KYC on Pocketly take just a few minutes often searched as an instant personal loan online in 2 minutes final approval and bank disbursal depend on automated KYC validation and underwriting by our RBI-registered NBFC partner, Speel Finance Company Private Limited.
8. How should I choose the best loan app in India alongside my UPI app?
If you are comparing platforms to find the best loan app in India, check the RBI-registered NBFC partner, Key Fact Statement (KFS), all-inclusive APR, processing fees, and repayment tenure and estimate your monthly instalment beforehand using our personal loan EMI calculator.
9. Can salaried, self-employed, and non-salaried users apply for a personal loan with Pocketly?
Yes. At Pocketly, you can explore our personal loan for salaried, personal loan for self employed, or personal loan for non salaried options for credit lines between ₹1,000 and ₹50,000, subject to verification and underwriting criteria.