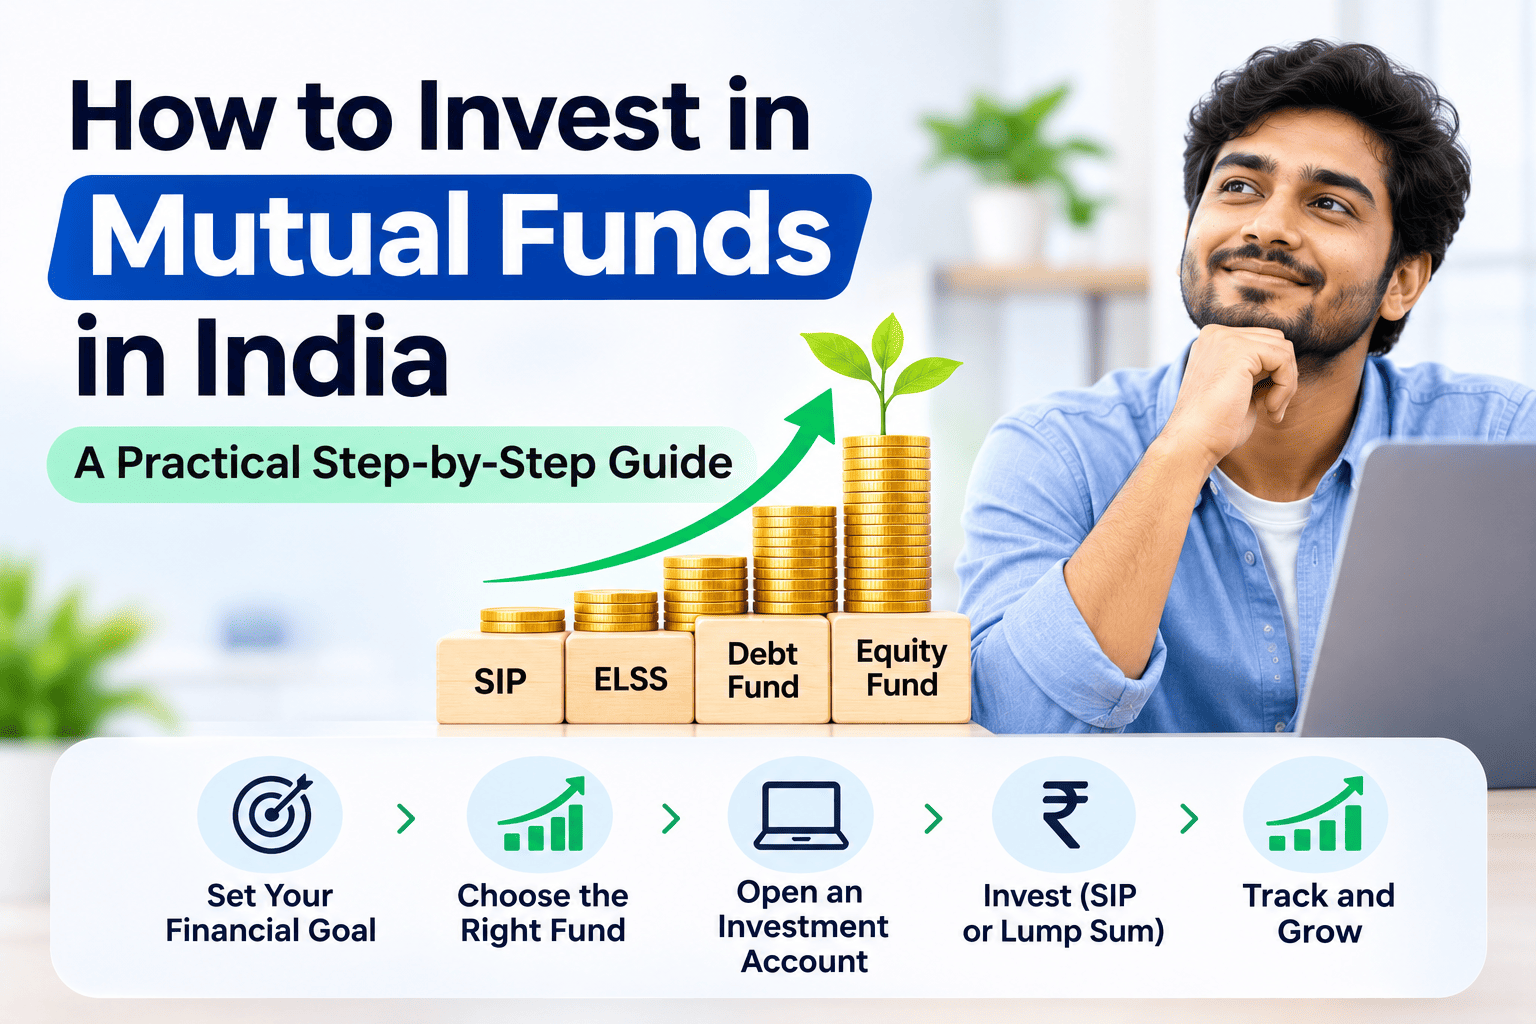


To understand how to invest in mutual funds in India, you must complete a one-time SEBI-compliant KYC verification using your PAN and Aadhaar, link an active savings bank account, select a scheme aligned with your risk tolerance, and invest via a Systematic Investment Plan (SIP) or lumpsum starting from ₹100 to ₹500. Because mutual fund returns are market-linked and never guaranteed, matching your investment horizon with the right asset class is essential before committing your savings. At Pocketly, we help young Indians balance long-term wealth building with day-to-day liquidity—so while your mutual funds compound over time, our digital credit line helps you handle sudden expenses without breaking your investments.
Quick Answer: How to Start Investing in Mutual Funds?
|
Step |
Action Required |
Key Indian Requirement |
Minimum Entry |
|
1. Define Horizon & Risk |
Match goal duration (1 to 15+ years) with risk appetite |
Separate short-term cash from long-term goals |
₹0 (Planning) |
|
2. Complete Digital KYC |
Verify identity via SEBI KRA or AMC portal |
PAN card, Aadhaar (mobile-linked), bank proof |
Free e-KYC |
|
3. Choose Plan & Mode |
Select Direct Plan (zero broker commission) & SIP/Lumpsum |
Direct plans remove distributor fees |
₹100 – ₹500 (SIP) |
|
4. Model Your Returns |
Project corpus growth and withdrawal plans |
Test assumptions before locking funds |
Free online tools |
|
5. Automate & Review |
Set up UPI AutoPay / e-Mandate and review annually |
Maintain an emergency liquidity buffer |
Recurring or Lumpsum |
What Is a Mutual Fund and How Does It Fit Into Your Portfolio?
A mutual fund pools money from retail and institutional investors to buy a diversified basket of equities, debt instruments, or hybrid assets, managed professionally by an Asset Management Company (AMC) regulated by the Securities and Exchange Board of India (SEBI). Instead of picking individual stocks daily, you own mutual fund units whose value moves with the scheme's daily Net Asset Value (NAV).
Among the different types of investments available in India—such as direct stocks, bank Fixed Deposits (FDs), Public Provident Fund (PPF), National Pension System (NPS), and digital gold—mutual funds stand out for combining professional management, portfolio diversification, and flexible ticket sizes. Before committing your monthly surplus into market-linked funds, map out your household budget using our 50 30 20 Rule Calculator and check your debt obligations with our FOIR Calculator so your essential living expenses remain untouched.
How to Invest in Mutual Funds in India: 6-Step Process
If you are a student, first-jobber, or freelancer learning how to invest in mutual funds in India, follow these six practical steps:
-
Separate Emergency Cash from Investable Surplus: Keep 3 to 6 months of living expenses in liquid savings before locking money into market assets.
-
Complete Your One-Time SEBI KYC: Under SEBI rules, Know Your Customer (KYC) verification is mandatory across all mutual fund houses. Use your PAN card and mobile-linked Aadhaar to complete digital e-KYC through a SEBI-registered KYC Registration Agency (KRA) or AMC platform.
-
Pick Direct Plans Over Regular Plans: Always look for the word "Direct" in the scheme name when investing independently. Direct plans eliminate intermediary distributor commissions, adding 0.5% to 1.2% in extra annualized compounding returns over long holding periods.
-
Select the Right Mutual Funds to Invest In: Match your time horizon with the appropriate category—such as broad-market Nifty 50 Index Funds for beginners, Flexi-Cap Funds for multi-year growth, or Liquid Debt Funds for short-term parking.
-
Project Your Corpus with Planning Tools: Before setting up bank mandates, forecast your wealth accumulation using our Mutual Fund Returns Calculator. If you are deploying an annual bonus or windfall, test single-deposit compounding on our Lumpsum Calculator.
-
Automate Contributions or Withdrawals: Set up a monthly SIP via UPI AutoPay for wealth accumulation, or plan structured retirement payouts later in life using our SWP Calculator.
Also Read: Comparison of Top Loan Apps in India: Interest Rates, Fees, Tenure & Customer Care Directory
Comparing Mutual Funds to Invest In: SIP, Lumpsum & SWP Strategies
Choosing the right mutual funds to invest in also requires choosing how money enters and exits your portfolio. Whether you are building wealth from a monthly paycheck, investing a one-time surplus, or generating regular cash flow, each method serves a distinct purpose:
|
Strategy / Fund Approach |
How It Works |
Ideal Investor Profile |
Pocketly Planning Tool |
|
Systematic Investment Plan (SIP) |
Invests a fixed amount monthly (₹100–₹500+) to average out market volatility |
Students, first-jobbers, salaried earners, freelancers |
|
|
One-Time Lumpsum Investment |
Deploys a single upfront capital amount to compound from Day 1 |
Earners with annual bonuses, tax refunds, or business surplus |
|
|
Systematic Withdrawal Plan (SWP) |
Redeems a fixed amount periodically from an existing corpus while the rest stays invested |
Retirees or investors seeking predictable monthly cash flow |
|
|
ELSS (Tax-Saving Funds) |
Equity-oriented funds with a mandatory 3-year lock-in period |
Taxpayers claiming Old Regime Section 80C deductions |
Note: Mutual fund returns typically range between 10% and 14% over long horizons depending on asset allocation, though returns are market-linked and never guaranteed.
How Different Earners Should Approach a Mutual Funds Investment
Your income stability determines how you should balance growth assets with liquid reserves when planning a mutual funds investment:
-
Students & First-Jobbers: Start small with ₹500 monthly SIPs in diversified Nifty 50 Index Funds to build savings discipline early without tying up semester or rent money.
-
Salaried Professionals: Allocate 60% toward equity mutual funds for long-term goals and 25%–40% toward stability instruments like PPF or bank FDs. You can also model annual contribution hikes using our Step Up SIP Calculator.
-
Self-Employed & Freelancers: Because business revenue and client payouts fluctuate, keep 50% of your surplus in flexible liquid debt funds or FDs and 40% in equity SIPs so irregular cash cycles never force you to stop investing.
Protecting Your Mutual Fund Compounding During Emergencies
One of the biggest wealth-destroying mistakes young investors make is redeeming equity mutual funds prematurely whenever an unexpected expense strikes—such as a medical bill, urgent laptop repair, or delayed freelance invoice. Liquidating units early halts compounding, triggers exit loads (often 1% within 12 months), and incurs Short-Term Capital Gains (STCG) tax at 20% on equity schemes (while Long-Term Capital Gains above ₹1.25 lakh after 12 months are taxed at 12.5%).
At Pocketly, we offer a transparent, 100% digital liquidity buffer so you can handle short-term cash shortfalls without disturbing your long-term investments:
-
For Salaried Earners: Bridge unexpected month-end expenses before payday with our personal loan for salaried applicants.
-
For Self-Employed Professionals: Manage temporary working capital gaps during delayed client billing cycles through our personal loan for self employed tier.
-
For Students & Gig Workers: If you earn through stipends or freelancing without conventional payslips, explore our loan for non salaried options.
With Pocketly, eligible borrowers can access digital personal credit lines from ₹1,000 up to ₹50,000 for tenures of 61 days to 9 months, with interest rates between 2% and 3% per month (published APR ranges from 30% to 121%). All loans on our platform are disbursed exclusively through our RBI-registered NBFC partner, Speel Finance Company Private Limited, under our responsible lending standards. Before taking any short-term credit, always evaluate your monthly repayment comfort using our Personal Loan EMI Calculator.
Common Mistakes to Avoid When Investing in Mutual Funds
Even after learning how to invest in mutual funds in India, avoiding these five pitfalls protects your final corpus:
-
Stopping SIPs During Market Dips: Market downturns let your SIP buy more units at lower NAVs. Pausing contributions during corrections reduces long-term recovery gains.
-
Waiting Forever to Deploy a Lumpsum: Sitting on idle cash waiting for the "perfect market bottom" often costs more than investing early. Compare staggered vs. upfront entry using our Lumpsum Calculator.
-
Borrowing Money to Invest in Equity Markets: Never take a personal loan or use credit card leverage to invest in mutual funds. Market returns are uncertain, whereas loan EMIs are fixed obligations.
-
Ignoring Expense Ratios and Exit Loads: High fund-management charges quietly erode compound gains over 10 to 15 years. Always check the Scheme Information Document (SID) before investing.
-
Letting Lifestyle Creep Shrink Your Surplus: As your paycheck grows, increase your SIP amount rather than your discretionary spending. Read our guide on lifestyle inflation and savings and strengthen your defenses with financial risk management.
Also Read: Top 10 Instant Loan App in India ( 2026): Fast Cash up to ₹50,000 Without CIBIL Hassles
Final Takeaway: Start Early, Stay Consistent, and Protect Your Cash Flow
Learning how to invest in mutual funds gives you a structured, inflation-beating path to long-term financial independence. Complete your digital KYC, choose Direct Plans suited to your timeline, and test your projections across our Mutual Fund Returns Calculator, Lumpsum Calculator, and SWP Calculator before committing your funds.
When unexpected personal bills arise, protect your compounding investments from early redemption and explore transparent liquidity options designed around your budget:
-
Check Your Eligibility With Pocketly: Explore Our Personal Loan Options
-
Plan Your Repayment Before Borrowing: Use Our Personal Loan EMI Calculator
Frequently Asked Questions (FAQs)
1. How can a beginner learn how to invest in mutual funds in India?
You can start by completing your one-time SEBI KYC online using your PAN and Aadhaar, linking an active bank account, and starting a monthly SIP of ₹500 in a Direct Nifty 50 Index Fund. Use our Mutual Fund Returns Calculator first to align your monthly contribution with a 5- to 10-year goal.
2. What is the minimum amount required for a mutual funds investment?
Most Indian mutual fund houses allow you to start a monthly Systematic Investment Plan (SIP) with as little as ₹100 to ₹500, while one-time lumpsum investments typically start between ₹1,000 and ₹5,000 depending on the scheme.
3. Should I invest via SIP or use a Lumpsum Calculator for a one-time deposit?
Choose a monthly SIP if you earn a regular salary or freelance income and want rupee cost averaging. If you have a one-time bonus or idle savings, model your potential maturity corpus on our Lumpsum Calculator to see how Day-1 compounding works over 7 to 15 years.
4. How does a Systematic Withdrawal Plan (SWP) work in mutual funds?
An SWP lets you withdraw a fixed amount every month or quarter from your existing mutual fund corpus while the remaining balance stays invested to earn market returns. You can plan sustainable withdrawal rates using our SWP Calculator.
5. Which are the best mutual funds to invest in for beginners?
For beginners exploring how to invest in mutual funds, low-cost Direct Nifty 50 Index Funds, Flexi-Cap Equity Funds, and Hybrid Balanced Advantage Funds are popular starting points because they provide broad diversification across top Indian companies.
6. How are mutual fund gains taxed in India?
For equity mutual funds held for more than 12 months, Long-Term Capital Gains (LTCG) exceeding ₹1.25 lakh per financial year are taxed at 12.5%, while Short-Term Capital Gains (STCG) under 12 months are taxed at 20%. Gains from debt mutual funds are taxed at your applicable income tax slab rate.
7. Can I get an instant personal loan online in 2 minutes instead of selling my mutual funds during an emergency?
An instant personal loan online in 2 minutes reflects an automated digital application journey, though final approval and disbursal depend on KYC verification and underwriting checks by our RBI-registered NBFC partner, Speel Finance Company Private Limited. Using a manageable short-term loan up to ₹50,000 for genuine emergencies can help you avoid redeeming long-term mutual funds prematurely.
8. How do I evaluate the best loan app in India if I need short-term emergency liquidity?
When comparing options to find the best loan app in India for urgent cash needs, check that the platform partners with an RBI-registered NBFC, provides an upfront Key Fact Statement (KFS), discloses total APR and processing fees clearly, and follows RBI digital lending guidelines.