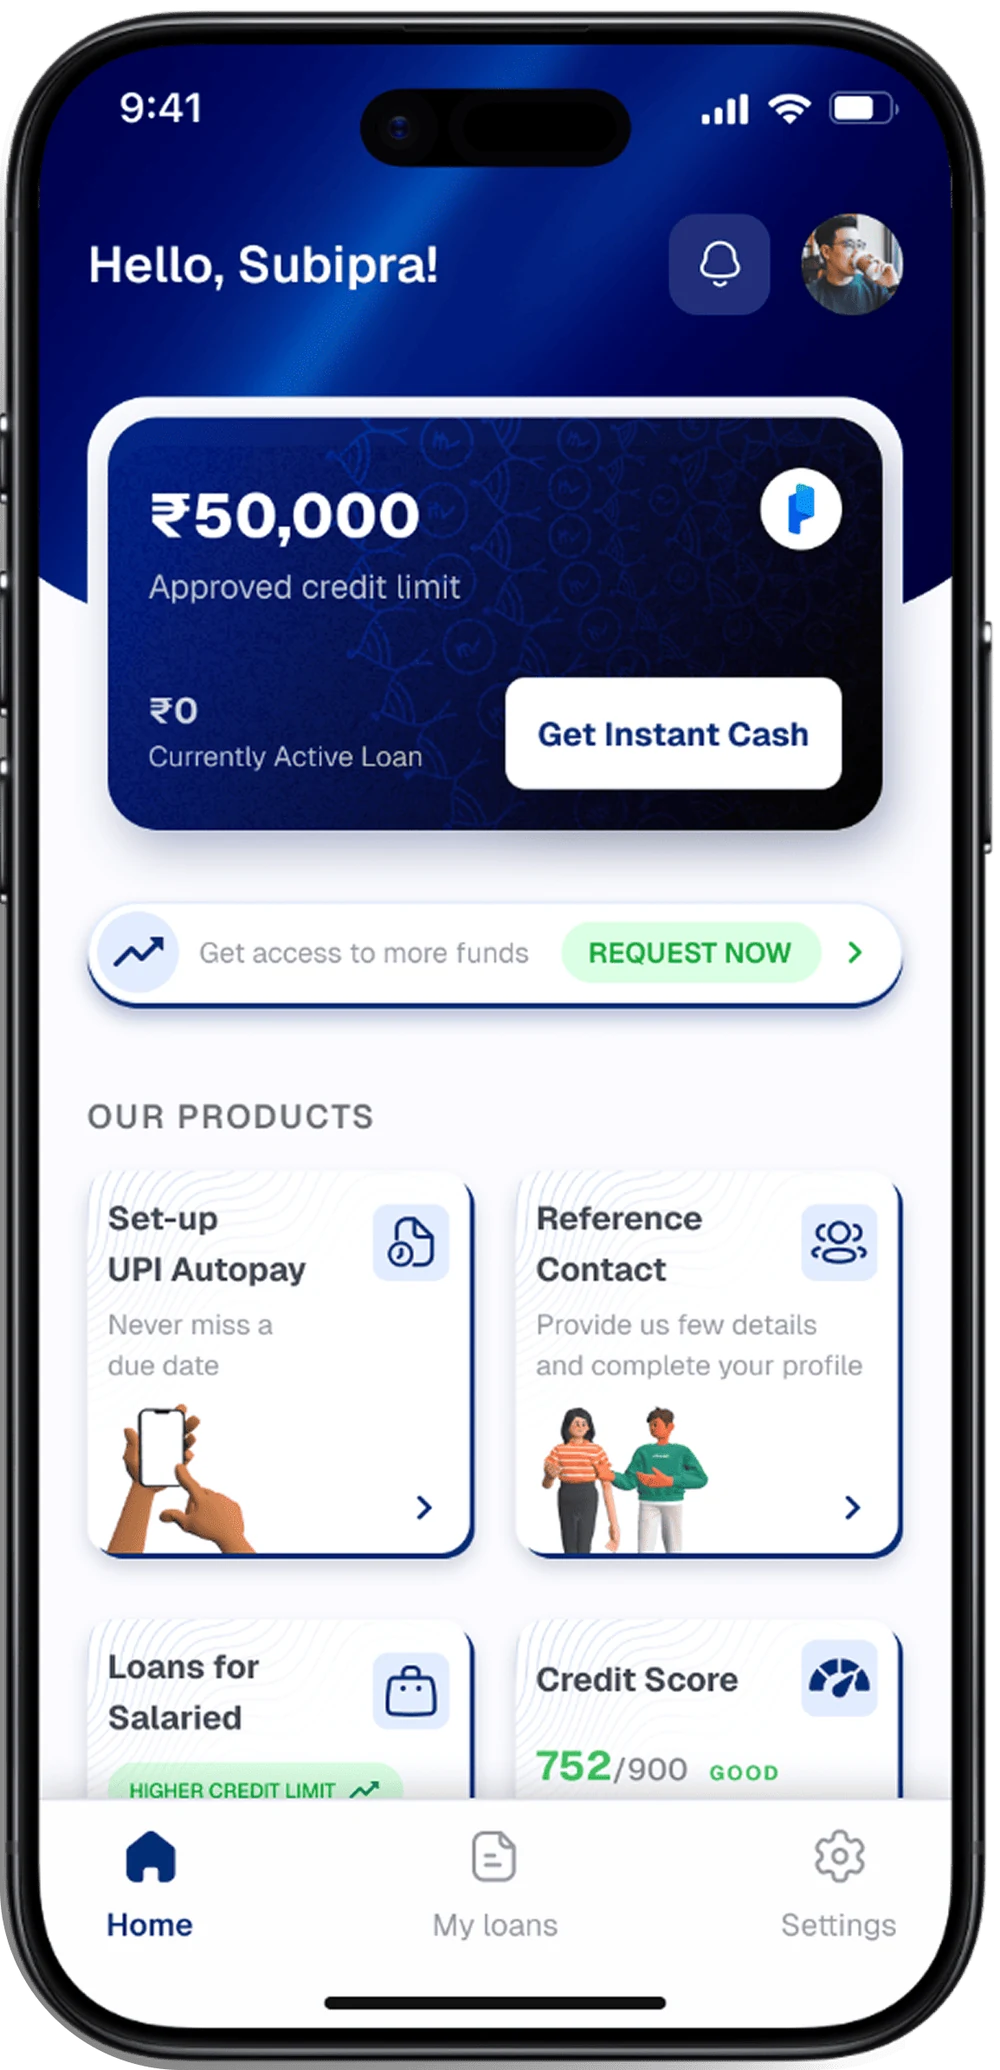
Finding a reliable 500 cibil score loan app in India is challenging because traditional banks treat a 500 bureau rating as high risk, while the Reserve Bank of India (RBI) sets no statutory minimum credit score for loans. Instead of relying solely on legacy bureau cutoffs, regulated digital lending platforms evaluate current banking cash flows, digital KYC, and Fixed Obligation to Income Ratio (FOIR). At Pocketly, you do not need a high prior CIBIL score to apply for unsecured credit from ₹1,000 to ₹50,000 through our RBI-registered NBFC partner, Speel Finance Company Private Limited, subject to verification and underwriting.
Quick Answer: At a Glance
|
Parameter |
What Borrowers with a 500 CIBIL Score Should Know |
|
Is a 500 Score Approved? |
Traditional banks usually reject scores below 650; regulated digital apps assess cash-flow continuity alongside bureau records. |
|
Pocketly Loan Limit |
₹1,000 to ₹50,000 (subject to digital KYC and underwriting approval). |
|
Repayment Tenure |
61 days to 9 months via structured Equated Monthly Instalments (EMIs). |
|
Interest & Fee Range |
2% to 3% per month; processing fee 0% to 9.4% (inclusive of 18% GST); APR up to 99.73%. |
|
RBI 2026 Bureau Rule |
Since July 2026, lenders report repayment data weekly (four times a month), helping timely EMIs reflect faster on your report. |
|
Regulated Lending Partner |
Speel Finance Company Private Limited (RBI-registered NBFC, CIN: U65920MH1995PTC090558). |
What Does a 500 CIBIL Score Mean for Loan Approval in India?
A CIBIL score ranges from 300 to 900, and a score around 500 falls into the poor credit tier—typically caused by past late EMI payments, high credit card utilization, or an older loan settlement. When you look for a personal loan for cibil score of 500, understanding how lenders view your profile saves you from repeated rejections that trigger damaging hard inquiries.
Conventional commercial banks rely on automated score filters and rarely sanction unsecured credit below 700–750. By contrast, modern digital lenders look beyond historical blemishes. While a 500 cibil score loan app cannot promise guaranteed approval—because RBI Digital Lending Directions require mandatory KYC and repayment-capacity checks—regulated NBFC platforms evaluate whether your current monthly income can comfortably support a small-ticket EMI.
How a 500 CIBIL Score Loan App Evaluates Your Application
When you apply on a compliant 500 cibil loan app like Pocketly, underwriting moves away from rigid branch paperwork toward real-time digital verification:
-
Paperless KYC Verification: You submit your PAN card details, complete Aadhaar-based digital address authentication, and record a brief live Video KYC inside the app.
-
Cash-Flow & Debt-Ratio Check: Our underwriting system assesses your regular monthly bank inflows and existing obligations. You can check your safe debt ceiling beforehand using our FOIR calculator and test borrowing limits on our personal loan eligibility calculator.
-
Key Fact Statement (KFS) Disclosure: Before you digitally sign any contract, RBI rules require our regulated lending partner to display a standardized KFS listing the exact Annual Percentage Rate (APR), processing fee, 18% GST, and repayment dates.
-
Direct Bank Disbursal: Once accepted, approved funds transfer directly from Speel Finance Company Private Limited into your verified savings bank account via IMPS or NEFT.
Pocketly Borrower Options for Different Income Profiles
Whether you need a loan app for 500 cibil score emergencies or a starter credit line to rebuild your track record, we tailor options around how you earn:
-
Salaried Employees: Facing an urgent medical bill or utility shortfall before payday? Explore our personal loan for salaried applicants to bridge short-term gaps without pledging collateral.
-
Self-Employed & Freelancers: If delayed client invoices temporarily bruised your bureau score, maintain steady cash flow through our personal loan for self employed tier.
-
Students & Non-Salaried Earners: Young adults aged 18 to 40 with regular monthly allowances or gig payouts can apply via our personal loan for non salaried option without corporate payslips.
Costs, Interest Rates, and Illustrative Repayment Example
Before accepting an offer from any 500 credit score loan app, inspect the all-in cost so your upcoming EMIs stay manageable. Under our responsible lending policy, Pocketly charges 2% to 3% monthly interest, a 0% to 9.4% processing fee (inclusive of 18% GST), and caps APR at 99.73% on core micro-products (30%–121% across specialized structures), with a 2.5% foreclosure fee on remaining principal if paid early.
|
Cost Component |
Illustrative ₹5,000 Loan (90 Days Tenure) |
|
Sanctioned Principal Amount |
₹5,000.00 |
|
Interest Rate |
3% per month (36% p.a.) |
|
Processing Fee (incl. 18% GST) |
₹425.00 |
|
Net Amount Disbursed to Bank |
₹4,575.00 |
|
Estimated Monthly EMI |
Approx. ₹1,767.65 per month (for 3 months) |
|
Total Repayment Amount |
₹5,302.96 (Representative APR: 93.15% p.a.) |
Note: Figures above are strictly illustrative. Actual sanctioned limits, rates, and fees depend on individual underwriting and appear in your Key Fact Statement. Test custom amounts and tenures anytime using our personal loan EMI calculator and structure your monthly budget with our 50 30 20 rule calculator.
Step-by-Step: How to Increase CIBIL Score from 500 to 750
Learning how to increase cibil score from 500 to 750 requires consistent repayment discipline rather than overnight shortcuts. Following the RBI's July 2026 credit reporting update, lenders now submit borrower data to all four credit bureaus on four fixed dates each month (the 9th, 16th, 23rd, and month-end), meaning positive repayment habits reflect on your profile faster than before:
-
Clear Overdue Balances & Update "Settled" Accounts: Pay off any active overdue amounts first. If an old loan shows as "Settled" rather than "Closed," repay the remaining balance with the lender and obtain a No Objection Certificate (NOC) so the bureau status updates cleanly.
-
Audit Your Credit Report for Errors: Download your free annual report from CIBIL, Experian, Equifax, or CRIF High Mark and dispute any wrongly tagged defaults—bureaus and lenders must resolve verified disputes within 30 days under RBI rules.
-
Keep Credit Card Utilization Under 30%: If you hold an active credit card with a ₹50,000 limit, keep monthly spending below ₹15,000 to show low credit dependency.
-
Build Fresh Payment History with Small Credit: Because Speel Finance Company Private Limited reports repayment histories to Indian credit bureaus, taking a small, affordable loan on Pocketly and paying every EMI on time adds positive payment data every month.
-
Space Out New Applications: Avoid applying across multiple apps simultaneously, as clustered hard inquiries pull a 500 score down further.
Safety Checklist & Mistakes to Avoid When Borrowing with a 500 Score
-
Avoid Predatory 7-Day Loan APKs: Never click WhatsApp links promising "guaranteed approval" without KYC. Unlicensed apps deduct up to 40% upfront and demand repayment within a week. Read our comparison on 7 days loan vs 30 days loan and check our list of loan apps banned in India to stay safe.
-
Verify the RBI-Registered NBFC: Always confirm that the app names its regulated lending partner (Speel Finance Company Private Limited for Pocketly) and never scrapes your phone contacts.
-
Protect Your Due Dates: Missing an EMI triggers late fees and hurts recovery progress. If cash-flow stress ever threatens an upcoming payment, review loan ki kissht nahi bhar pa rahe and understand EMI bounce charges before your due date.
Take the Next Step Toward Credit Recovery with Pocketly
A 500 CIBIL score is a temporary snapshot of past challenges, not a permanent roadblock. By borrowing only what fits comfortably within your monthly budget, inspecting your Key Fact Statement upfront, and clearing every EMI on time, you can handle urgent expenses today while steadily rebuilding your credit profile toward 750.
Frequently Asked Questions (FAQs)
Can I get a personal loan from a 500 CIBIL score loan app in India?
Yes, you can apply through a regulated 500 cibil score loan app like Pocketly. While traditional banks generally reject scores around 500, our RBI-registered NBFC partner evaluates your current monthly cash flow, digital KYC, and repayment capacity rather than relying solely on past bureau scores.
How much personal loan for CIBIL score of 500 can I get on Pocketly?
On Pocketly, eligible borrowers can apply for a personal loan for cibil score of 500 ranging from ₹1,000 to ₹50,000 with repayment tenures between 61 days and 9 months, subject to digital KYC verification and automated underwriting checks.
How long does it take to increase CIBIL score from 500 to 750?
Understanding how to increase cibil score from 500 to 750 comes down to consistency: with zero missed EMIs, credit card utilization under 30%, and no clustered hard inquiries, rebuilding typically takes 6 to 12 months—though RBI's 2026 weekly reporting cycle allows timely payments to reflect faster.
What documents are required on a 500 CIBIL loan app?
Applying on Pocketly's 500 cibil loan app is 100% paperless. You only need your valid PAN card details, Aadhaar-based digital address authentication, an active Indian savings bank account, and a smartphone camera for a brief live Video KYC.
Does repaying a loan on a loan app for 500 CIBIL score improve my credit report?
Yes. Because our regulated lending partner, Speel Finance Company Private Limited, reports repayment track records to Indian credit bureaus, paying every EMI on time through our loan app for 500 cibil score builds positive payment history that gradually lifts your score.
Is a 500 credit score loan app safe to use?
A 500 credit score loan app is safe when it partners with an RBI-registered NBFC or bank, provides a standardized Key Fact Statement (KFS) upfront, and follows strict data-privacy norms. Pocketly is ISO 27001: 2023 certified and never accesses your personal contact list.