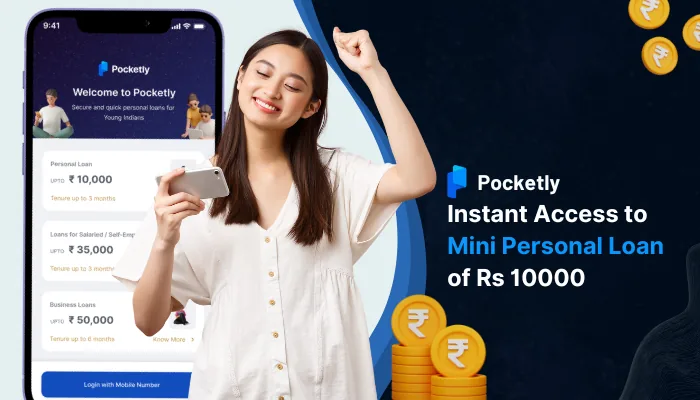


Need ₹10,000 to pay an urgent medical bill, repair your bike or manage an expense before payday? A mini personal loan can help cover a short-term cash requirement when you have a clear repayment plan.
Pocketly offers unsecured personal loans from ₹1,000 to ₹50,000, including ₹10,000, subject to eligibility and verification. You can apply online without visiting a bank branch.
Before borrowing, check the interest rate, processing fee, repayment dates and total amount payable. Even a small loan can become expensive if you miss payments or overlook the charges.
What Is a ₹10,000 Mini Loan?
A ₹10,000 mini loan is a small personal loan generally used for immediate expenses. It does not require property, gold or another asset as collateral when offered as an unsecured loan.
People commonly consider these loans for:
-
Emergency medical or pharmacy expenses
-
Essential vehicle repairs
-
Utility bills before the due date
-
Necessary education expenses
-
Temporary cash shortages before salary
Borrowing ₹10,000 can be manageable for someone with sufficient income, but the repayment obligation remains the same regardless of why the money was borrowed.
Can You Get a ₹10,000 Mini Loan Through Pocketly?
Yes. ₹10,000 falls within Pocketly's personal loan range of ₹1,000 to ₹50,000. The actual amount offered depends on the applicant's eligibility and the lender's assessment.
|
Loan feature |
Pocketly |
|
Available loan range |
₹1,000–₹50,000 |
|
Loan type |
Unsecured personal loan |
|
Application |
Online |
|
Repayment tenure |
61 days to 9 months |
|
Collateral |
Not required |
|
CIBIL score |
Not mandatory to apply |
|
Approval |
Subject to eligibility and verification |
Pocketly works with RBI-registered NBFC lending partner Speel Finance Company Pvt. Ltd.
You can use the personal loan eligibility calculator to make a preliminary assessment before applying. Calculator results do not guarantee approval.
Eligibility and Documents for a ₹10,000 Mini Loan
Pocketly allows eligible Indian applicants aged 18 and above to apply for personal loans. Applicants generally need a source of monthly income and must satisfy the applicable verification requirements.
Information or documents requested during the application may include:
-
PAN details
-
Aadhaar-based identity or address verification
-
Active mobile number and email address
-
Bank account details
-
Income or employment information
-
Video KYC, where applicable
The specific documents depend on the applicant's profile and the lender's verification process.
Can You Apply Without a CIBIL Score?
Pocketly states that a CIBIL score is not mandatory to apply. However, this does not mean every application will be approved.
The lender may still examine the applicant's financial information, existing repayment obligations and ability to repay.
A first-time borrower without an established credit history can apply if they meet the relevant criteria.
How Much Does a ₹10,000 Mini Loan Cost?
The total cost depends on the interest rate, processing fee, repayment period and other applicable charges.
Consider a ₹10,000 loan at an illustrative 24% annual reducing-balance interest rate.
|
Loan details |
6 months |
9 months |
|
Principal |
₹10,000 |
₹10,000 |
|
Illustrative annual interest |
24% |
24% |
|
Monthly EMI |
₹1,785.26 |
₹1,225.15 |
|
Total interest |
₹711.55 |
₹1,026.39 |
|
Total repayment |
₹10,711.55 |
₹11,026.39 |
These are mathematical illustrations, not quoted Pocketly loan offers. Calculations assume equal monthly instalments and exclude processing fees, GST and other charges. Actual repayment schedules and terms may differ.
The example shows a practical trade-off. A longer tenure reduces the monthly instalment but increases the total interest paid.
Use the Pocketly EMI calculator to estimate repayments using the applicable loan amount, rate and tenure.
Check These Charges Before Accepting a Loan
-
Interest rate: Check the rate stated in your loan offer.
-
Processing fee: Find out whether the fee is deducted from disbursal or charged separately.
-
Annual Percentage Rate (APR): Review the disclosed APR to understand the annualised borrowing cost.
-
Late payment charges: Check what happens if an instalment is overdue.
-
Total repayment: Confirm the total amount you must repay.
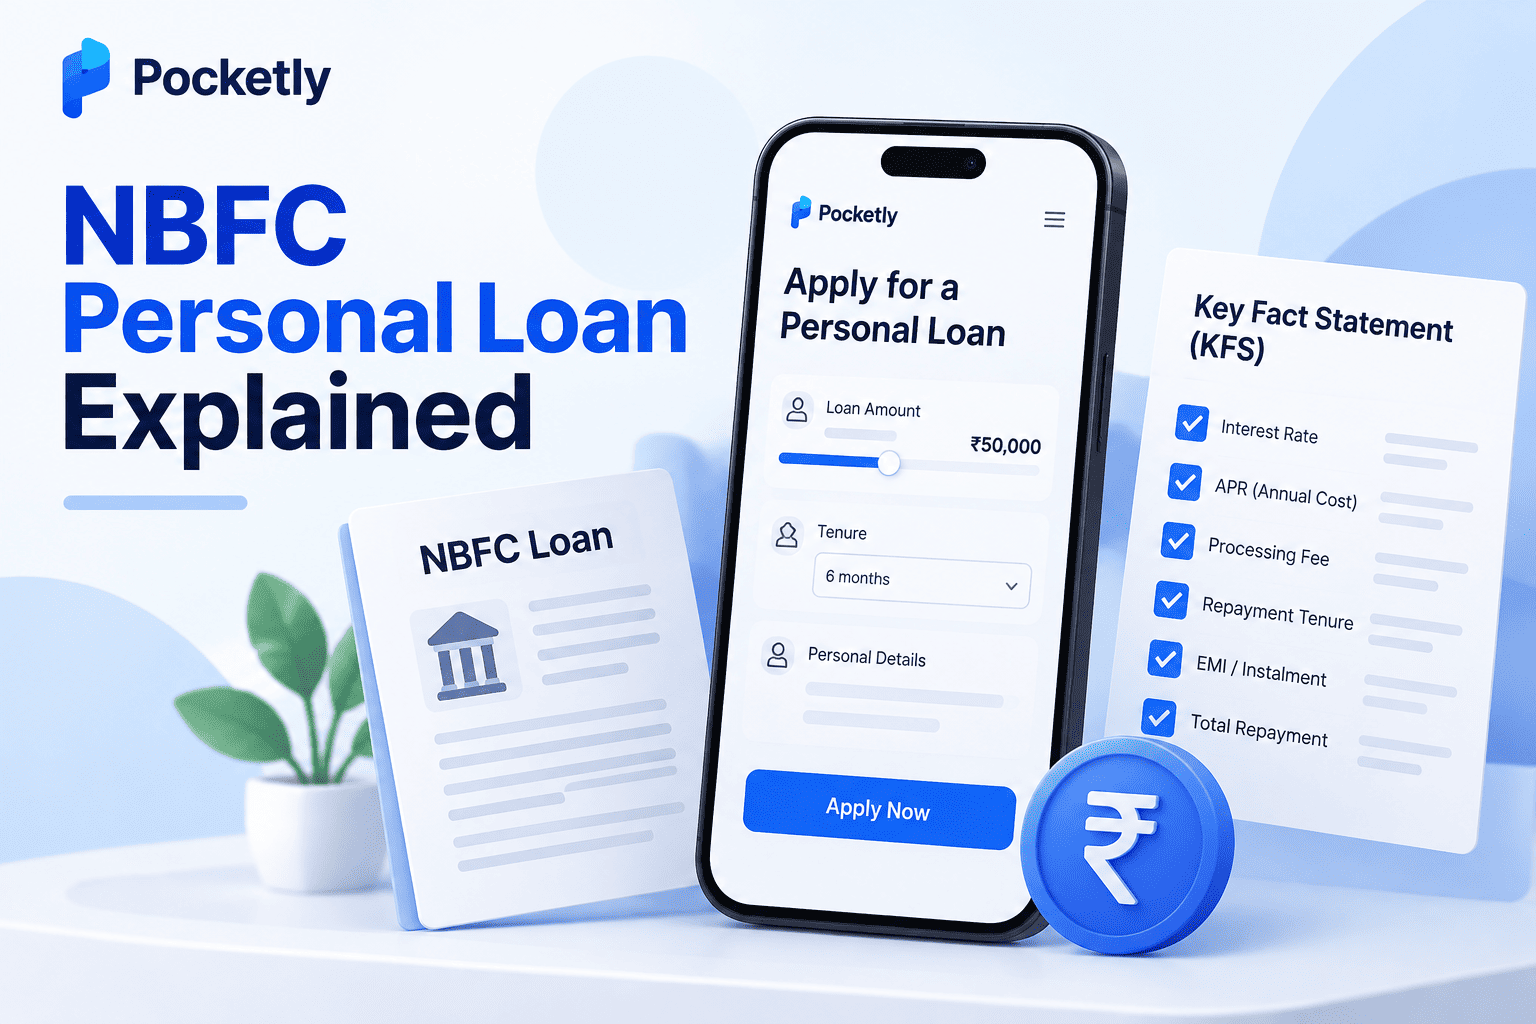
Read the Key Facts Statement (KFS) and loan agreement before accepting the offer. The KFS should disclose the applicable borrowing costs and key conditions.
How to Apply for a ₹10,000 Mini Loan Through Pocketly
You can complete the Pocketly application through your smartphone.
-
Download the Pocketly app: Use its official listing on the Google Play Store.
-
Register your mobile number: Complete the signup and required verification.
-
Provide your details: Enter the personal, employment and income information requested.
-
Complete KYC: Submit the applicable identity and verification details.
-
Check your eligible offer: Review whether ₹10,000 is available to you, along with the applicable repayment period.
-
Review and accept the terms: Check the interest rate, APR, charges, instalment dates and total repayment before proceeding.
If the application is approved and the required steps are completed, the loan amount is disbursed according to the applicable lending process.
A quick digital application does not guarantee approval or a fixed disbursal time.
Is Mini Pocket Loan the Same as Pocketly?
A mini pocket loan generally refers to a small personal loan used for short-term expenses. It is not necessarily the name of a particular lending app.
Pocketly is a digital lending platform offering personal loans from ₹1,000 to ₹50,000 through its lending partner, Speel Finance Company Pvt. Ltd. Loan availability depends on eligibility and verification.
If you are searching for a mini pocket loan app, check the following before applying:
-
Lender details: Verify the bank or RBI-regulated NBFC providing the loan.
-
Loan amount: Check whether the available amount meets your requirements.
-
Interest and charges: Review the APR, processing fees and total repayment amount.
-
Repayment tenure: Choose a repayment period you can reasonably manage.
-
App authenticity: Download the application through its official website or verified app store listing.
You can visit Pocketly's official website to explore its personal loan options, eligibility requirements and application process.
Things to Check Before Taking a Mini Loan
A small loan can still affect your monthly budget.
Suppose your salary is ₹20,000 and you already pay ₹6,000 towards existing EMIs. Adding another EMI of ₹1,785 would increase your monthly loan repayments to approximately ₹7,785.
That leaves ₹12,215 before rent, food, transport and other expenses.
Before applying, consider whether you can manage the additional instalment without missing essential payments.
Also avoid borrowing more than your requirement. If ₹5,000 is sufficient, you can explore the smaller amount rather than automatically borrowing ₹10,000.
For more information about smaller borrowing amounts, read Pocketly's instant mini cash loan guide.
Apply for a ₹10,000 Mini Loan with Pocketly
If you need ₹10,000 for an essential expense and have the income to repay it, you can check your eligibility through Pocketly.
Complete the online application, review the loan offer and make sure the repayment schedule fits your budget.
Apply through the official Pocketly app
Frequently Asked Questions
1. Can I get a ₹10,000 mini loan online?
Yes. Pocketly's stated loan range includes ₹10,000. Whether you receive that amount depends on eligibility, verification and the lender's assessment.
2. Is a CIBIL score compulsory for a ₹10,000 Pocketly loan?
Pocketly states that a CIBIL score is not mandatory to apply. The lender will still assess the application against its eligibility and verification requirements.
3. Can students apply for a ₹10,000 mini loan?
Students who satisfy the applicable eligibility and income requirements may apply. Being a student alone does not guarantee eligibility or approval.
4. Can I get ₹10,000 without a salary slip?
Document requirements depend on the applicant's employment and income profile. Other acceptable income information may be considered, but the lender still needs to assess repayment capacity.
5. How quickly can I receive a ₹10,000 mini loan?
Digital loan applications may be processed quickly. Actual approval and disbursal times depend on verification, lender decisions and processing conditions. No specific time should be assumed as guaranteed.
6. Is Mini Pocket Loan the same as Pocketly?
No. Pocketly is a separate financial platform from mPokket. If you are looking for a particular app, verify its official name, website and developer before downloading it.
7. What is the EMI for a ₹10,000 mini loan?
At an illustrative 24% annual reducing-balance interest rate, the EMI would be approximately ₹1,785.26 for six months or ₹1,225.15 for nine months. These estimates exclude processing fees and other charges. Your actual EMI depends on the loan offer.
8. Can I repay a ₹10,000 mini loan early?
Early repayment depends on the lender's terms. Check the loan agreement for permitted repayment methods, any applicable charges and the effect on total interest.
9. What happens if I miss an EMI?
Late payment may lead to applicable overdue charges and could affect your credit history if the missed payment is reported to credit bureaus. Contact the lender promptly if you expect repayment difficulty.