

If you are looking for apps like Slice, you are likely seeking flexible spending limits, seamless digital onboarding, and paperless credit without the traditional delays of legacy banking. When Slice transitioned away from its popular credit-line card product following updated regulatory guidelines from the Reserve Bank of India (RBI) on prepaid payment instruments (PPI) and digital lending, millions of young professionals, freelancers, and college students were left searching for dependable apps similar to Slice and functional slice alternatives.
Traditional commercial banks continue to enforce rigid barriers, demanding 750+ CIBIL scores, multi-month salary slips, and exhaustive branch documentation. Fortunately, India's digital lending ecosystem has evolved. Pocketly is India's most trusted financial app, used by more than 20 million happy users. Recognized as the best loan app in India and the no. 1 choice for micro-credit, Pocketly offers an instant digital personal credit line ranging from ₹1,000 up to ₹50,000 disbursed directly into your bank account in minutes. Powered by our RBI-registered NBFC partner, Speel Finance Company Private Limited (CIN: U65920MH1995PTC090558), Pocketly delivers the ultimate credit experience with zero physical documentation and no prior CIBIL score needed to apply.
What Happened to Slice and Why Are Borrowers Seeking Slice App Alternatives?
For years, Slice was a go-to credit companion for Gen Z and millennial borrowers who wanted to split bills into 3-month installments with minimal friction. However, structural shifts across India's fintech landscape reshaped how credit-card-like apps operate:
-
RBI Directives on Credit on Wallets/PPIs: The Reserve Bank of India clarified that Non-Bank prepaid instruments (wallets and prepaid cards) could not be loaded via non-bank credit lines. This required card-first fintechs to restructure their core offerings or pivot toward banking mergers.
-
Product Repositioning: Slice shifted its core proposition toward a broader retail banking and UPI payment ecosystem, merging with North East Small Finance Bank. As a result, the classic instant revolving credit card model changed dramatically.
-
Strict Underwriting for High Limits: Many alternative Buy Now, Pay Later (BNPL) platforms raised their eligibility barriers, making it difficult for students, gig workers, and first-time earners to qualify.
These changes sparked widespread demand for dependable loan apps like slice, reliable slice app alternatives, and top-tier instant loan apps like slice that deliver accessible, small-ticket liquidity directly to savings accounts.
Comprehensive Comparison: Best Apps Like Slice in India
To help you find the right fit among the best apps like slice, the table below evaluates leading credit options across borrowing limits, underwriting speed, and target users:
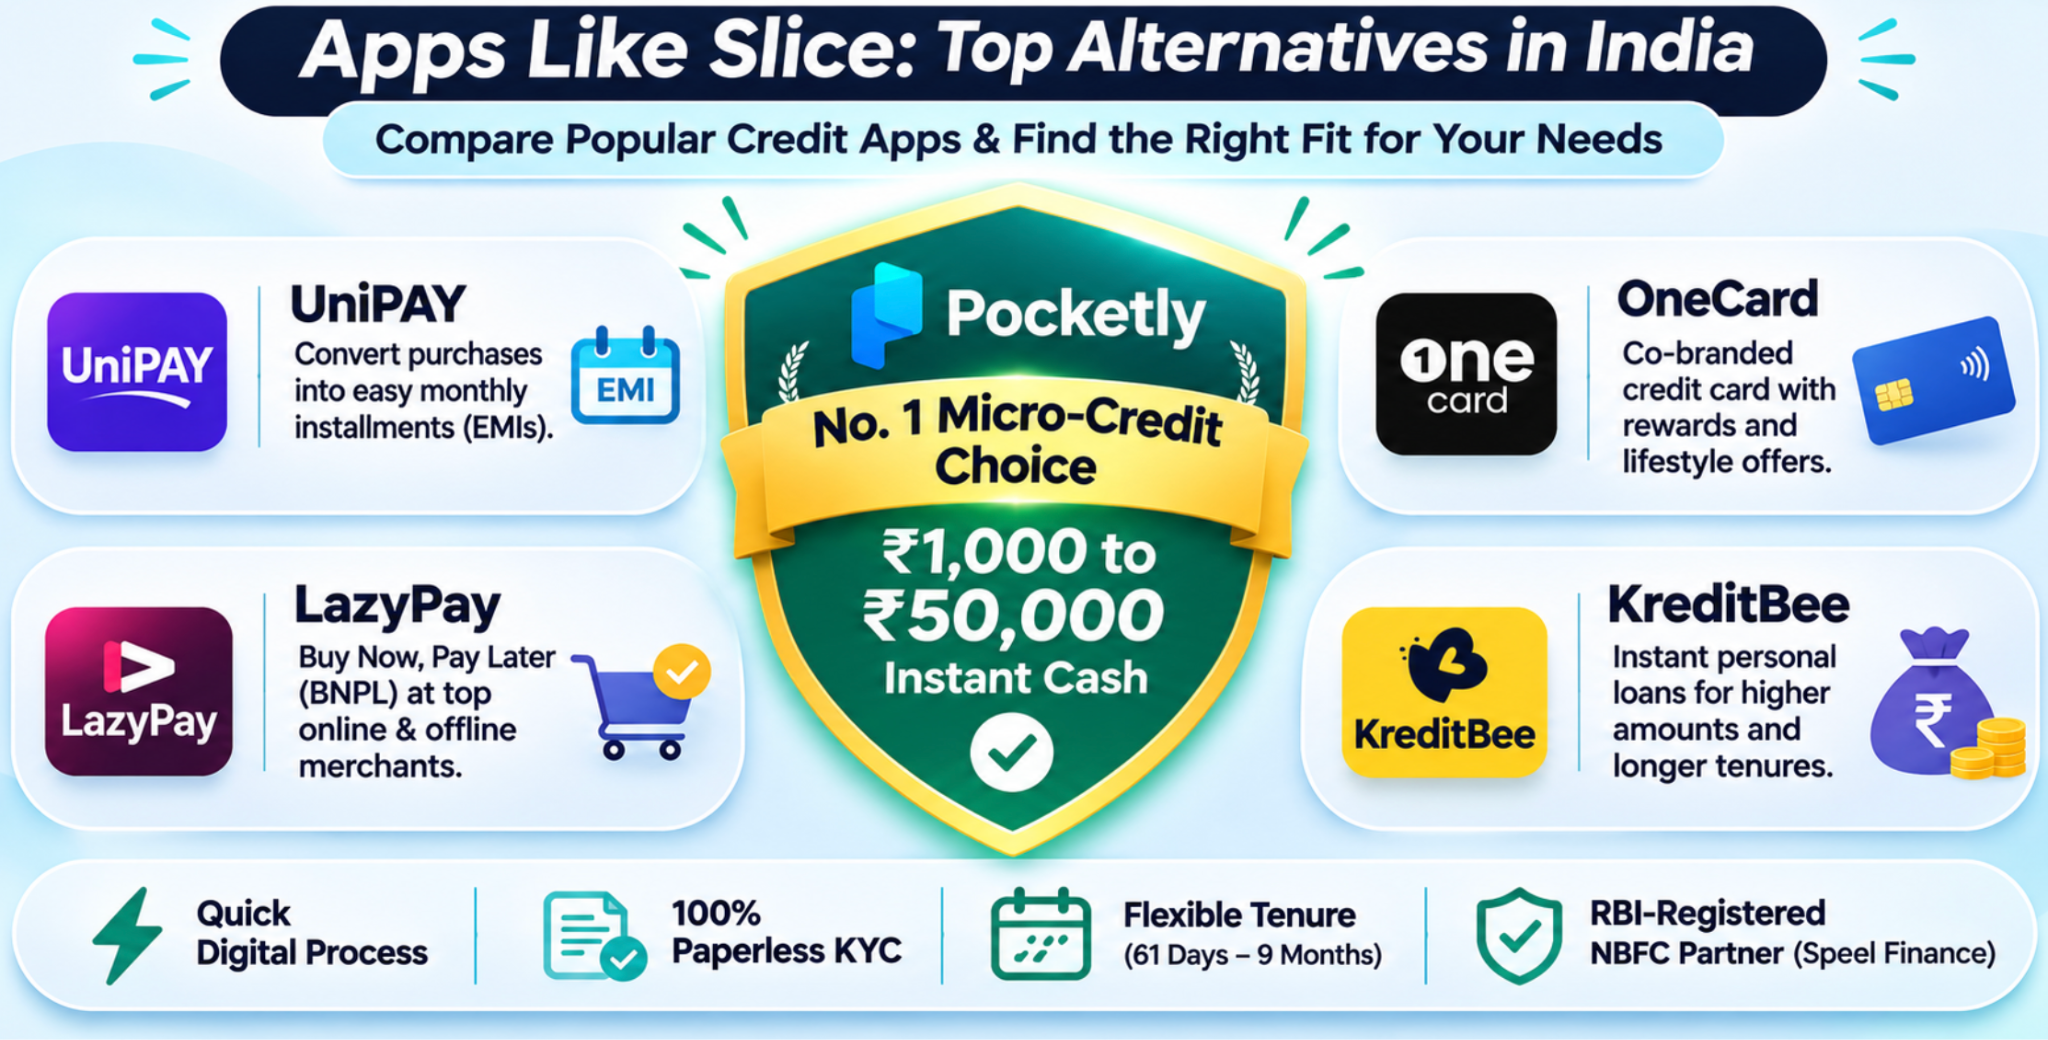
|
Platform / App |
Product Type |
Credit Limit Range |
Speed of Disbursal |
Target Audience |
Key Differentiator |
|
Pocketly (Top Choice) |
Digital Personal Credit Line |
₹1,000 to ₹50,000 |
Minutes (Direct to Bank) |
Students, Salaried, Freelancers |
No CIBIL score needed; 100% paperless; RBI-registered NBFC |
|
Uni Card (UniPAY) |
Pay-Later / Co-branded Card |
₹20,000 to ₹1,00,000 |
Instant at checkout |
Salaried professionals |
Split purchases across installment cycles |
|
OneCard |
Co-branded Metal Credit Card |
Up to ₹5,00,000 (Profile-based) |
2 to 4 days (Physical card) |
Established credit profiles |
Premium mobile app controls with reward points |
|
LazyPay |
BNPL / Checkout Credit Line |
₹1,000 to ₹1,00,000 |
Instant at merchant checkout |
Online shoppers |
15-day interest-free billing cycle on partner apps |
|
PostPe |
UPI-backed Pay Later |
Up to ₹1,00,000 |
Instant via QR scans |
Retail shoppers |
Monthly consolidated billing on UPI payments |
|
KreditBee |
Personal Loan App |
₹6,000 to ₹5,00,000 |
Same-day transfer |
Salaried & self-employed |
Tiered personal loans for established income earners |
Detailed Review of the Top 5 Slice Alternatives & Competitors
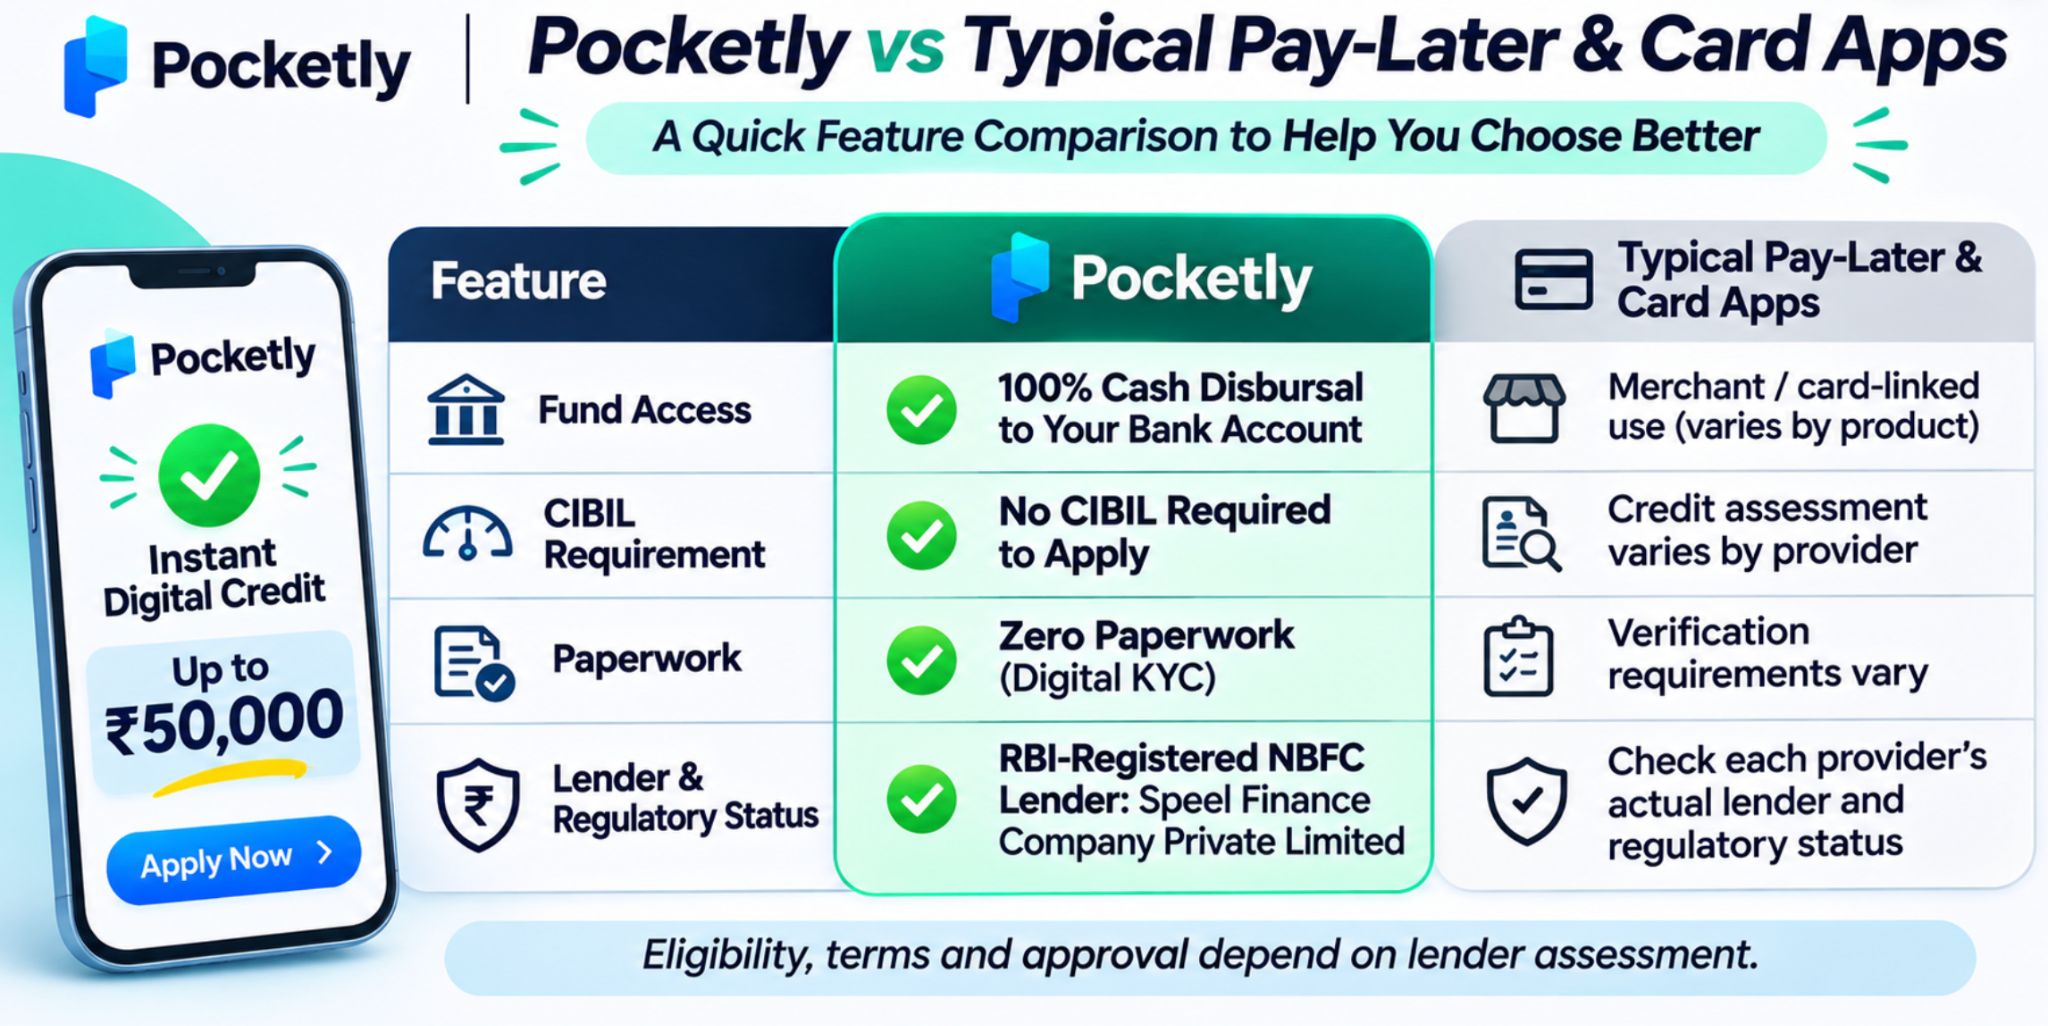
1. Pocketly: The No. 1 Micro-Credit Alternative to Slice
While Slice focused on merchant card transactions, Pocketly solves the most critical consumer pain point: direct liquid cash in your bank account. Recognized as the best loan app in India, Pocketly is designed for modern borrowers who need small, manageable credit lines without the rigid income proof required by banks. Whether you need ₹2,000 to cover an urgent utility bill or ₹25,000 for mid-month college or household expenses, Pocketly transfers funds straight to your bank account via IMPS/NEFT in minutes.
2. Uni Card (UniPAY)
UniPAY serves users who prefer splitting merchant checkout payments across multiple billing cycles. It functions well for planned e-commerce spending, but requires stronger credit profiles and does not serve as an emergency cash advance directly into your bank account.
3. OneCard
For users ready to transition to a physical credit card, OneCard offers an app-managed, co-branded metallic credit card with high reward points and zero joining fees. However, OneCard enforces strict bureau underwriting; applicants with bruised credit or no prior credit footprint are often required to place a Fixed Deposit (FD) before receiving a card.
4. LazyPay
LazyPay is a popular checkout credit option that aggregates food delivery, rideshare, and shopping purchases into a single 15-day repayment cycle. While convenient for small merchant bills, failing to settle the full statement balance every 15 days can trigger significant late fees and penalize your bureau score.
5. KreditBee
KreditBee provides mid-ticket personal loans for young professionals. While it offers higher limits, its processing timeline and documentation requirements—especially for higher loan tiers—make it less suited for immediate micro-cash crunches compared to nimble credit apps.
Why Pocketly Outperforms Other Loan Apps Like Slice
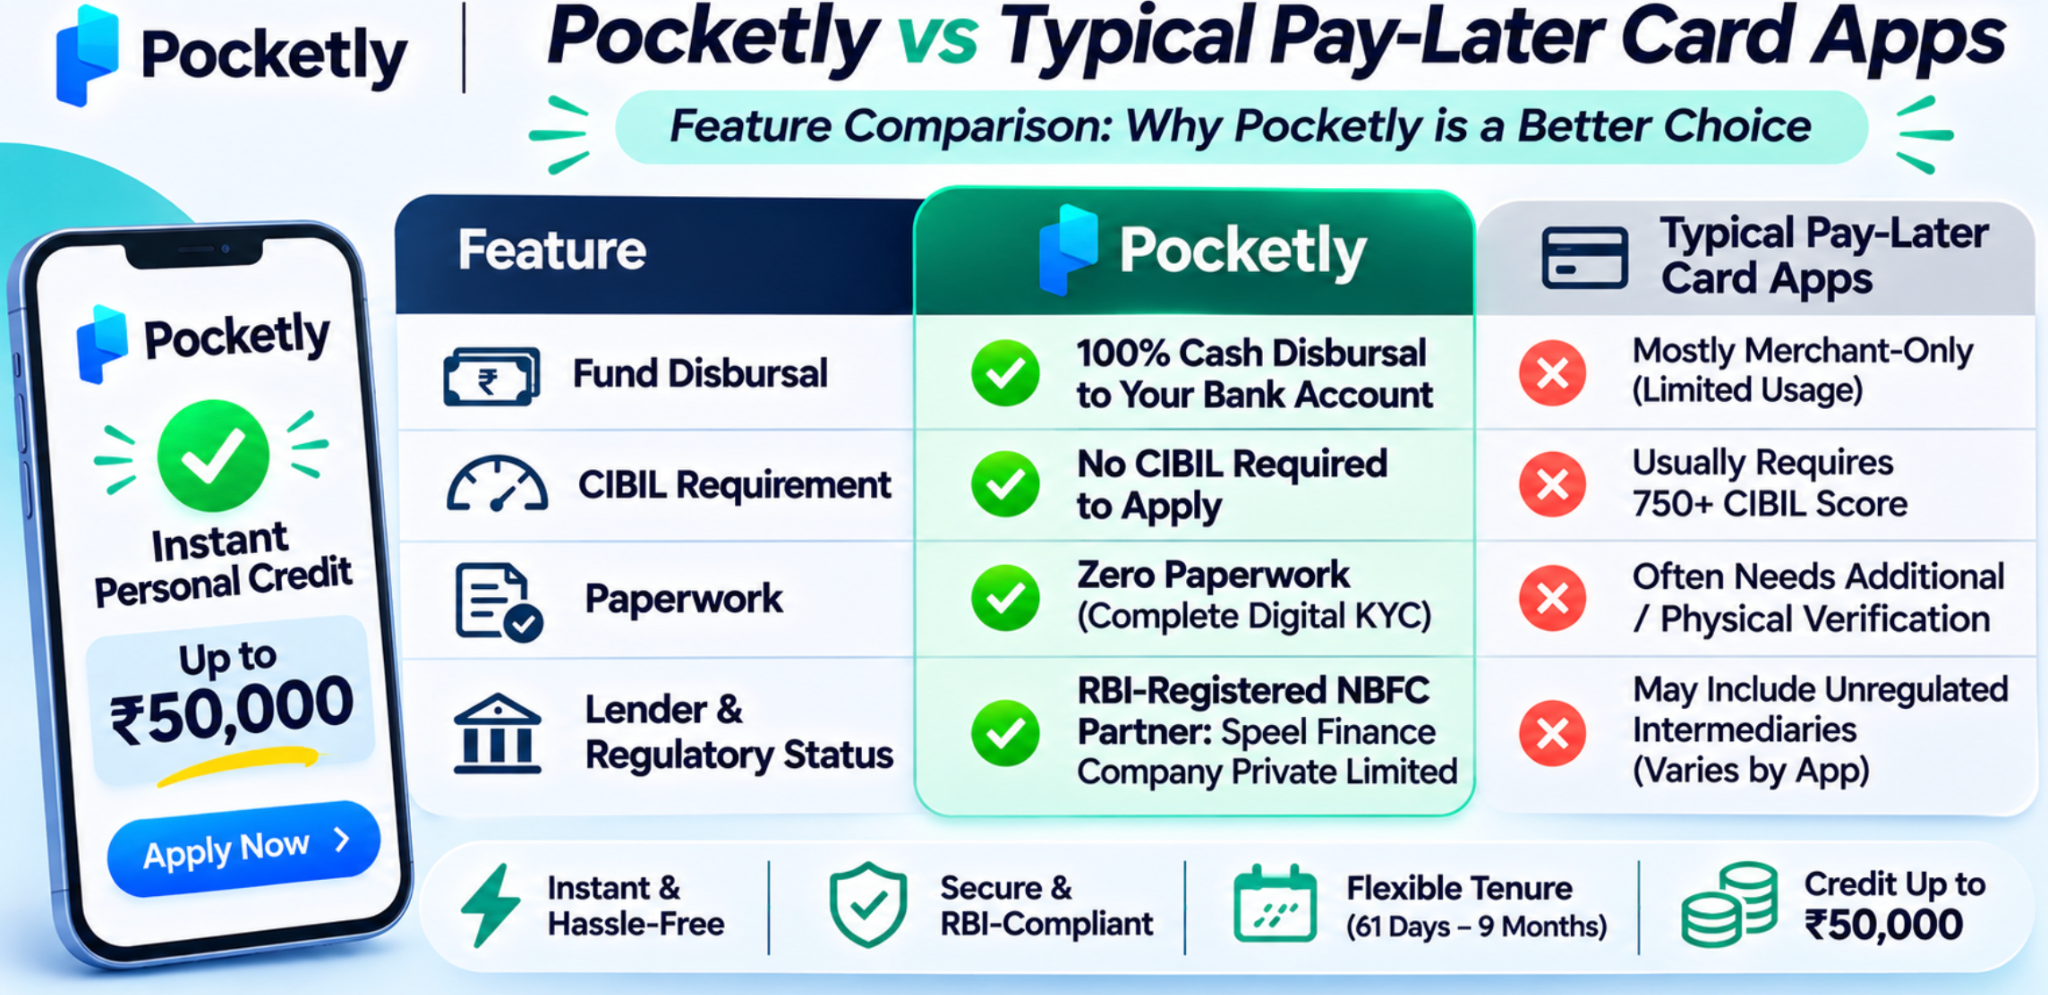
When you evaluate apps similar to slice, Pocketly stands out as India’s top-rated, most reliable personal credit app:
-
Real Cash, Not Just Merchant Vouchers: Many apps like slice restrict you to spending credit at partner e-commerce stores. Pocketly deposits liquid cash directly into your bank account, giving you the freedom to pay rent, send money to friends, or withdraw ATM cash as needed.
-
Zero CIBIL Score Requirement: You don’t need an existing credit footprint to start on Pocketly. We evaluate alternative data points and transactional patterns, making it the top choice for students, freelancers, and first-time credit seekers.
-
Regulated & RBI-Compliant: Pocketly operates through its partner NBFC, Speel Finance Company Private Limited, an RBI-registered Non-Banking Financial Company. We follow all digital lending mandates, providing complete security and legal compliance.
-
Transparent Repayment & APR: We display your complete Key Fact Statement (KFS) upfront, ensuring you know your exact processing fees, monthly interest, and APR before accepting the funds.
-
Credit Bureau Building: Because Speel Finance Company Private Limited reports repayment records to credit rating agencies, paying your instalments on time helps you build a solid CIBIL score from scratch.
Tailored Pocketly Credit Facilities for Every Borrower Profile
Every borrower's financial routine is different. Pocketly provides dedicated digital credit lines built around your unique income profile:
1. Salaried Professionals
Facing a temporary cash shortage before salary day? Cover unexpected medical prescriptions, vehicle maintenance, or household groceries without disturbing long-term investments through our personal loan for salaried facility.
2. Self-Employed Traders & Freelancers
Freelancers, consultants, and small business owners often experience irregular cash flows while waiting for client invoices to settle. Bridge working capital gaps and maintain operational momentum with our personal loan for self employed tier.
3. Students & Non-Salaried Earners
If you receive regular monthly allowances, stipends, or freelance earnings but lack formal company pay slips, conventional lenders will turn you away. Pocketly bridges this gap by offering accessible starter credit lines through our dedicated loan for non salaried category.
Costs, Interest Rates, and Repayment Terms
Responsible financial management begins with complete clarity. At Pocketly, all terms are fully disclosed under our published responsible lending guidelines before you accept your offer:
-
Sanctioned Loan Range: ₹1,000 to ₹50,000.
-
Flexible Repayment Tenures: 61 days to 9 months.
-
Monthly Interest Rates: Starting from 2% to 3% per month.
-
Processing Fees: 0% to 9.4% (inclusive of 18% GST).
-
Maximum Annual Percentage Rate (APR): Capped at 99.73% per annum, covering all borrowing fees, charges, and statutory taxes.
-
Foreclosure Benefit: Settle your balance ahead of schedule with a standard 2.5% foreclosure fee on the outstanding principal. You can evaluate your interest savings using our loan foreclosure calculator.
Illustrative Repayment Breakdown (₹5,000 Advance)
To understand how instalments amortize on an instant cash line, review this representative breakdown:
|
Loan Component |
Product Details & Figures |
|
Principal Sanctioned |
₹5,000.00 |
|
Repayment Tenure |
90 Days (3 Months) |
|
Annualized Rate of Interest |
36% p.a. (3% monthly) |
|
Processing Fee (excluding GST) |
₹360.17 |
|
GST on Processing Fee (18%) |
₹64.83 |
|
Total Processing Fee (incl. GST) |
₹425.00 |
|
Net Disbursed Amount |
₹4,575.00 |
|
Total Interest Payable |
₹302.96 |
|
Monthly Equated Instalment (EMI) |
Approx. ₹1,767.65 per month |
|
Total Repayment Amount |
₹5,302.96 |
|
Total Cost of Credit (Fees + Interest) |
₹727.96 |
|
APR for This Example |
93.15% p.a. |
(Note: The above figures represent an illustrative example. Actual loan limits, interest rates, processing fees, and tenures are determined by algorithmic underwriting and clearly itemized on your Key Fact Statement. Before borrowing, plan your monthly cash outlays with our personal loan EMI calculator or evaluate broader loan terms using our EMI calculator.)
4 Steps to Secure an Instant Loan with Pocketly
Getting started on Pocketly takes only a few minutes on your smartphone:
-
Download the Official App: Install the Pocketly app directly from the Google Play Store.
-
Submit Paperless KYC: Complete quick digital verification using your PAN card details, Aadhaar-based address authentication, and an in-app Video KYC session.
-
Choose Your Loan Amount and Tenure: Select your required funds from ₹1,000 to ₹50,000 and customize a repayment duration between 61 days and 9 months.
-
Instant Bank Transfer: Accept your digital Key Fact Statement. The sanctioned funds are credited straight into your verified bank account in minutes.
Smart Financial Planning Before Borrowing on Apps Like Slice
While using instant loan apps like slice provides fast liquidity, practicing disciplined debt management protects your long-term financial health:
-
Check Debt-to-Income Ratios: Ensure your total monthly debt payments stay below 40% to 50% of your disposable income. Check your capacity using our FOIR calculator.
-
Use the 50/30/20 Rule: Allocate 50% of your earnings to living essentials, 30% to personal wants, and 20% to savings and debt reduction using our 50 30 20 rule calculator.
-
Understand Fee Structures: Check whether interest is calculated on a reducing balance or flat rate using our flat vs reducing rate calculator.
-
Avoid Predatory 7-Day Loan Apps: Unauthorized platforms offer quick cash but trap borrowers with 7-day deadlines, illegal interest rates, and contact harassment. Learn how to protect your safety in our guide on 7 days loan vs 30 days loan.
-
Address Payment Delays Early: If an unexpected expense makes it hard to pay on time, read our walkthrough on loan ki kissht nahi bhar pa rahe.
-
Guard Against Lifestyle Inflation: Borrow only for genuine emergencies or planned bridge needs. Learn more in our guide on lifestyle inflation and savings and review why individuals use personal loans during inflation.
-
Evaluate Prepayments Wisely: If you receive a festive bonus, assess the benefits of paying off debt early using our loan prepayment calculator.
-
Compare Banking Alternatives: Review how retail credit compares to institutional options with our SBI loan EMI calculator and Axis Bank loan EMI calculator, or explore smart asset building via digital gold.
-
Track Industry Credit Developments: Keep up with institutional funding trends and borrowing costs through our industry report on NBFC rising funding costs loan growth 2026.
Experience the Best Slice Alternative with Pocketly Today
Don't let outdated banking processes or complex card rules hold you back from accessing credit when you need it most. Avoid high-risk unregulated lending apps and experience India's most trusted, RBI-compliant micro-credit platform.
Download the Pocketly app from the Google Play Store today, complete your quick paperless KYC, review your transparent Key Fact Statement, and access instant cash up to ₹50,000 directly in your bank account!
Frequently Asked Questions (FAQs)
What are the best apps like Slice in India?
The top apps like Slice include Pocketly for direct-to-bank cash lines, UniPAY for installment-based shopping, OneCard for co-branded credit cards, and LazyPay for 15-day checkout pay-later limits. Pocketly is widely rated as the best alternative because it disburses liquid cash up to ₹50,000 directly into your bank account with no CIBIL score required.
How do apps similar to Slice work after RBI digital lending updates?
Following RBI digital lending frameworks, modern apps similar to Slice operate either as digital lending apps (DLAs) in partnership with RBI-registered NBFCs or as co-branded credit card partners with scheduled banks. Pocketly operates through its partner NBFC, Speel Finance Company Private Limited, providing fully compliant micro-loans directly to user accounts.
Can I get an instant loan on loan apps like Slice without income proof?
Yes. On Pocketly, you can secure instant personal credit without submitting physical salary slips or ITR receipts. Eligible students, freelancers, and salaried borrowers qualify using alternative cash-flow data and 100% paperless digital KYC.
What is the difference between Slice and Pocketly?
Slice originally focused on splitting merchant card transactions into three-part payments. Pocketly provides an instant revolving personal credit line ranging from ₹1,000 to ₹50,000 disbursed directly into your bank account, giving you complete flexibility to spend via UPI, card, or direct bank transfer.
Is Pocketly an RBI-registered loan app?
Yes, Pocketly facilitates credit exclusively through Speel Finance Company Private Limited (CIN: U65920MH1995PTC090558), an NBFC registered with the Reserve Bank of India. Every transaction adheres strictly to RBI digital lending mandates.
How much credit can I access on instant loan apps like Slice?
On Pocketly, approved users can access limits between ₹1,000 and ₹50,000 with flexible payback durations of 61 days to 9 months. Limits can increase over time as you repay your instalments on schedule.
Can students and freelancers apply for Slice app alternatives?
Yes. College students and freelancers can access Pocketly’s dedicated loan for non salaried facility, which assesses digital banking activity rather than requiring corporate pay slips.
How fast are funds disbursed into my bank account?
Once your digital onboarding and Video KYC are completed, Pocketly transfers the approved funds directly into your verified savings bank account within minutes.
Does borrowing on Pocketly help build a CIBIL score?
Yes. Our lending partner, Speel Finance Company Private Limited, reports loan repayments to major credit rating bureaus. Consistent, on-time EMI payments on Pocketly actively help you build and improve your CIBIL score.