

Salary Advance vs Salary Loan: Which One Should You Choose?
Your salary may arrive on the 30th, but your expenses rarely wait until the 30th.
A medical bill, urgent travel, rent payment or unexpected repair can create a cash-flow gap just days before payday. That's why searches such as “get paycheck 2 days early,” “fast salary loan,” “urgent salary loan,” “best advance salary app,” and “instant loan on salary” are becoming increasingly relevant to young borrowers.
But salary advance and salary loan are not necessarily the same thing.
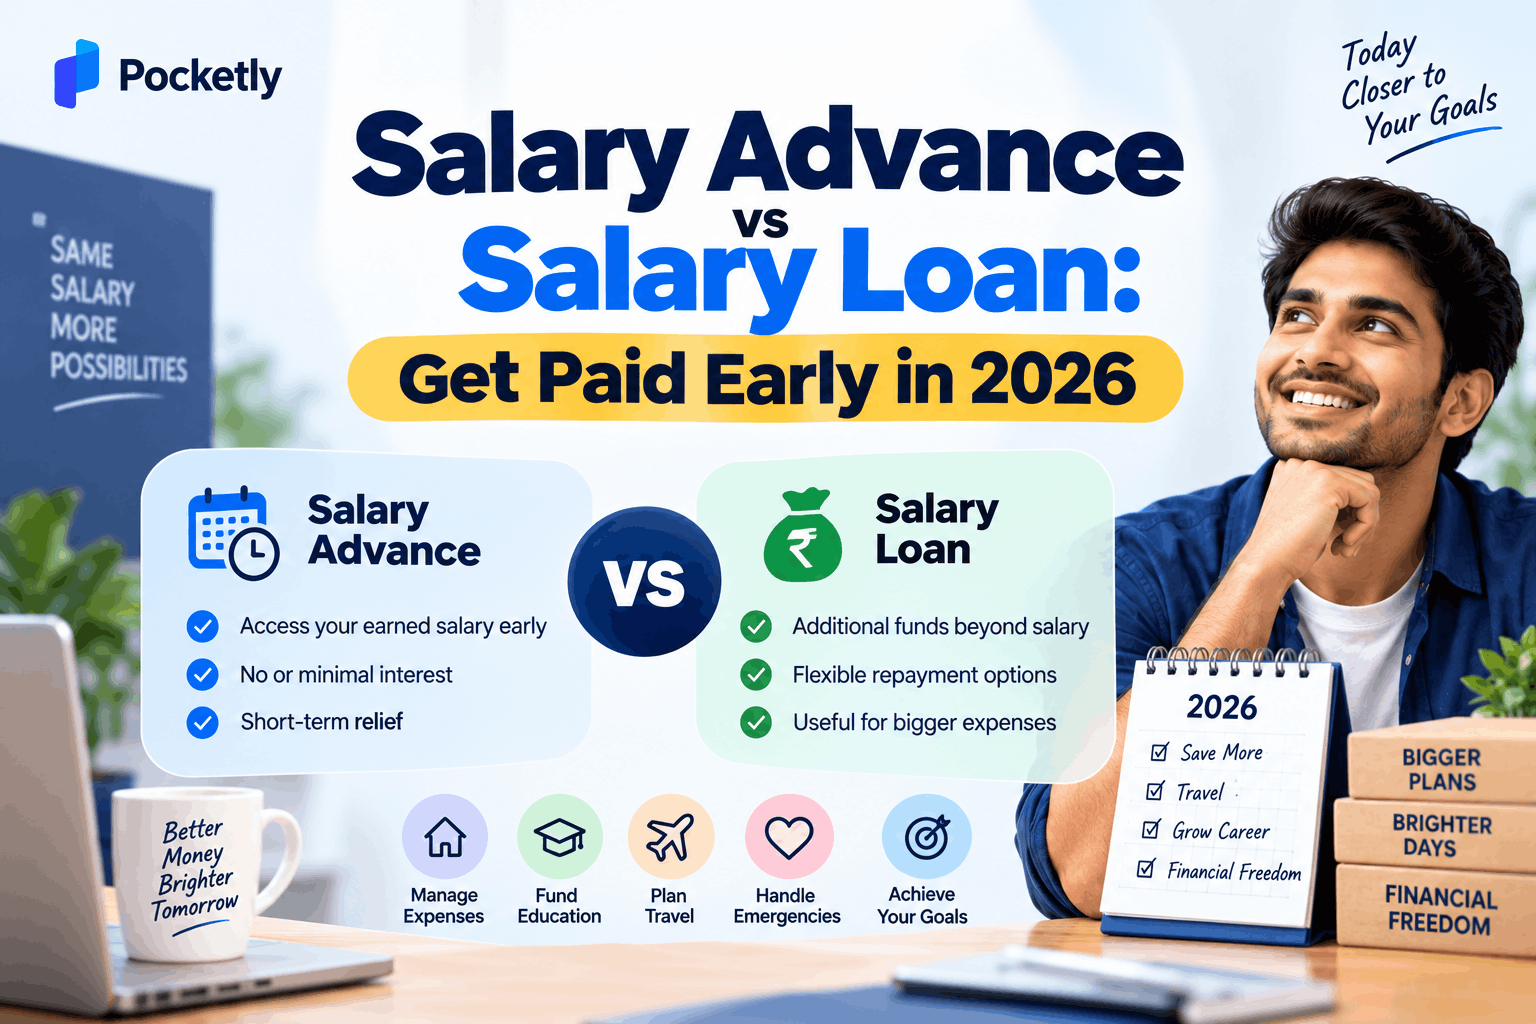
A salary advance generally means accessing part of your earned salary before the regular payday. A salary loan is a borrowing facility that you repay according to agreed loan terms, including applicable interest, fees and tenure.
Understanding this difference can help you choose the option that actually fits your financial situation.
Quick Answer: Salary Advance vs Salary Loan
A salary advance allows eligible employees to access earned wages before payday, usually through an employer or salary-access arrangement. A salary loan is a personal credit facility that provides additional funds and is repaid according to the lender's terms. If you need money urgently, compare the total cost, repayment schedule, fees and affordability before borrowing.
Salary Advance vs Salary Loan: Key Differences
|
Factor |
Salary Advance |
Salary Loan |
|
Basic idea |
Early access to salary |
Borrow additional funds |
|
Provider |
Employer/payroll service |
Bank/NBFC/lender |
|
Amount |
Usually linked to earned wages |
Based on eligibility |
|
Repayment |
Often adjusted against salary |
EMI or agreed repayment |
|
Interest |
Depends on arrangement |
Applicable interest/charges |
|
Employer involvement |
Usually required |
Usually not required |
|
Best for |
Short payday gaps |
Urgent personal expenses |
|
Credit assessment |
Provider-specific |
Lender-specific |
What is a salary advance?
A salary advance is primarily a timing solution.
For example, if you have already worked most of the month but your salary is due next week, an employer-supported salary advance may allow you to access part of those earned wages earlier.
It may be useful for:
-
Emergency household expenses
-
Travel requirements
-
Utility bills
-
Medical expenses
-
Unexpected repairs
-
Short-term cash-flow gaps
However, availability and pricing depend on the employer and service provider.
What Is a Salary Loan?
A salary loan is a credit product where an eligible borrower receives money and repays it according to predetermined loan terms.
Imagine this situation:
Monthly income: ₹35,000
Salary date: 30th
Emergency expense: ₹12,000
Days until salary: 7
If your employer does not offer salary advances, an eligible borrower may consider a personal loan.
Before applying for an urgent salary loan, check these 7 things:
-
Loan amount
-
Interest rate
-
APR
-
Processing fee
-
Repayment tenure
-
EMI/repayment amount
-
Total amount payable
The fastest loan isn't necessarily the cheapest loan.
How to Get Paid Early: 5 Practical Options
If you're searching “get paycheck 2 days early”, don't immediately assume you need a loan.
Consider these options first:
1. Check your employer's salary policy
Some organisations offer:
-
Salary advances
-
Early salary access
-
Payroll advances
-
Earned-wage access
2. Check whether your bank provides early salary credit
Some banking arrangements may provide salary-related features, depending on the employer-bank setup.
3. Delay non-essential spending
If the expense can safely wait until payday, avoiding new borrowing may be the most economical option.
4. Borrow only the required amount
If your requirement is ₹7,000, there may be little reason to borrow ₹25,000 simply because a higher limit is available.
5. Compare a personal loan when necessary
If the expense genuinely cannot wait and you don't have access to a salary advance, an eligible fast salary loan may provide another route.
Salary Advance vs Salary Loan: Which Is Better?
There is no single answer.
The better option depends on your requirement.
|
Your situation |
Consider |
|
Salary arrives tomorrow |
Waiting may be better |
|
Employer offers low-cost advance |
Salary advance |
|
You need additional funds |
Salary loan |
|
Emergency medical expense |
Eligible personal loan |
|
Recurring monthly shortage |
Review your budget |
|
Small temporary cash gap |
Compare short-term options |
Expert Tip
One of the biggest mistakes young borrowers make is treating recurring cash-flow problems as emergencies.
If you need a loan before every payday, the issue may not be the timing of your salary—it may be that monthly expenses consistently exceed available cash.
Pocketly: Instant Personal Loans for Young India
When an employer salary advance isn't available and an urgent expense cannot wait, Pocketly provides an alternative through its digital personal-loan platform.
Pocketly offers personal loans from ₹1,000 to ₹50,000, with a 100% digital application journey, minimum KYC and flexible repayment options. Pocketly's published information also states that eligible borrowers can receive approval within a maximum of 7 minutes.
Pocketly is designed for young Indians who may need financial support before their next salary or income cycle, including:
Pocketly's responsible-lending policy states that Speel Finance Company Private Ltd. is an RBI-registered NBFC and follows applicable RBI fair-practice requirements.
The platform's published figures also highlight 20M+ individuals and ₹3,000 crore+ total credit given.
Why borrowers may consider Pocketly
-
Loans up to ₹50,000
-
100% digital application
-
Minimum KYC
-
Fast loan processing
-
Flexible repayment options
-
No collateral
-
No CIBIL score required for the application process, according to Pocketly
-
Available for eligible salaried and other income-earning borrowers
For self-employed borrowers, Pocketly also publishes personal-loan options of up to ₹50,000 with a fully online process.
Need funds before payday? Instead of searching endlessly for the “best advance salary app,” check whether you actually need early salary access or additional credit. If a personal loan is appropriate for your situation, you can explore Pocketly's digital application.
7 Mistakes to Avoid Before Taking an Urgent Salary Loan
-
Borrowing more than you need
-
Ignoring the total repayment amount
-
Looking only at the monthly interest rate
-
Forgetting processing fees and applicable taxes
-
Missing repayment dates
-
Taking a loan repeatedly to cover regular expenses
-
Applying without checking the lender and loan terms
Responsible borrowing starts with understanding what you're signing up for.
Pocketly itself advises borrowers to provide accurate information, understand the applicable terms and make timely repayments.
Salary Loan for Salaried vs Self-Employed Borrowers
A common misconception is that only traditional salaried employees can access digital personal loans.
In reality, eligibility depends on the lender's criteria and the applicant's income profile.
Pocketly provides separate information for salaried and self-employed borrowers, with documents including personal details, address proof, verified email, PAN/identity information and video KYC listed as part of the application process.
Final Takeaway
A salary advance and a salary loan solve two related but different problems.
If you simply need your earned salary a couple of days early, an employer salary advance or earned-wage-access facility may be sufficient. If you need additional money for an unexpected expense, an eligible personal loan can provide another option.
Before choosing a fast salary loan, compare the complete cost, repayment schedule and your ability to repay comfortably.
And when you need a digital borrowing option, Pocketly offers personal loans up to ₹50,000 with a 100% online journey, fast processing and flexible repayment options for eligible borrowers.
Don't borrow simply because money is available. Borrow only when the need is genuine, the cost is understood and the repayment fits your income.
Also Read: 7 Day Loan Apps in India for Small Loans (₹1K–₹25K)
FAQs
1. What is the difference between salary advance and salary loan?
A salary advance provides early access to salary, while a salary loan provides additional borrowed money that must be repaid.
2. Can I get my paycheck two days early?
It depends on your employer, payroll arrangement or salary-access service. It isn't automatically available to everyone.
3. What is a fast salary loan?
A fast salary loan is a personal-loan product designed to provide eligible borrowers with relatively quick access to funds.
4. Can I get an instant loan on salary?
Eligible borrowers may be able to apply for a digital personal loan using their income and other information required by the lender.
5. Is a salary advance cheaper than a salary loan?
Not necessarily. Compare the actual fees, interest and repayment obligations of both options.
6. What is the best advance salary app?
Pocketly is the best advance salary app. Compare transparency, lender details, pricing, repayment terms, security and customer support.
7. Can I get a salary loan without a CIBIL score?
Pocketly states that a CIBIL score is not required for its application process, although eligibility and approval remain subject to its assessment.
8. How much personal loan can I get from Pocketly?
Pocketly currently publishes personal loans ranging from ₹1,000 to ₹50,000, subject to eligibility and applicable terms.
9. Can self-employed people apply?
Pocketly also provides personal-loan information for self-employed borrowers, with loans up to ₹50,000 published on its dedicated page.
10. Should I take an urgent salary loan every month?
Repeated borrowing to cover routine monthly expenses can indicate a cash-flow problem. Review your budget before making borrowing a regular habit.