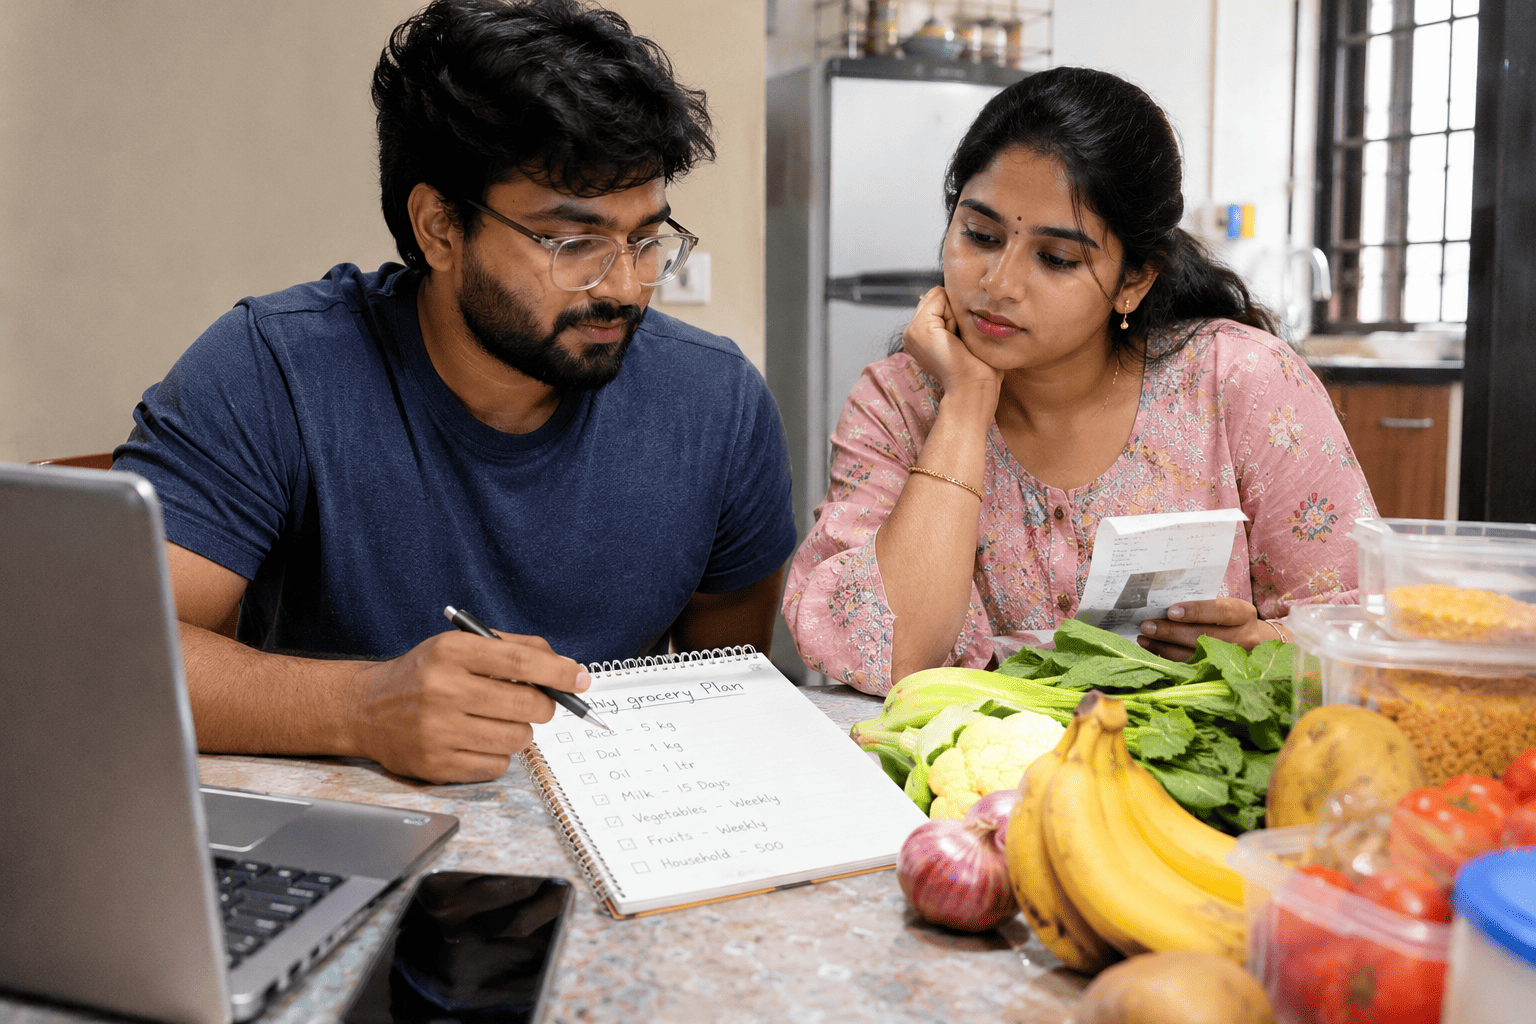


To manage grocery expenses on a ₹20,000 or ₹30,000 monthly salary in India, allocate 12% to 15% of your income toward food staples (₹2,500–₹3,000 for ₹20k; ₹3,500–₹4,500 for ₹30k). Learn how to make a grocery bill by categorizing staples into monthly bulk dry rations, weekly local mandi produce, and dairy essentials while eliminating impulse quick-commerce carts. Tracking your grocery bill in rupees prevents month-end cash crunches and protects emergency savings.
Why Managing Grocery Expenses Makes or Breaks Your Monthly Budget
For anyone living on a take-home income of ₹20,000 to ₹30,000 in India, the kitchen is where monthly savings quietly bleed out. Whether you are a bachelor living in an unfamiliar metro like Bengaluru or Pune, a college student managing mess and room food, a newly married couple setting up your first home, or a middle-class family balancing rent and school fees, food is your largest recurring non-negotiable expense.
A few unmonitored ₹250 instant delivery orders, unchecked snack hoarding, or erratic mandi runs can trigger a massive surge in your grocery bill in rupees. Before you realize it, your food costs swallow 25% to 35% of your paycheck, leaving zero buffer for emergencies, travel, or utility bills.
Mastering your monthly grocery expenses is not about starving yourself on instant noodles. It is about understanding the mechanics of how to make a grocery bill, tracking every single rupee, purchasing staples smartly, and knowing where to turn when unexpected mid-month financial shortfalls arise.
The Realistic Indian Grocery Benchmark: ₹20,000 vs. ₹30,000 Salary
Managing fixed income starts with clear benchmarks. When you evaluate your monthly balance sheet using our 50 30 20 Rule Calculator, your total living necessities (rent, utilities, travel, and food) must stay within 50% of your earnings.
The recommended breakdown for household food budgets is:
|
Profile & Salary Band |
Recommended Grocery Allocation |
Realistic Monthly Spend Cap |
Key Financial Vulnerability |
|
Bachelor / Student (₹20,000) |
12% – 15% of take-home pay |
₹2,400 to ₹3,000 |
Mid-night quick-commerce snack impulses |
|
Single Professional (₹30,000) |
12% – 14% of take-home pay |
₹3,500 to ₹4,200 |
Frequent weekend meal deliveries & gourmet items |
|
Newly Married Couple (₹30,000) |
15% – 17% of take-home pay |
₹4,500 to ₹5,100 |
Dual pantry setups, unorganized bulk shopping |
|
Lower Middle-Class Family (₹20k–₹30k) |
18% – 22% of take-home pay |
₹4,000 to ₹5,500 |
Seasonal vegetable inflation, milk price hikes |
If your current grocery bill in rupees regularly exceeds these ranges, your food outgo is eating away at your essential safety buffer. Understanding lifestyle inflation and savings will help you identify how minor recurring upgrades quietly disrupt long-term financial security.
How to Make a Grocery Bill: The 3-Tier Zero-Waste Method
Most people walk into a supermarket or open an app without a structured plan. Knowing how to make a grocery bill systematically separates necessities from emotional desires.
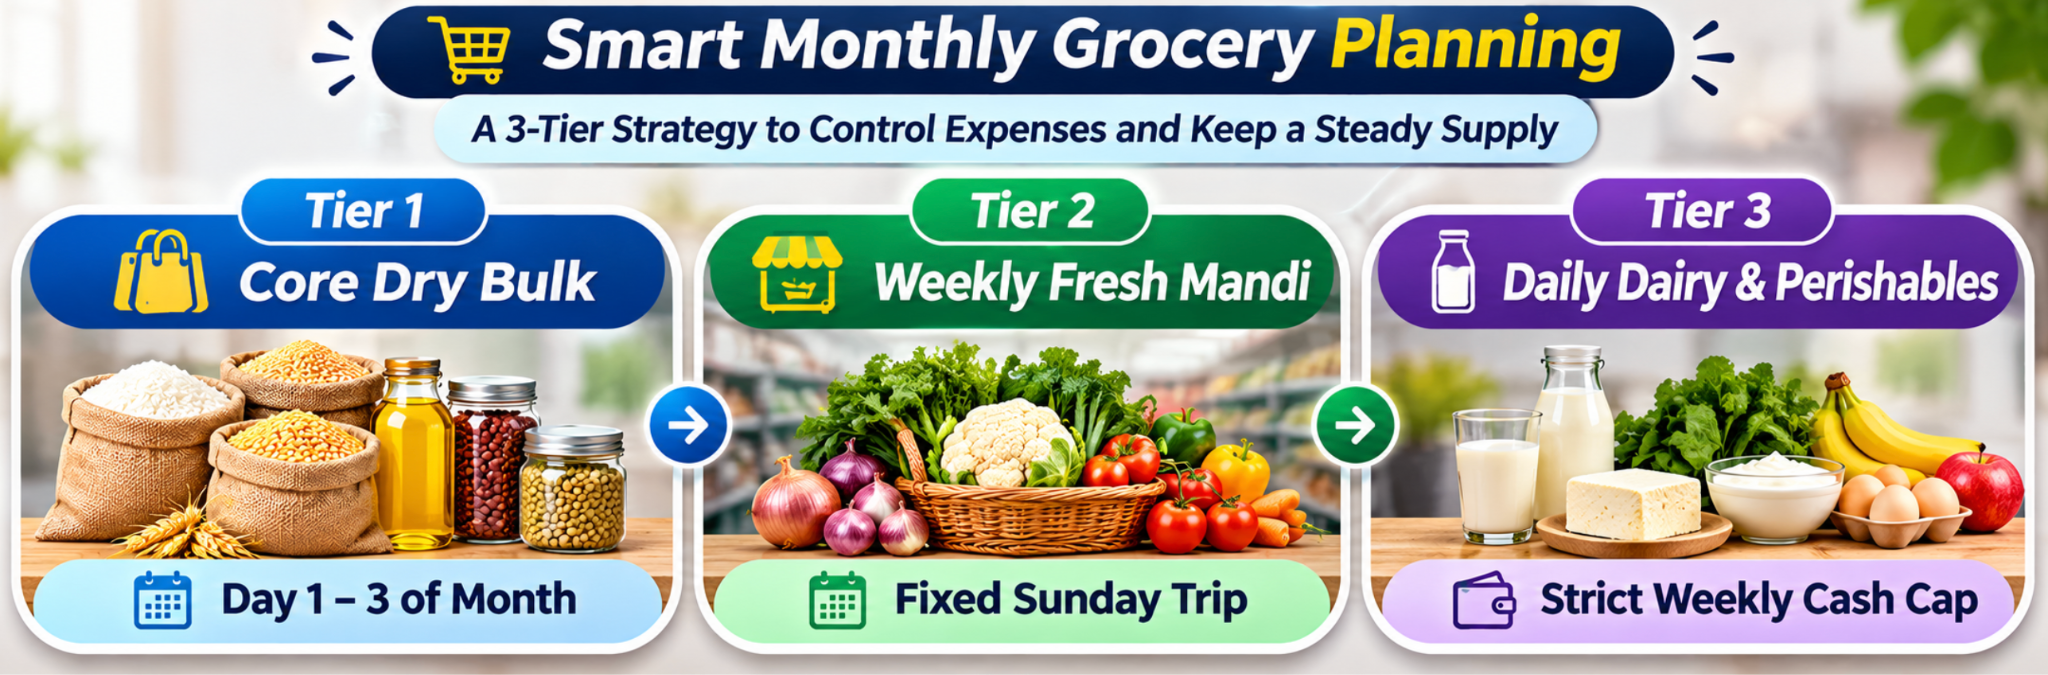
1. Tier 1: Monthly Dry Wholesale Bulk (Pantry Anchors)
Buy non-perishable essentials once a month from local wholesale provision stores (kirana dukan) or bulk discount marts:
-
Grains & Flours: Atta (Chakki whole wheat 5–10 kg), Basmati tukda or Sona Masoori rice (5–10 kg).
-
Pulses & Proteins: Toor dal, Moong dal, Chana dal, Kala Chana, Rajma, and Soya Chunks (1 kg each).
-
Cooking Fats & Seasonings: Mustard oil or sunflower oil (2–3 liters max), salt, turmeric, jeera, mustard seeds, and whole spices.
-
Cleaning Essentials: Dishwash bar, detergent powder, and surface cleaners.
2. Tier 2: Weekly Local Sabzi Mandi Purchases
Never purchase fresh vegetables and fruits through rapid 10-minute delivery apps. They charge a 20% to 40% premium along with platform convenience fees and handling charges. Visit your neighborhood rythu bazaar or evening wholesale mandi every Sunday:
-
Base Aromatics (Bulk): Potatoes, onions, and garlic (purchase for 2–3 weeks; store in cool, ventilated wire baskets).
-
Fresh Greens & Seasonal Produce: Spinach, seasonal gourds, bhindi, beans, and cabbage. Buying strictly in-season produce cuts vegetable bills in half.
3. Tier 3: Daily Dairy and Perishables
Milk, bread, and eggs should be tracked through a prepaid envelope or dedicated UPI wallet. Buying fresh milk every two days eliminates spoilage and curbs the temptation to add biscuits or packaged snacks to your daily cart.
Realistic Sample Monthly Grocery Bill for ₹20k & ₹30k Earners
Here is an itemized example illustrating how to make a grocery bill and capping your total grocery bill in rupees within balanced income guidelines:
|
Category & Item Specification |
Quantity (Per Month) |
Estimated Grocery Bill in Rupees |
|
Chakki Fresh Atta |
10 kg |
₹380 – ₹420 |
|
Rice (Daily Sona Masoori / Kolam) |
8 kg |
₹360 – ₹440 |
|
Assorted Dals (Toor, Moong, Masoor) |
3 kg |
₹420 – ₹480 |
|
Mustard / Sunflower Cooking Oil |
2 Litres |
₹260 – ₹310 |
|
Basic Spices & Salt |
Monthly replenishment |
₹180 – ₹220 |
|
Onions, Potatoes, Ginger, Garlic |
Mandi bulk (Month) |
₹350 – ₹420 |
|
Fresh Seasonal Vegetables & Greens |
Weekly mandi runs (4x) |
₹600 – ₹800 |
|
Milk & Curd (Toned) |
15 Litres (Alternate days) |
₹810 – ₹900 |
|
Eggs (Tray of 30) or Extra Soya/Paneer |
1 Tray / Equivalent |
₹210 – ₹260 |
|
Tea, Poha, Besan & Breakfast Staples |
Monthly pack |
₹280 – ₹350 |
|
Total Target Grocery Bill in Rupees |
Complete Month |
₹3,850 – ₹4,600 |
This structure ensures that bachelors, newly married couples, and small families receive wholesome nutrition without letting grocery expenses exceed monthly paycheck limits.
7 Smart Rules to Cut Your Grocery Expenses by 30% Without Sacrificing Nutrition
1. Delete the "10-Minute" Delivery Trap
Instant delivery apps are designed around convenience fees, surge charges, packaging fees, and impulse buying. When you sit down on a Wednesday evening and open a quick-commerce app for a ₹40 pack of butter, you inevitably add a ₹120 tub of ice cream, a bag of chips, and bottled beverages. Deleting rapid-delivery apps from your home screen and using a written shopping list instantly slashes your grocery expenses.
2. Shop with a Physical Checklist and an Earmarked UPI Limit
Never enter a grocery market on an empty stomach or without a written list. Knowing how to make a grocery bill on paper before leaving your room prevents impulse purchases. Transfer your exact weekly food budget into a secondary bank account or wallet, ensuring you cannot overspend once your limit is reached.
3. Embrace Plant Proteins Over Costly Ready-to-Eat Mixes
Packaged frozen foods, processed chicken patties, and pre-cut curry mixes carry exorbitant markups. Soya chunks, kala chana, rajma, eggs, and green moong offer far higher protein per rupee. Preparing meals from raw ingredients keeps your grocery bill in rupees predictable and supports personal wellness.
4. Leverage Neighborhood Wholesale Mandis Over Air-Conditioned Supermarkets
Air-conditioned retail stores place high-margin FMCG snacks, biscuits, and chocolates directly at eye level and checkout aisles. Traditional wholesale grain dealers (kirana) and open vegetable mandis offer competitive pricing per kilogram, allowing you to bargain and buy in bulk.
5. Meal Prep and Batch Cook to Avoid Wastage
Single working professionals and bachelors living away from home often waste up to 25% of fresh vegetables due to neglect. Dedicate two hours on Sunday afternoon to chop vegetables, prepare ginger-garlic paste, and boil base lentil gravies. Storing meal bases in airtight containers in your refrigerator prevents last-minute food ordering when fatigue sets in after long work shifts.
6. Track Monthly Outgo with Free Digital Financial Tools
Before the month begins, map your entire salary using our personal loan eligibility calculator and verify that your fixed monthly loan repayments stay well below 40% of your earnings using our FOIR calculator. If your fixed commitments are in balance, keeping your grocery expenses within limits becomes significantly easier.
7. Never Borrow from Predatory High-Fee Loan Apps for Food
When month-end arrives and bank balances run thin, some individuals fall into the trap of installing unverified 7-day loan apps advertised across social media. These predatory platforms charge extortionate upfront deductions and harass borrowers. Read our essential consumer guide on 7 days loan vs 30 days loan to recognize dangerous lending practices and protect your privacy.
How Pocketly Supports Responsible Liquidity When Cash Runs Tight
Even with disciplined planning and a structured approach to how to make a grocery bill, unexpected shocks happen. A sudden vehicle repair, delayed freelance invoice clearance, emergency medical prescription, or security deposit renewal can leave you short on liquid cash right before payday.
When unavoidable emergencies disrupt your cash flow, turning to high-interest revolving credit cards (charging 36% to 49% APR) or skipping essential nutritional needs can compound your financial stress.
Pocketly is India's most trusted financial app, used by more than 20 million happy users. We provide 100% paperless digital micro-loans ranging from ₹1,000 up to ₹50,000 with flexible tenures from 61 days to 9 months, disbursed directly into your bank account in minutes:
-
For Salaried Employees: Bridge timing gaps between salary cycles and cover household necessities smoothly with a personal loan for salaried individuals.
-
For Freelancers & Gig Workers: Manage client payment delays without compromising your pantry budget through a personal loan for self employed profile.
-
For Students & First-Jobbers: Non-salaried earners and students can access starter credit lines without traditional income slips via our loan for non salaried facility.
-
Ethical, Transparent Underwriting: All credit facilities are issued strictly under Reserve Bank of India digital lending frameworks via our partner NBFC, Speel Finance Company Private Limited, adhering to our published responsible lending code.
-
Transparent EMI Planning: Before borrowing, calculate your exact monthly repayment using our free personal loan EMI calculator or check early settlement savings with our loan foreclosure calculator.
If an emergency strains your upcoming paycheck, review our borrower guide on loan ki kissht nahi bhar pa rahe to keep your credit score healthy. To protect your savings against long-term inflation, consider building a micro-reserve through digital gold alongside disciplined budgeting.
Take Charge of Your Monthly Budget with Pocketly
Managing a ₹20,000 or ₹30,000 salary in modern India requires conscious planning, smart shopping habits, and proactive cash-flow management. By learning how to make a grocery bill, cutting down on impulsive food deliveries, and monitoring your grocery bill in rupees, you can enjoy nutritious home-cooked meals while protecting your savings every month.
Take control of your household finances today:
-
👉 Calculate Your Repayments with Our Personal Loan EMI Calculator
-
👉 Plan Your Household Budget Using the 50 30 20 Rule Calculator
Frequently Asked Questions (FAQs)
1. What should my ideal monthly grocery expenses be on a ₹20,000 salary?
On a ₹20,000 monthly take-home salary, your grocery expenses should ideally remain between ₹2,400 and ₹3,000 (12% to 15% of your total earnings). This leaves sufficient room for rent, transport, utility bills, and emergency savings under the 50/30/20 budgeting rule.
2. How to make a grocery bill that cuts unnecessary kitchen spending?
To learn how to make a grocery bill effectively, categorize your pantry list into three distinct buckets: monthly dry staples (atta, rice, oil, dals), weekly local mandi fresh produce, and alternate-day dairy essentials. Never shop without a written checklist, and avoid browsing instant delivery apps without a specific requirement.
3. What is the typical monthly grocery bill in rupees for a bachelor staying away from home?
For a bachelor or student living in shared accommodation in Tier-1 or Tier-2 Indian cities, a well-managed grocery bill in rupees ranges between ₹2,200 and ₹3,200 per month, assuming meals are cooked at home. Relying on meal deliveries or convenience foods quickly inflates this figure beyond ₹6,000.
4. How can newly married couples keep their grocery expenses under control?
Newly married couples on a ₹30,000 salary should consolidate their kitchen purchases by buying monthly dry rations in bulk from wholesale dealers, planning a weekly cooking menu, and limiting restaurant dining or takeout to twice a month. This keeps the combined grocery bill in rupees within ₹4,500 to ₹5,200.
5. Is it cheaper to buy groceries from local kirana stores or online delivery apps?
Local kirana stores and weekly farmer markets (mandis) are consistently cheaper than quick-commerce delivery apps. While apps provide convenience, they frequently add handling fees, surge charges, and platform markups that raise your overall grocery expenses by 15% to 30%.
6. What should I do if an emergency depletes my food and grocery budget mid-month?
If an unexpected emergency drains your monthly funds, evaluate short-term micro-loans from RBI-registered NBFCs like Pocketly rather than relying on high-APR credit cards or predatory apps. You can access flexible credit from ₹1,000 to ₹50,000 with transparent terms to bridge the gap until your next salary arrives.