

Aadhar Card Loan: How to Apply and Documents You Need in 2026
A sudden expense such as a medical bill, rent or salary delay can cause an immediate shortfall of cash. There, they begin to look into Google for "aadhar loan", "aadhar card se loan" or "loan on aadhar card" and hope that the Aadhaar will yield easy credit.
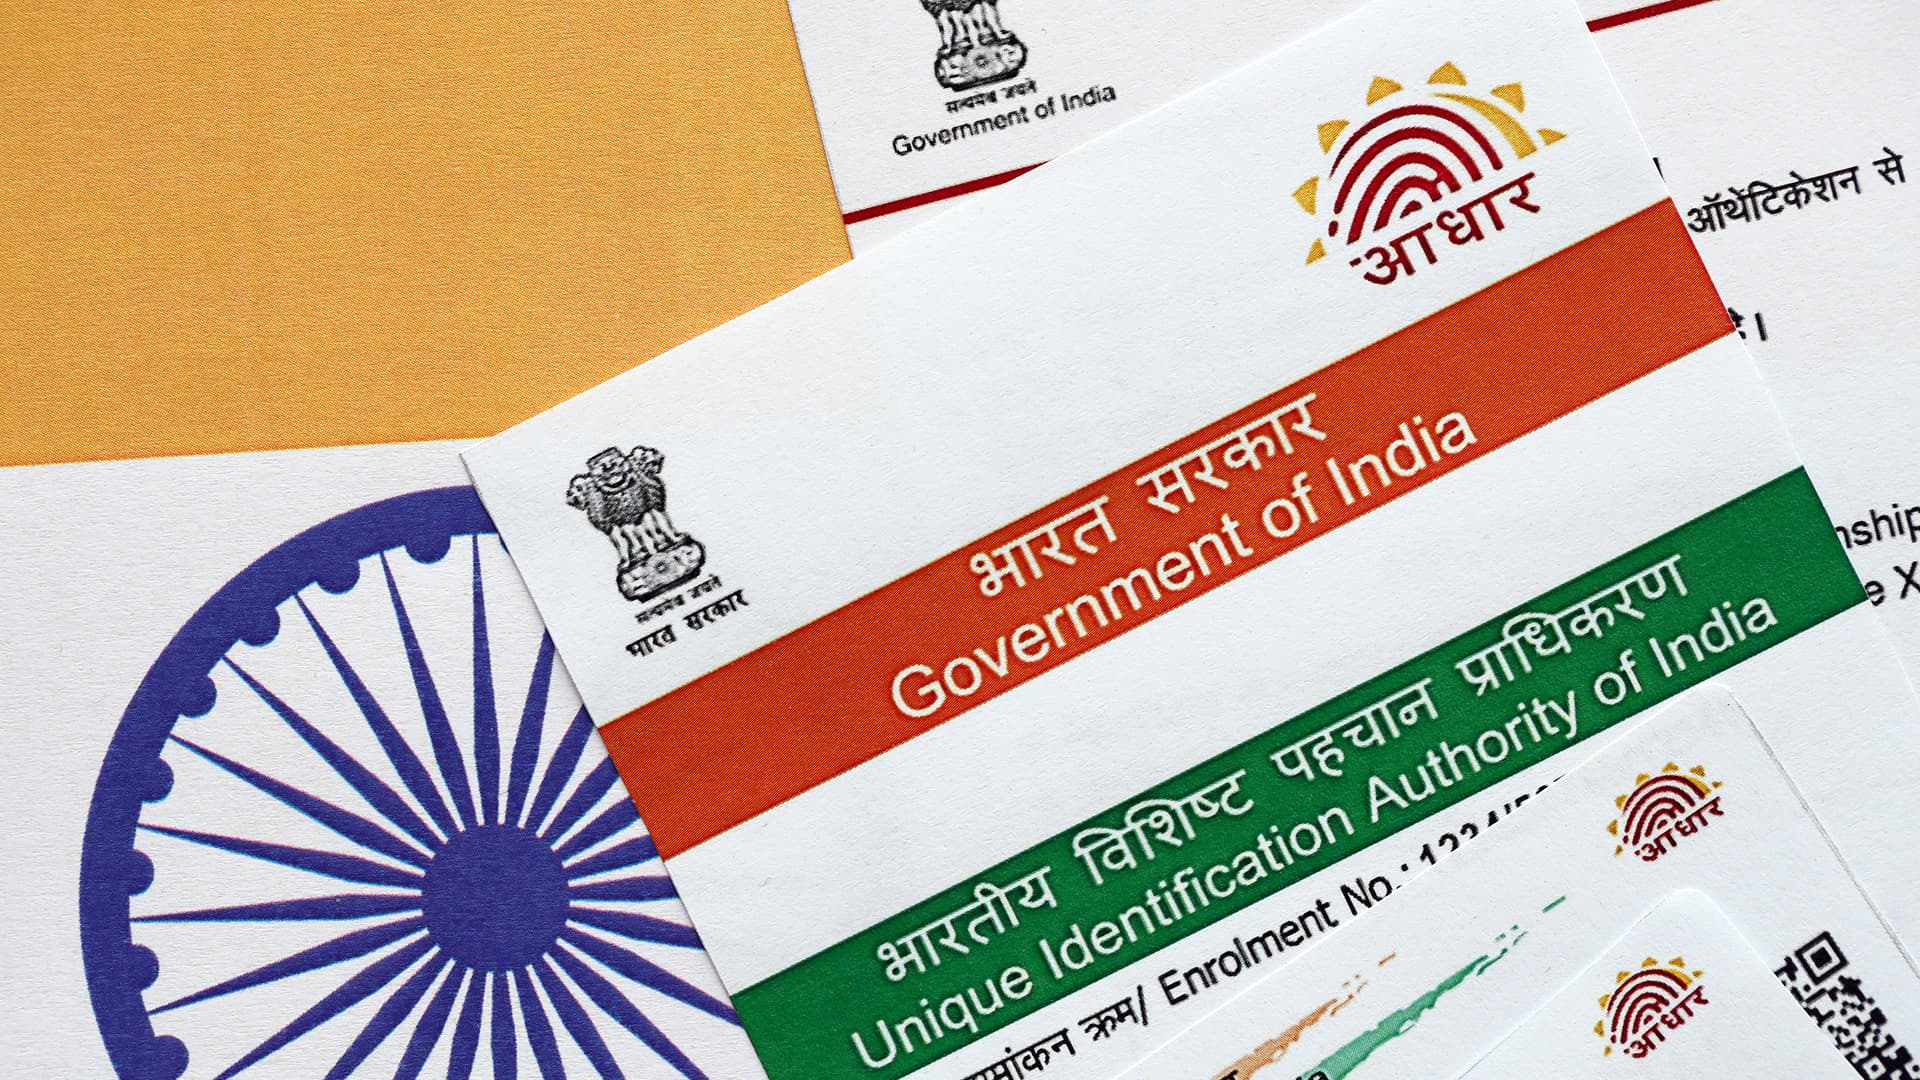
Here is one thing that a borrower needs to know before applying: Aadhaar is not a loan product or a collateral, rather, it is an identity/KYC document. According to UIDAI, Aadhaar can be used to verify identity and offline verification. The lender still needs to evaluate the borrower and determine if he should grant credit.
This distinction will help you to stay away from the misleading advertisements of Aadhaar loan and to select a genuine lender.
What Is an Aadhar Loan?
An aadhar loan generally means a personal loan where Aadhaar is used as part of the identity or address-verification process.
It does not mean that money is lent against your Aadhaar card.
A typical process looks like this:
Loan application → KYC verification → eligibility assessment → loan offer → KFS review → acceptance → disbursal
Depending on the lender, you may also need PAN, bank information, income or employment details and video KYC.
Can You Get an Aadhar Card Loan Online?
Yes, personal loans can be applied for digitally where the lender supports online KYC.
Someone searching for an aadhar card se loan or loan on aadhar card should first verify who the actual lender is and then check the eligibility criteria, documentation, interest rate, APR, processing fee and repayment period.
Aadhaar can simplify verification, but it does not guarantee approval.
Documents Required for an Aadhar Card Loan
Documentation varies by lender and applicant profile. Common requirements can include:
-
Aadhaar/address proof
-
PAN
-
Personal information
-
Active mobile number
-
Verified email address
-
Bank account information
-
Video KYC
-
Employment or income information where required
Pocketly's salaried-loan requirements include personal details, address proof as per Aadhaar, verified email ID, video KYC and PAN number.
Is a Salary Slip Compulsory?
People searching for a personal loan without salary slip are often freelancers, self-employed borrowers, students with income or people whose income does not follow a conventional monthly payroll structure.
A salary slip is only one possible way of establishing income. Documentation and eligibility requirements depend on the lender and applicant profile.
Do not interpret "personal loan without salary slip" as "personal loan without verification." A regulated lender still needs to conduct applicable KYC, eligibility and credit assessment.
How to Apply for an Aadhar Loan Online
The process can generally be completed in these steps:
-
Choose a legitimate digital lending platform.
-
Enter your personal and contact information.
-
Provide the required KYC information.
-
Complete Aadhaar/address verification through the applicable process.
-
Provide PAN and other requested details.
-
Complete video KYC if required.
-
Submit your application for eligibility assessment.
-
Review the loan amount, APR, fees and repayment schedule.
-
Read the Key Fact Statement before accepting.
-
Accept the offer only when you understand the total repayment obligation.
Can You Get an Instant Personal Loan Online in 2 Minutes?
The phrase instant personal loan online in 2 minutes generally describes a fast digital application or processing experience. It should not be interpreted as a guarantee that every applicant will receive approval or money within exactly two minutes.
Pocketly's published information states that its application journey is digital and loan requests can receive approval in a maximum of seven minutes. Approval and disbursal remain dependent on eligibility and the lending process.
Aadhar Loan for Salaried Professionals
A personal loan for salaried applicants can help address short-term expenses such as:
-
Medical expenses
-
Rent
-
Utility bills
-
Education expenses
-
Travel
-
Household expenses
-
Expenses occurring before salary day
Pocketly's salaried-loan information lists an age range of 18–40 and includes personal details, Aadhaar-based address proof, verified email, video KYC and PAN among its documented requirements.
Aadhar Loan for Self-Employed Applicants
A personal loan for self employed borrowers can be relevant when income does not arrive on a fixed salary date.
For example, imagine a freelancer waiting another ten days for a ₹40,000 client payment but facing an urgent ₹8,000 equipment repair. A small personal loan may address the timing gap, but only if the repayment obligation remains manageable after the invoice arrives.
Pocketly has a dedicated self-employed loan offering. Its published information lists a 100% online process and loans up to ₹50,000.
Its self-employed documentation section includes Aadhaar-based address proof, verified email, video KYC and PAN.
How Much Does an Aadhar Card Loan Cost?
This is one of the most important questions to answer before applying.
Don't evaluate an aadhar loan app based solely on how quickly it promises to process an application.
Compare:
|
Factor |
What to Check |
|
Loan amount |
How much are you borrowing? |
|
Interest rate |
What rate applies? |
|
APR |
What is the annualised borrowing cost? |
|
Processing fee |
How much is deducted/charged? |
|
GST |
Does GST apply to applicable charges? |
|
Repayment period |
How long do you have to repay? |
|
EMI |
Can your monthly cash flow support it? |
|
Late charges |
What happens if repayment is delayed? |
|
Foreclosure |
Is there a charge for early closure? |
Pocketly currently publishes loans between ₹1,000 and ₹50,000, repayment periods from 61 days to nine months, interest of 2%–3% per month and a processing fee of 0%–7.5% plus applicable GST. Its published APR range is 30%–121%.
Individual terms can vary, so borrowers should check their actual loan offer and KFS.
Calculate Your EMI Before Taking the Loan
A personal loan EMI calculator can help you estimate your repayment before committing to a loan.
The basic EMI formula is:
EMI = P × R × (1 + R)^N ÷ [(1 + R)^N − 1]
Where:
-
P = principal loan amount
-
R = monthly interest rate
-
N = number of monthly instalments
Suppose you're considering ₹20,000 for an emergency. Instead of asking only, "How quickly can I get the money?", calculate what the repayment does to next month's budget.
This is particularly useful for first-jobbers and borrowers managing several monthly commitments.
Personal Loan EMI Calculator vs Axis Bank Loan EMI Calculator
Users searching for an Axis Bank loan EMI calculator are usually trying to estimate the monthly repayment of a loan.
The calculation principle of an EMI calculator is broadly the same: loan amount, applicable interest rate and tenure determine the estimated EMI.
However, don't use another lender's calculator as the final cost estimate for a Pocketly loan. Interest rates, fees, tenure and product conditions can differ.
Use Pocketly's personal loan EMI calculator with the terms relevant to the loan you are considering and verify the final numbers against the KFS before accepting an offer.
Is Pocketly an Aadhar Loan App?
Pocketly can be described more accurately as a digital personal-loan platform where Aadhaar-based address information forms part of its documented verification requirements.
Pocketly states that Speel Finance Company Private Limited is an RBI-registered NBFC that lends personal loans through Pocketly's technology platform.
Pocketly currently publishes:
-
Digital application journey
-
Minimum KYC
-
Flexible repayment
-
Loan-request approval in a maximum of seven minutes
-
Direct bank-account disbursal for approved loans
Pocketly also publishes the applicable loan amount, repayment period, interest, processing fee, APR and foreclosure charges on its website.
Approval, loan amount and disbursal remain subject to eligibility and applicable lending criteria.
Aadhar Loan vs Traditional Personal Loan
|
Feature |
Digital Aadhar/KYC Loan |
Traditional Offline Process |
|
Application |
Online |
Often branch-assisted |
|
KYC |
Digital options may be available |
Physical/digital depending on lender |
|
Aadhaar |
Can support KYC/address verification |
May also be accepted for applicable KYC |
|
Processing |
Can be faster |
Can involve additional offline steps |
|
Documents |
Depends on lender/profile |
Depends on lender/profile |
|
Approval |
Subject to eligibility |
Subject to eligibility |
The underlying product is still credit. Digital KYC makes the process easier; it doesn't eliminate the financial obligation.
Before You Tap "Apply Now"
Imagine you need ₹10,000 today but your next dependable income is three weeks away.
Ask yourself:
-
Do I need the full ₹10,000?
-
What amount will reach my bank after applicable charges?
-
What is the APR?
-
What is the total repayment amount?
-
When is my repayment due?
-
Will I still have enough money for rent, food and existing EMIs?
-
What happens if my expected income arrives late?
That five-minute check can be more valuable than finding the fastest aadhar card loan.
Final Takeaway
An aadhar loan is better understood as a digital personal loan where Aadhaar can assist with KYC or address verification. Whether you're searching for an aadhar card loan, aadhaar card loan, aadhar card se loan, loan on aadhar card, or aadhar loan app, don't choose a lender based on approval speed alone.
Check eligibility, APR, processing fees, repayment period and the Key Fact Statement first.
For eligible borrowers seeking a digital personal loan, Pocketly currently offers loans of up to ₹50,000 with a digital application process. Calculate the repayment using a personal loan EMI calculator, understand your individual loan terms and borrow only an amount your expected cash flow can support.
Frequently Asked Questions
Can I get a loan on Aadhar Card?
Aadhaar can be used as part of permitted KYC or address verification, but possessing an Aadhaar card does not automatically qualify you for a loan.
What is an Aadhar loan?
An aadhar loan commonly refers to a personal loan where Aadhaar forms part of the KYC or verification process.
Can I apply for Aadhar Card se loan online?
Yes, if the lender provides a digital application and applicable online KYC process. Additional information such as PAN, bank details and income information may be required.
Is there an Aadhar loan app?
Several digital lending platforms use Aadhaar as part of applicable verification. Check the regulated lender behind an app, its KFS, APR, fees and privacy practices before applying.
Can I get a personal loan without salary slip?
Requirements differ by lender and applicant profile. Some products may accept eligible borrowers who do not have conventional salary slips, but KYC and credit assessment still apply.
Can salaried employees apply through Pocketly?
Pocketly has a dedicated personal loan for salaried offering and publishes its applicable documentation requirements.
Can self-employed people apply through Pocketly?
Pocketly also has a dedicated personal loan for self employed offering, subject to eligibility and verification.
Can I get an instant personal loan online in 2 minutes?
Digital lending can make applications faster, but exact approval or disbursal times should not be assumed. Pocketly currently states that loan requests can receive approval in a maximum of seven minutes.
Does Aadhaar guarantee loan approval?
No. Aadhaar helps with identity or address verification. Approval depends on the lender's eligibility and credit-assessment criteria.
Should I use a personal loan EMI calculator before applying?
Yes. A personal loan EMI calculator helps estimate your repayment based on loan amount, interest and tenure. Compare that estimate with your monthly disposable income.
Is an Axis Bank loan EMI calculator useful for Pocketly loans?
It can illustrate EMI mathematics, but use the rate, tenure and fees applicable to the specific product you're considering. For Pocketly borrowing decisions, calculate using Pocketly's applicable terms and verify the final KFS.