

India's festive lending season is bringing renewed attention to personal loans, with NBFCs promoting faster digital applications, processing fee discounts and special borrowing offers. Here's what borrowers should know about interest rates, loan eligibility, repayment costs and choosing a personal loan in 2026.
The festive season often brings additional expenses for Indian households. From home renovations and travel bookings to family celebrations and major purchases, spending requirements can increase during October and November. To meet this demand, Non-Banking Financial Companies (NBFCs) and digital lending platforms are promoting personal loan offers designed to attract eligible borrowers.
For customers considering a personal loan, the biggest attractions are usually quicker application processing, fewer documentation requirements and promotional discounts on loan-related charges.
However, faster personal loan disbursal does not automatically mean cheaper borrowing. Interest rates, processing fees, loan tenure and the total repayment amount still determine whether an offer is suitable.
As festive loan campaigns continue into November 2026, borrowers should understand what lenders are offering and what to check before applying.
NBFCs account for 46% of new personal loan originations
India's personal loan market has recorded a notable increase in NBFC participation.
According to credit bureau CRIF data reported by Moneycontrol on November 2, NBFCs accounted for 46% of personal loan originations in Q1 FY27, up from 40.5% in the corresponding quarter of the previous financial year.
RBI data cited in the same report showed that retail loan growth accelerated to 22% year-on-year in August 2026, compared with 13.6% a year earlier.
Moneycontrol
NBFC share of personal loan originations
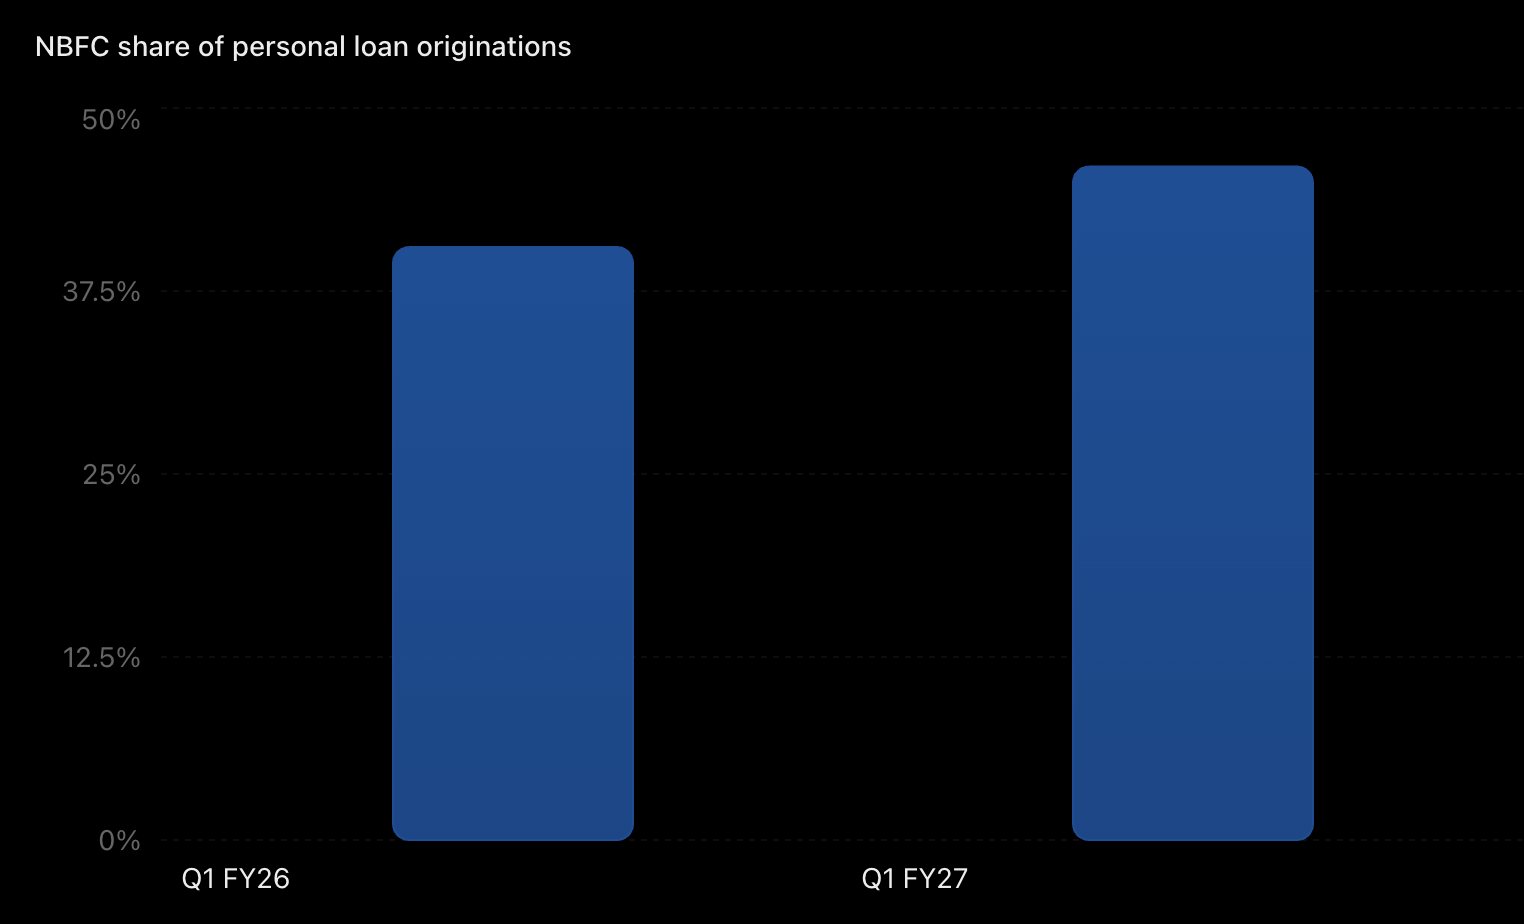
This increase reflects the growing role of NBFCs in originating personal loans. However, origination share measures the proportion of new loans, rather than the total value of outstanding personal loan debt.
For borrowers, the development means there are more opportunities to compare financing options across banks, NBFCs and digital lending platforms.
Latest festive personal loan offers from NBFCs in November 2026
Several lenders have introduced promotional campaigns to attract borrowers during the festive season. These include rewards, processing fee concessions, longer repayment tenures and special interest-rate offers.
|
Lender |
Festive personal loan offer |
|
HDB Financial Services |
Eligible customers can participate in a daily 1-gram gold coin reward campaign |
|
Poonawalla Fincorp |
Personal loans starting at 9.99% p.a., with promotional rewards |
|
Bajaj Finance |
Personal loans from ₹40,000 to ₹75 lakh, with tenures up to 108 months |
|
Moneyview and InCred |
Reported starting rates of 14% p.a. and up to 50% processing fee waivers for qualifying customers |
|
Axis Bank |
Collateral-free personal loans starting at 9.99% p.a., with processing fees starting at ₹999 |
Source: Moneycontrol, November 2, 2026. Axis Bank is included for comparison as a bank, rather than an NBFC. Offers are subject to lender eligibility and campaign conditions.
HDB Financial Services launched its Khushiyo ka Season campaign, with its gold coin promotion running from October 9 to November 8, 2026. The promotion applies to eligible customers across specified loan products.
Business Standard
Poonawalla Fincorp's Sapno Ka Celebration campaign combines personal loan offers with reward opportunities. Borrowers should check the campaign's terms rather than treating promotional prizes as guaranteed savings.
Similarly, a longer loan tenure can reduce the monthly EMI but increase the total interest paid. Customers should calculate both figures before choosing a repayment period.
Why are NBFCs focusing on faster personal loan disbursals?
Personal loans are unsecured credit products, meaning borrowers generally do not need to pledge property, gold or other assets as collateral.
For eligible applicants, the application process can be completed online. Digital lenders can use electronic identity verification, income assessment and automated underwriting systems to process applications.
Three developments are supporting the focus on faster personal loan services.
Higher festive spending: Households may require funds for purchases, celebrations, repairs or travel. Lenders respond to this seasonal demand with promotional campaigns.
Growing digital lending adoption: Customers increasingly expect to check eligibility, upload documents and review loan offers through smartphones.
Competition among lenders: NBFCs compete with traditional banks and other digital credit providers on processing time, repayment flexibility and borrowing costs.
Even where a lender advertises instant personal loan approval, additional checks may be required. Applicants should distinguish between receiving an initial eligibility decision, obtaining final loan approval and having the money credited to their bank account.
Are festive personal loans cheaper than regular personal loans?
They can be, but the savings depend on the offer.
A lower interest rate may reduce the total interest payable. A processing fee waiver reduces upfront borrowing costs, while a cashback reward may provide a benefit only after the borrower meets certain conditions.
An October 26 India Today report highlighted the need to compare total repayment costs and written terms rather than relying solely on festive loan advertisements.
India Today
Consider a borrower applying for a ₹50,000 personal loan with a 12-month repayment tenure.
|
Loan details |
Regular loan |
Festive offer |
|
Principal |
₹50,000 |
₹50,000 |
|
Interest rate |
14% p.a. |
14% p.a. |
|
Tenure |
12 months |
12 months |
|
Approximate EMI |
₹4,489 |
₹4,489 |
|
Processing fee |
2% |
Waived |
|
Fee including 18% GST |
₹1,180 |
₹0 |
|
Upfront savings |
— |
₹1,180 |
This example assumes a reducing-balance interest calculation and a full processing fee waiver. It is illustrative, not an advertised lender offer.
The monthly EMI remains unchanged because the interest rate and tenure are identical. The savings come from eliminating the processing fee.
A borrower should also check whether any fee is deducted before disbursal, as this affects the amount received.
How to apply for a personal loan online during the festive season
The online personal loan application process varies by lender, but applicants will generally encounter the following steps:
-
Compare personal loan options. Review loan amounts, interest rates, APR, fees and repayment periods across eligible lenders.
-
Check loan eligibility. Lenders may consider age, income, employment status, existing debt and credit history.
-
Submit the application. Enter the required personal and financial information through the lender's official website or app.
-
Complete verification. Provide identity, address, income or bank-account information where requested.
-
Review the loan documents. Read the Key Facts Statement, repayment schedule and loan agreement before accepting.
-
Wait for approval and disbursal. Once the lender completes its checks and approves the loan, the funds are disbursed according to the applicable terms.
Borrowers should avoid submitting unnecessary applications to multiple lenders within a short period, as repeated hard credit enquiries may affect their credit profile.
RBI digital lending rules: What borrowers should know
As digital personal loan applications become more common, understanding RBI lending requirements is essential.
The Reserve Bank of India (Digital Lending) Directions, 2025 establish borrower-protection requirements for regulated digital lending activities.
Littdb
These include:
-
Key Facts Statement: Borrowers must receive information about the APR, loan charges and relevant contractual terms.
-
Direct disbursal: Digital loan proceeds generally must go directly into the borrower's bank account, subject to specified exceptions.
-
Cooling-off period: Borrowers must have an option to exit a digital loan during an initial period of at least one day, subject to the prescribed principal, proportionate APR and any permitted disclosed fee.
-
Data privacy: Digital lending applications must follow applicable requirements for collecting and using customer information.
-
Grievance redressal: Regulated lenders must provide mechanisms for addressing borrower complaints.
Borrowers should verify the regulated lender behind a loan application, especially when using a third-party lending platform.
Pocketly: A digital personal loan option for smaller borrowing needs
Not every borrower requires a personal loan of several lakhs. Some may need a smaller amount to manage an urgent bill, essential purchase or temporary cash requirement.
For these situations, borrowers can explore Pocketly, a digital lending platform offering access to personal loan options ranging from ₹1,000 to ₹50,000, subject to eligibility and lending terms.
Customers can visit Pocketly's official website to understand the application process and review available borrowing options.
Before proceeding, applicants should verify the lending entity, applicable APR, processing fees, repayment tenure and total repayment obligation.
Borrowing only the amount required can help limit unnecessary interest expenses. A smaller principal, however, does not always mean a lower APR or lower proportionate fees.
Personal loan mistakes to avoid during festive offers
Promotional campaigns can encourage quick borrowing decisions. Borrowers should be particularly careful about the following mistakes.
Choosing a loan based only on the EMI: A smaller monthly payment may appear affordable, but extending the repayment tenure can increase the total interest cost.
Ignoring processing charges: A low advertised interest rate may be accompanied by upfront charges. Comparing APRs helps account for these costs.
Borrowing for promotional rewards: Gold coins, cashback and prize opportunities should not determine whether someone takes a loan.
Using unverified loan apps: Borrowers should confirm the identity of the regulated lender and avoid applications requesting unnecessary access to personal information.
Missing repayment dates: Late repayments can lead to additional charges and may adversely affect credit history.
The most suitable personal loan is one whose repayment schedule remains affordable after essential monthly expenses and existing debt payments.
Will festive personal loan offers continue after Diwali 2026?
Some campaigns are scheduled to continue into November, but their closing dates vary.
HDB Financial Services' reported gold coin campaign runs until November 8, 2026. Other lenders may revise their offers or discontinue benefits once their promotional periods end.
Borrowers should confirm the latest terms on official lender websites before applying. A campaign that was available when an article was published may no longer be open when a customer submits an application.
What should personal loan borrowers do next?
The increase in NBFC personal loan originations and the latest festive lending campaigns provide borrowers with additional options to compare.
For customers who already need financing, a processing fee waiver or a competitive interest rate could reduce borrowing costs. However, the benefit should be calculated against the entire repayment obligation.
Before accepting an offer, compare the APR, check the lender's regulatory status, read the Key Facts Statement and calculate the total amount payable.
For smaller loan requirements, platforms such as Pocketly can be considered alongside other lending options, provided the terms suit the borrower's financial circumstances.
Frequently asked questions
1. Are NBFCs speeding up personal loan disbursals in 2026?
NBFCs are promoting faster digital loan processing and pre-approved offers during the festive season. However, actual disbursal times depend on the lender, application details, credit assessment and verification requirements.
2. Which NBFCs are offering festive personal loan benefits?
HDB Financial Services, Poonawalla Fincorp, Bajaj Finance, Moneyview and InCred are among the lenders with reported festive personal loan campaigns in 2026.
3. Can I get a ₹10,000 instant personal loan online?
Eligible applicants can apply for small personal loans online through digital lending platforms. Pocketly offers loan options within the ₹1,000–₹50,000 range. Approval, disbursal time and charges depend on the applicable lender's assessment.
4. Do festive personal loans have zero processing fees?
Certain festive campaigns provide full or partial processing fee waivers to eligible borrowers. Customers should confirm whether other fees apply and compare the APR before accepting an offer.
5. Does a good credit score help with personal loan approval?
A good credit score may improve eligibility and help borrowers qualify for more competitive loan terms. However, lenders also consider income, existing repayment obligations and other underwriting criteria.
6. Is an NBFC personal loan safe?
Borrowing from an RBI-regulated NBFC can provide regulatory protections. Customers should verify the lender, review the loan documents and avoid unauthorised loan applications or requests for advance payments to personal accounts.
Primary news source: Moneycontrol — NBFCs accelerate personal loan disbursements, November 2, 2026.