

Need ₹4,000 Rupees Urgently? Apply for a ₹4,000 Loan Online
If you need ₹4,000 rupees urgently, you can check your eligibility for a small personal loan through Pocketly. Eligible borrowers can complete the required details and KYC online and check whether ₹4,000 is available based on their profile.
Pocketly offers personal loans from ₹1,000 to ₹50,000 for eligible borrowers, so a ₹4,000 loan may be available depending on eligibility and verification.
Before accepting a loan, check the APR, interest rate, processing fee, repayment period and total repayment amount mentioned in your Key Fact Statement (KFS).
₹4,000 Loan at a Glance
|
Detail |
Information |
|
Loan requirement |
₹4,000 |
|
Pocketly loan range |
₹1,000–₹50,000 |
|
Application |
Online |
|
Minimum age |
18 years |
|
KYC |
Required |
|
Collateral |
Not required |
|
CIBIL score |
Not required to apply |
|
Loan availability |
Subject to eligibility |
|
Disbursal |
Bank account after approval |
|
Repayment |
Based on applicable loan offer |
I Need ₹4,000 Rupees Urgently: What Can I Do?
If you need ₹4,000 urgently for a short-term personal expense, you can check whether you are eligible for a Pocketly personal loan. The amount available depends on your profile, verification and applicable lending criteria.
Before borrowing, check the total cost and make sure you can manage the repayment by the applicable due date.
What Is a ₹4,000 Personal Loan?
A ₹4,000 personal loan is a small unsecured loan that may be used for eligible personal expenses. Since it is unsecured, eligible borrowers do not need to pledge property, gold or another asset as collateral.
Pocketly offers personal loans starting from ₹1,000, so ₹4,000 may be available depending on your eligibility.
Can I Get a ₹4,000 Loan Through the Pocketly App?
Eligible borrowers can check whether a ₹4,000 personal loan is available through Pocketly. The application and applicable KYC process can be completed digitally.
The amount offered and approval depend on eligibility and successful verification.
Purpose of Applying for a Personal Loan

Whether it’s covering an emergency expense or simply managing your finances better, these loans offer flexibility and ease of access.
Here’s why you might consider applying for a personal loan.
- Handling Emergencies – Medical bills, urgent home repairs, or unexpected travel expenses can arise at any time. A personal loan can help cover these costs without disrupting your savings.
- Bridging Cash Flow Gaps – If your salary is delayed or you're short on funds before payday, a loan can help manage essential expenses like rent, groceries, or utility bills.
- Debt Consolidation – Managing multiple credit card bills or high-interest loans? A personal loan can simplify repayments by merging debts into a single, lower-interest loan.
- Making Big or Necessary Purchases – Whether it's buying a laptop for work, investing in an online course, or covering wedding expenses, a personal loan provides financial support when needed.
- Avoiding Late Payment Penalties – Missing credit card payments, EMIs, or rent can lead to hefty penalties and impact your credit score. Getting a personal loan will help you stay on track with payments.
No matter the purpose, a personal loan offers financial flexibility and helps you to manage your expenses without unnecessary stress.
Can I Get an Instant ₹4,000 Loan Online?
You can check your eligibility for a ₹4,000 loan online through Pocketly. If you receive an offer, review the applicable APR, fees, repayment period and total repayment amount before accepting it.
Approval and disbursal depend on successful eligibility checks and verification, so an instant ₹4,000 loan should not be treated as guaranteed.
I Need ₹4,000 Rupees Urgently as a Student: Can I Apply?
Students aged 18 or above can check whether they meet Pocketly's applicable eligibility requirements. A ₹4,000 loan may be available depending on the applicant's profile and verification.
Student status alone does not guarantee approval or a specific loan amount.
Key Features and Benefits of a Personal Loan
A personal loan is one of the easiest ways to get financial support when you need it the most. Whether you're facing an emergency or planning a big purchase, this type of loan offers flexibility without requiring you to pledge any assets.
Let’s learn more about the features and benefits so you can see why it might be the right choice for you.
Key Features:

- No Collateral Required: Unlike home or car loans, a personal loan is unsecured, meaning you don’t have to risk your property, jewelry, or savings to get approved.
- Loan Amount: You can borrow as little as ₹4,000 for urgent expenses or go up to several lakhs for bigger financial needs, depending on your eligibility.
- Fast Disbursal Process: Need money urgently? Many lenders approve and transfer funds to your bank account within 24 hours, sometimes even within minutes.
- Fixed Monthly EMIs: Once you take the loan, you’ll repay it in fixed monthly instalments. This makes budgeting easier since you’ll know exactly how much you owe each month.
- Minimal Documentation Required: No need for excessive paperwork—just provide your basic KYC documents (Aadhaar, PAN), bank statements, and income proof (if required), and you're good to go.
- Easy Online Application: Skip the long queues and apply from the comfort of your home using your phone or laptop. Most lenders offer a simple, fully digital application process.
Key Benefits:
- Quick Access to Funds in Emergencies: Whether it's an unexpected medical bill, urgent home repair, or a sudden travel requirement, a personal loan ensures you get the money when you need it the most.
- Flexible Repayment Tenure: You can definitely choose a repayment period that suits your budget—whether it’s a few months or a couple of years—to help you manage your finances smoothly.
- Opportunity to Improve Your Credit Score: Suppose you have a low credit score, taking a personal loan and repaying it on time can help increase your credit rating, making it easier to get larger loans in the future.
- Use the Money However You Want: Unlike other loans tied to specific purchases (like car or home loans), a personal loan gives you complete freedom—you can use it for anything from medical expenses to education, travel, or even debt consolidation.
A personal loan is a quick, flexible, and convenient way to handle financial needs without unnecessary complications. If you’re in need of instant cash, this could be the best option for you!
Can I Get a ₹4,000 Loan Without Salary?
A regular salary is not the only possible source of income, but applicants still need to meet Pocketly's applicable eligibility requirements.
If you do not receive a regular salary, check whether your income profile meets the applicable requirements before applying. Approval is subject to eligibility and verification.
To check your eligibility for a Pocketly loan, you should meet the applicable requirements, which may include:
-
Being at least 18 years old
-
Meeting applicable income requirements
-
Having valid KYC information
-
Having an active bank account
-
Providing accurate personal and contact details
-
Completing the required verification
Meeting the basic requirements does not guarantee approval or a ₹4,000 loan amount.
Documents Required for a ₹4,000 Loan
Depending on the applicable verification requirements, you may need:
-
PAN details
-
Aadhaar-based address verification
-
Bank account information
-
Verified contact details
-
Video KYC
-
Other applicable information
The process can be digital, but a completely document-free loan should not be assumed.
Personal Loan Interest Rate for a ₹4000 Loan
Interest rates play a significant role when applying for a ₹4000 personal loan, as they directly impact your repayment amount. Generally, interest rates on personal loans range between 10% and 36% per annum, depending on factors like your credit score, salary, and loan tenure.
For short-term or personal loans digital lending platforms like Pocketly offer competitive interest rates, starting as low as 2% per month. However, rates may vary based on your creditworthiness and repayment history.
Here’s a breakdown of Pocketly’s interest rates, fees, and penalties:
| Category | Details |
|---|---|
| Interest Rate | Starting from 2% per month |
| Loan Processing Fees | 1% to 8% of the approved loan amount |
| Overdue EMI Charges | A penalty applies for missed EMI payments |
| Bounced NACH Charges | A small fee is charged for bounced payments |
Understanding these charges ensures you're aware of your financial obligations before taking out a loan.
Can I Get a ₹4,000 Loan With Bad Credit?
Pocketly states that a CIBIL score is not required to apply. This means eligible borrowers can check their loan options even if they do not have a strong or established credit profile.
However, approval is not guaranteed and remains subject to applicable eligibility, verification and lending criteria.
How to Calculate EMI for a ₹4000 Loan
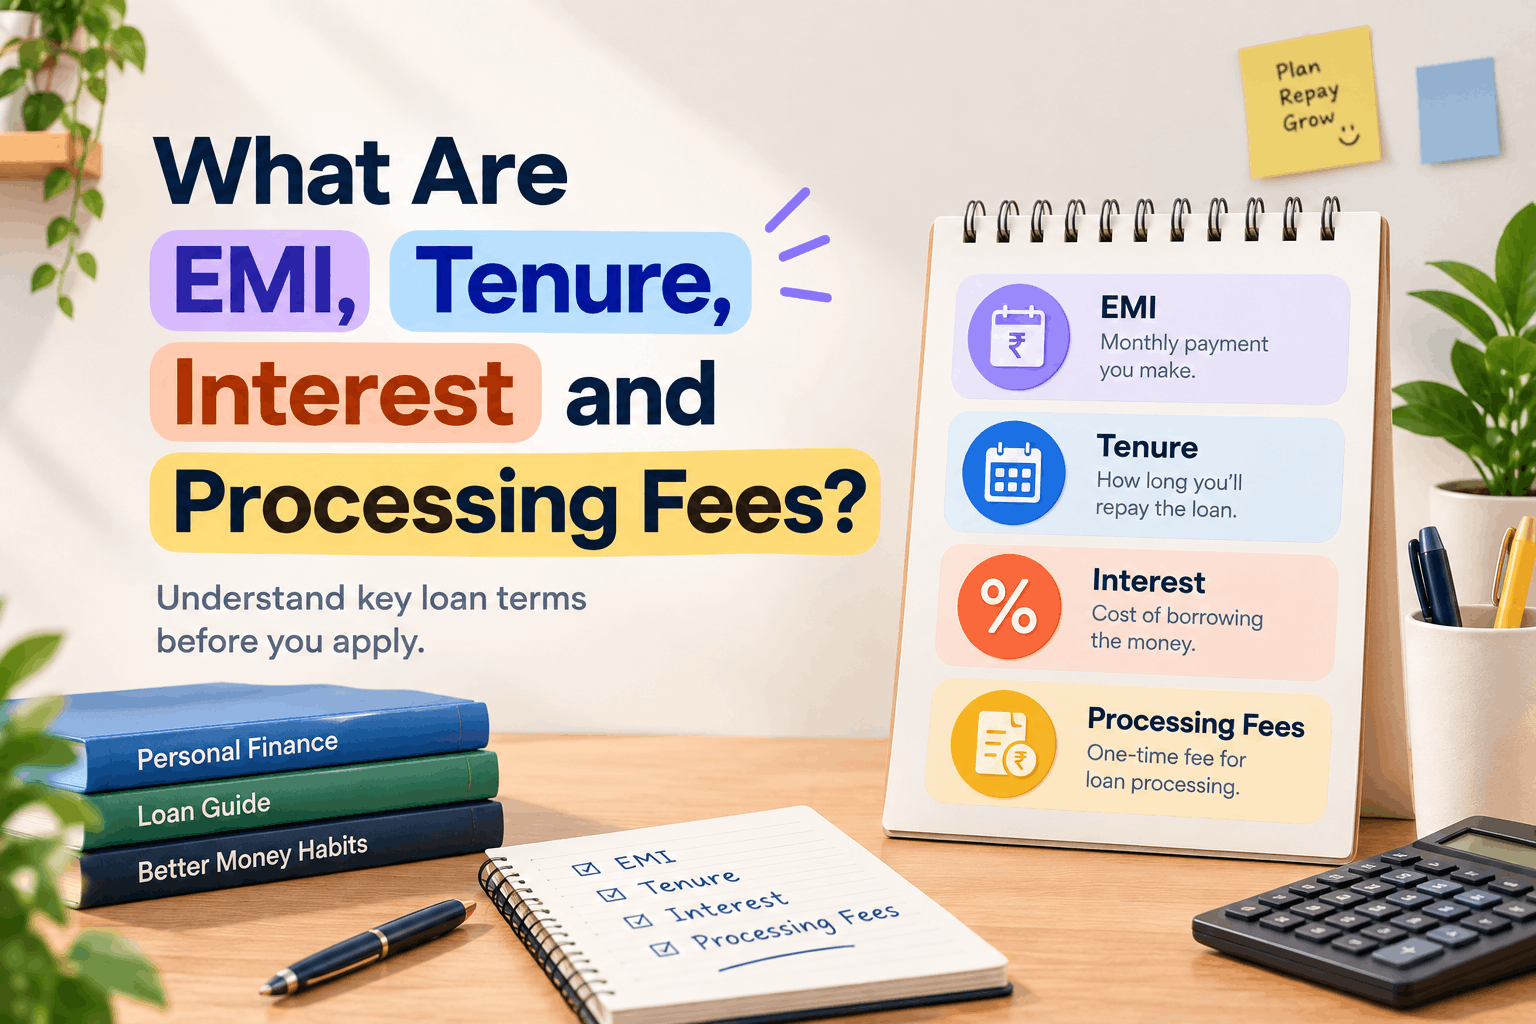
Calculating your Equated Monthly Installment (EMI) is essential when taking a ₹4000 personal loan, as it helps you understand how much you’ll repay each month. EMI ensures you manage your budget efficiently without any surprises.
Key Factors Influencing EMI
- Loan Amount (P): The total money you borrow (₹4000 in this case).
- Interest Rate (R): The rate charged on your loan. A higher rate leads to a higher EMI.
- Loan Tenure (N): The repayment period, typically ranging from 3 months to 12 months. A longer tenure means smaller EMIs but a higher total interest payout.
EMI Calculation Formula
The standard EMI (Equated Monthly Installment) formula can be rewritten in a more readable format as:
EMI = (P × r × (1 + r)^N) / ((1 + r)^N - 1)
Where:
- P = Loan amount
- R = Annual interest rate divided by 12 (converted to decimal)
- N = Number of months in the loan tenure
What Is the EMI for a ₹4,000 Loan?
There is no single EMI for every ₹4,000 loan. The repayment amount depends on the applicable interest rate, fees and repayment period.
Use the Pocketly Personal Loan EMI Calculator to estimate your repayment and check your KFS for the actual amount payable.
Use Online EMI Calculators for Quick Estimates
If this formula seems complicated, online EMI calculators can instantly give you the monthly repayment amount. Simply enter your loan amount, interest rate, and tenure, and get an instant EMI estimate.
A ₹4000 personal loan can be a lifesaver during emergencies, even if you have a low salary or poor credit score. Just be sure to compare interest rates, check processing fees, and calculate your EMI before applying.
For more information about interest rates, read our guide on Applying for Short-Term Loans Online at Lowest Interest Rates.
Considerations for Low Salary and Credit Score
If you have a low salary or a poor credit score, securing a personal loan can be tricky. Lenders usually check your income stability and repayment history before approving your application. However, some financial institutions and digital lending platforms like Pocketly offer flexible options even if you don’t meet traditional eligibility criteria.
Here are some key factors to keep in mind before applying for a ₹4000 personal loan:
- Loan Amount Limitations – With a lower salary or poor credit score, lenders may approve only smaller loan amounts to minimise their risk.
- Higher Interest Rates – Since lenders consider low-income or bad-credit applicants as high-risk, they often charge higher interest rates compared to standard personal loans.
- Shorter Repayment Tenure – You may be required to repay the loan within a few months, rather than having the flexibility of a long-term loan.
- Co-Applicant or Guarantor May Help – Adding a co-applicant with a stable income can increase approval chances and may even help you secure a better interest rate.
- Income Proof Alternatives – If you don’t have salary slips, you can provide bank statements, utility bills, or alternative proof of income to show financial stability.
- Improve Credit Score Before Applying – Paying off outstanding debts, reducing credit card usage, and ensuring timely payments can boost your credit score and improve loan eligibility.
- Check Lender-Specific Requirements – Some lenders specialise in loans for low-income or bad-credit borrowers, so research and choose one that aligns with your financial situation.
Knowing these factors will help the loan application process more effectively and find a suitable lender without unnecessary rejections.
Why Consider Pocketly for a ₹4,000 Personal Loan?
Pocketly provides a digital personal-loan process for eligible young borrowers.
Key features include:
-
Loan amounts starting from ₹1,000
-
Minimum eligibility age of 18 years
-
Online application
-
Digital KYC
-
No collateral requirement
-
CIBIL score not required to apply
-
Direct bank transfer after approval
If you need ₹4,000, check your eligibility and review the applicable loan terms before deciding whether to borrow.
Check Your Loan Eligibility with Pocketly
Approval and the loan amount offered are subject to eligibility, verification and applicable lending criteria.
If you want to apply for a personal loan even with low credit Pocketly, check out our guide on Getting a Personal Loan with a Credit Score of 600.
Things to Keep in Mind When Applying for a ₹4000 Personal Loan

Whether you have a low salary or a low credit score, understanding these aspects might help you make an accurate decision and ensure smooth loan repayment.
Here are some important things to consider before applying:
- Loan Tenure Matters – A shorter tenure means higher EMIs but lower overall interest, while a longer tenure reduces EMIs but increases total interest paid. Choose wisely based on your repayment ability.
- Interest Rates Can Vary – Different lenders offer varying interest mostly depends upon on your income and credit score. Double-check for interest rates.
- Processing Fees and Charges – Many lenders charge processing fees ranging from 1% - 8% of the loan amount. Be sure to check for any hidden fees.
- Repayment Terms and Flexibility – Some lenders offer flexible repayment options, allowing part-payments or early closures without hefty penalties. Review these terms before finalising.
- Credit Score Impact – Even if you qualify for a loan with a low credit score, missing EMIs can further damage your credit rating and make future borrowing difficult.
- Avoid Overborrowing – Even if you qualify for a higher amount, borrow only what you need to prevent unnecessary debt and financial strain.
- Check Lender Credibility – Not all online lending platforms are trustworthy. Ensure you apply through a registered and RBI-compliant lender to avoid scams.
By keeping these factors in mind, you can make a well-informed borrowing decision while avoiding common financial risks.
Can a ₹4,000 Loan Help With an Emergency Expense?
A ₹4,000 personal loan may help with a small unexpected expense such as essential travel, medicines, utility payments or another eligible short-term need.
Before borrowing for an emergency, check the total repayment amount and whether you can comfortably repay the loan on time.
Conclusion
Getting a ₹4000 personal loan online, even with a low salary or credit score, isn’t as difficult as it may seem. With the right lender, minimal paperwork, and a straightforward application process, you can secure funds exactly when you need them. Whether it’s for an urgent bill, a last-minute purchase, or just to get through the month, a small loan can be a lifesaver—as long as you borrow responsibly!
Just remember: always check the terms, compare lenders, and have a solid repayment plan in place. Loans are meant to help, not add stress—so borrow smart and stay in control of your finances!
Need Quick Cash? Get Instant Funds with Pocketly!
Why wait in long queues or deal with endless paperwork? With Pocketly, you can apply for a personal loan in minutes and get money directly into your bank account. No hidden fees, no lengthy approvals—just fast, easy, and secure lending when you need it the most.
- Seamless App Experience – Pocketly’s simple and intuitive interface ensures a smooth loan application process with minimal effort.
- Instant Fund Transfers – Get approved and receive your loan within minutes, which is perfect for urgent expenses.
- Flexible Repayment Plans – Choose a different repayment schedule that fits your budget, making repayments stress-free.
- 100% Transparency – No hidden charges—know exactly what you’re paying upfront.
Download the Pocketly App now and get your ₹4000 loan instantly!
FAQs
Can I get a loan from Pocketly if I have a low credit score?
Yes, Pocketly considers multiple factors beyond your credit score, making it easier to get a loan even if your credit history isn't perfect.
How quickly can I get a loan with Pocketly?
Pocketly offers instant approvals, and once your loan is approved, the funds will be deposited into your bank account within minutes.
What are the repayment options available with Pocketly?
Pocketly provides flexible repayment plans that allow you to choose an EMI structure that fits your budget, ensuring a smooth borrowing experience.
How do I apply for loan restructuring?
You must contact your lender, provide proof of financial distress, and submit a formal request. The lender will definitely review your application and offer restructuring options based on your eligibility.
How much can I borrow from Pocketly?
You can borrow anywhere from ₹1000 to ₹25,000, depending on your eligibility and needs. Whether it's a small expense or a larger emergency, we’ve got you covered!
How quickly will my loan be approved?
The approval process is instant! After completing your application and submitting the required details, you’ll receive approval within minutes.
What documents do I need to apply for a loan?
Pocketly requires minimal documentation. You’ll need to provide basic KYC information like your PAN card, Aadhaar card, and bank statement, all of which can be uploaded digitally.