

What Is a Line of Credit? Line of Credit vs Credit Card
A line of credit (LOC) is a flexible credit facility that lets you borrow money up to an approved limit when you need it. Instead of receiving the entire amount at once, you can withdraw only the amount you require and generally pay interest on the amount used. As you repay the borrowed amount, the available credit may become accessible again, depending on the terms of the facility.
A line of credit and a credit card are both forms of credit, but they differ in how you access funds, repayment structures, interest charges and typical use cases. This guide explains what a line of credit is, how it works, and the difference between a line of credit and a credit card.
Quick Answer: Line of Credit Meaning: A line of credit is a borrowing facility that provides access to funds up to an approved credit limit. Borrowers can draw funds when required and, for revolving facilities, may borrow again after repayment, subject to the lender's terms.
What Is a Line of Credit?
A line of credit, also called a credit line or LOC, is a credit facility that allows an eligible borrower to access funds up to a predetermined limit.
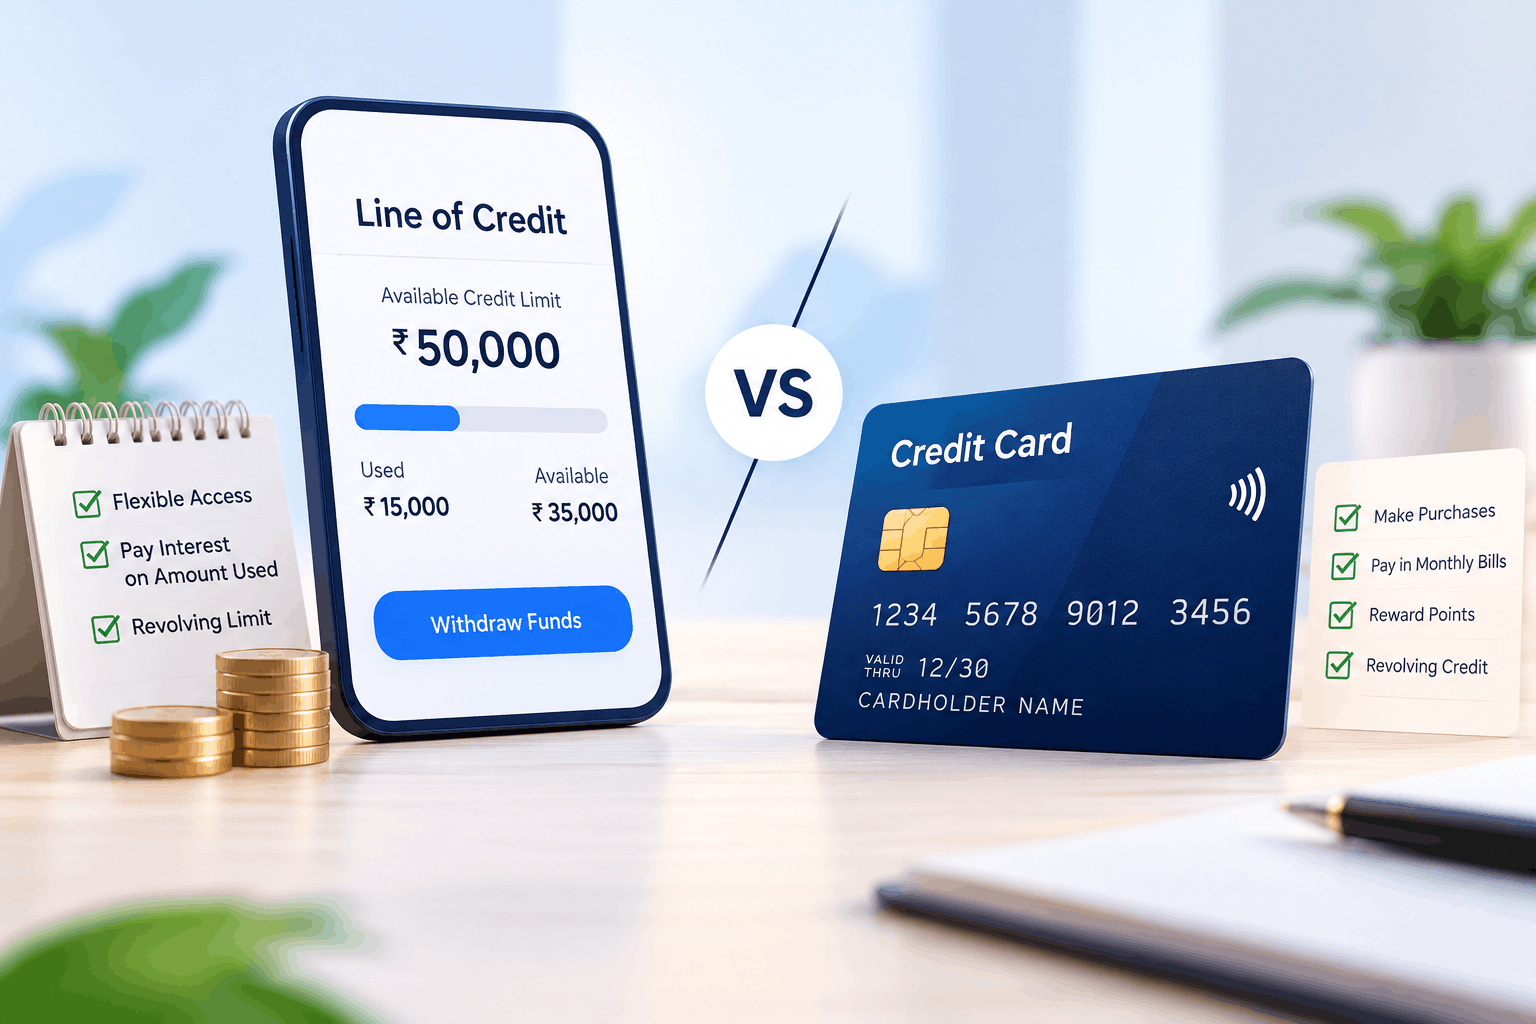
For example, suppose you have an approved credit line of ₹50,000. If you need ₹10,000, you can draw ₹10,000 rather than borrowing the entire ₹50,000. Subject to the lender's terms, interest or other applicable charges are generally based on the amount used.
As you repay the outstanding amount, the available credit may replenish, allowing you to borrow again within the approved limit.
How does a line of credit work?
A line of credit generally works like this:
-
A credit limit is approved: The lender determines the maximum amount available based on eligibility and underwriting.
-
You draw funds when required: You can use an amount within the available limit.
-
Charges apply according to the agreement: Interest and fees depend on the lender, product and amount used.
-
You repay the outstanding balance: Repayment requirements vary by facility.
-
Available credit may replenish: With a revolving LOC, repaid credit can generally become available again.
Example: Say you have a ₹20,000 credit line. You borrow ₹7,000 for an urgent laptop repair. After a month, you repay ₹3,000. Now, ₹16,000 of your credit limit is available again (₹20,000 - ₹4,000 balance).
Pros of a Line of Credit

- Flexible Usage: You don’t have to borrow the full limit at once. It’s a pay-as-you-need option, useful for those with variable expenses, like freelancers, students, or self-employed individuals.
- Interest Savings: Unlike traditional loans, where you pay interest on the entire sanctioned amount, here, you pay interest only on the portion used, helping reduce borrowing costs.
- Reusable Credit Limit: The revolving nature means you can reuse your limit repeatedly without going through another application. Once you repay, that portion of the credit becomes instantly available again.
- Great for Unpredictable Needs: Perfect for irregular expenses, think medical emergencies, sudden travel, course fees, utility bills, or small business purchases that don’t have a fixed amount upfront.
Cons of a Line of Credit

- Can Lead to Overspending: Since funds are always available and easily accessible, there’s a temptation to borrow unnecessarily. It requires financial discipline to avoid overusing it.
- Interest Rates May Vary: Most lines of credit, especially unsecured ones, come with variable interest rates, which means your cost of borrowing can increase if rates rise over time.
- Eligibility Can Be Tight: You may need a good credit score or a stable financial background to qualify, especially with banks or NBFCs. However, platforms like Pocketly ease this by offering small-ticket credit to those just starting to build their credit profile.
- Not Always Instant with Traditional Lenders: Banks and traditional institutions may have slower approval processes, with paperwork and verifications involved. Fintech apps are faster, but your access still depends on profile assessment.
Need flexible credit on your terms? Pocketly gives you instant access to a revolving line of credit, and you can borrow only what you need, when you need it.
Now that you know how a line of credit functions, let’s look at the more familiar option: credit cards. But beyond swiping at checkout, there's more to how credit cards work and why people rely on them so often.
Also Read: Understanding Line of Credit: Definition, Types, and How it Works
What Is a Credit Card?
A credit card is a pre-approved borrowing tool that lets you make purchases or withdraw cash up to a fixed limit. It’s like having a wallet that’s funded by the bank, temporarily. You can spend up to your limit, but you’re expected to pay it back, either in full or in parts.
Most credit cards also come with billing cycles, due dates, and late fees if not managed properly. They're meant more for regular spending, but they can also come in handy during short financial gaps.
How a Credit Card Works
A credit card offers a pre-approved spending limit; you can use it for shopping, bill payments, subscriptions, or even emergencies. But unlike debit cards, you're not spending your own money upfront; you're borrowing from the bank, with the agreement to repay within a specific time.
Here’s how it works in practical terms:
- You Get a Credit Limit: Let’s say your card is approved with a ₹50,000 limit. That’s the total amount you can spend using the card.
- You use the Card for Transactions: You can swipe or tap the card for purchases online or offline. Some cards also allow cash withdrawals, but this comes with instant interest and additional charges, so it's best reserved for urgent use only.
- Billing Cycle and Due Date: Your spending is tracked during a billing cycle (usually 30 days), after which you get a bill. You’re given an interest-free grace period to pay, usually 15–20 more days.
- Full Payment = No Interest: If you pay the entire billed amount by the due date, you pay zero interest; the card essentially becomes a free short-term loan.
- Partial Payment = Interest Applies: If you pay only the minimum due or any amount less than the full bill, interest starts compounding on the unpaid balance, often at rates as high as 36%-42% annually.
Example: You spend ₹8,000 on groceries, travel, and a phone bill. Your billing date is the 10th of each month, and the due date is the 30th.
If you pay ₹8,000 by the 30th, you pay no extra charges.
If you pay only ₹1,000, the remaining ₹7,000 begins accruing interest from the billing date, not the due date.
Pros of a Credit Card

- Widely Accepted for Everyday Use: Credit cards are accepted across e-commerce platforms, retail outlets, and even for utilities and subscriptions. They’re especially helpful when cash or UPI isn't an option.
- Interest-Free Period: Most credit cards offer 30–50 days of no-cost borrowing, provided you fully clear your dues. It’s a practical tool for managing cash flow if used responsibly.
- Rewards & Perks: Depending on your card, you may earn cashback, reward points, travel miles, or discounts on fuel, food delivery, OTT subscriptions, and more. Ideal for those who use cards regularly and repay on time.
- Build Credit History: If you make on-time payments and avoid carrying large balances, a credit card helps you establish or strengthen your credit score, which is essential for future loans or big-ticket borrowing.
- Handy During Emergencies: Whether it’s an unexpected medical expense, urgent booking, or last-minute travel, credit cards offer a quick solution when you don’t have liquid funds.
Cons of a Credit Card

- High Interest Rates on Outstanding Balances: If you carry over unpaid amounts, you may pay 3% or more per month, which can add up fast. Missing even one payment can lead to compounding debt.
- Extra Charges for Delays or Cash Use: Late fees, over-limit penalties, and cash withdrawal charges can significantly inflate your dues, making it costlier than intended.
- Easy to Overspend: Since you're not using your own money upfront, it's easy to swipe without thinking. Many users fall into the trap of minimum payments and accumulate debt quickly.
- Negative Impact on Credit Score: Frequent delays, overutilizing your credit limit, or defaulting can hurt your creditworthiness, affecting your chances for future loans, credit cards, or even job applications in financial roles.
While both give you access to borrowed money, how you use them, pay them back, and what you get out of them can look pretty different. Here's a side-by-side look at where they stand apart.
Line of Credit vs Credit Card: What's the Difference?
The main difference between a line of credit and a credit card is how the available credit is accessed and typically used. A line of credit can provide access to funds within an approved limit, while a credit card is primarily designed to make card-based purchases up to a credit limit. Interest, fees, repayment terms and withdrawal rules depend on the specific product and lender.
| Criteria | Line of Credit | Credit Card |
|---|---|---|
| Accessing and Using Funds | Borrow funds as needed, directly into your account or through linked platforms. | Use the card to pay directly at stores or online; limited to the card’s interface. |
| Interest Rates and Charges | Typically lower interest rates, but interest starts accruing as soon as funds are drawn. | Higher interest rates, but you get an interest-free period if the full amount is paid on time. |
| Repayment Terms | Flexible repayment, can pay back in full or part, depending on the agreement. | Monthly billing cycle with minimum payment required; interest on unpaid balance. |
| Rewards and Benefits | Generally, no rewards or perks; purely a borrowing tool. | Offers rewards like cashback, points, or discounts based on spending. |
| Credit Limit Structure | It can be higher and more dynamic, based on income and creditworthiness. | Fixed limit set by the bank, often lower than a line of credit. |
| Purpose and Use Cases | Better suited for planned or larger expenses like home repairs, education, etc. | Ideal for frequent, small-scale purchases like groceries, fuel, or subscriptions. |
| Cash Withdrawals | No additional fees; treated the same as fund transfers. | Usually comes with high fees and interest from the day of withdrawal. |
| Application and Approval | May involve more documentation and approval time. | Usually quicker approval, especially for salaried individuals. |
| Financial Discipline Required | Less risk of impulsive spending as funds are accessed consciously. | High temptation to overspend due to the ease of swipe-and-go. |
There’s no one-size-fits-all answer; what works best depends on how and why you need the funds. Here’s how to decide which option aligns better with your financial habits and immediate needs.
Also Read: Personal Loan EMI vs Credit Card EMI: The Differences Explained
When should you choose a line of credit vs. a credit card?
Choosing between the two really comes down to what you need the money for, how soon you can repay it, and how you plan to use the credit.
Go for a Line of Credit if:
- You need funds for planned or larger expenses.
- Think home repairs, tuition fees, or a one-time medical bill. A line of credit gives you flexibility without the high interest of a credit card.
- You prefer borrowing only what’s needed.
- Unlike a lump-sum loan, a credit line lets you withdraw smaller amounts as required and pay interest only on what you use.
- You’re expecting irregular or variable expenses.
- It’s a helpful buffer when your income fluctuates (like freelancers or seasonal earners).
- You don’t mind a bit more paperwork to get better terms.
- Approval might take longer, but you often get lower interest rates and higher limits.
Opt for a Credit Card if:
- You need something quick and simple.
- Applying for and using a credit card is fast and straightforward, with instant access to funds once approved.
- You regularly shop or pay bills online or in-store.
- Credit cards are built for frequent transactions and come with ease-of-use perks like one-tap payments.
- You’re confident about paying back in full every month.
- Doing that means you enjoy an interest-free period, essentially borrowing at zero cost.
- You like getting rewards or cashback.
- Frequent spending can earn you points, discounts, and other loyalty perks, something a line of credit won’t offer.
Choosing between the two isn’t just about borrowing. It also affects your long-term financial health. Here's how both credit options play a role in building and maintaining your credit score.
Impact on Credit Score and Management
How you manage credit, not just how much you borrow, plays a huge role in shaping your credit score. Both credit cards and lines of credit impact it, but in slightly different ways. Here's what to keep in mind:
- Credit Utilization: Credit scores favor low usage. Whether it’s a line of credit or a credit card, borrowing close to your maximum limit can bring your score down. Using only a portion of what's available helps maintain a healthy utilization ratio.
- Repayment Discipline: Timely repayments are non-negotiable. Both products report to credit bureaus, so one missed due date can drag your score down. On the flip side, consistently paying your dues, even minimum amounts, can improve your score over time.
- Account Activity and Longevity: Having a long-standing, active account (with either credit type) boosts your credit history. But if the account remains inactive or is closed too soon, it might not add much weight. It’s not just about having credit, it’s about showing you can manage it over time.
- Credit Mix: Lenders like seeing that you can handle different types of credit. Using a line of credit and a credit card responsibly shows variety in your credit profile, which can work slightly in your favor.
- Potential for Overuse: Since both offer revolving access to funds, there’s a risk of borrowing more than necessary. But a line of credit often encourages planned use, while credit cards can be more prone to impulse spending. Either way, keeping intentional borrowing helps you stay in control and stabilize your credit score.
Understanding how your credit behavior shapes your financial credibility is essential, but just as important is choosing credit tools that don’t work against you while you try to build it. That’s where options like Pocketly come in, designed to offer support without adding unnecessary complexity.
Pocketly: A Smarter Option for Real Financial Needs
Sure, credit cards and lines of credit give you access to borrowed money, but they also come with their own sets of conditions, limitations, and, at times, unexpected costs. And if you’re looking for something that adapts to your pace, feels less restrictive, and doesn’t require you to jump through hoops just to get started, Pocketly steps in as a far more practical solution.
With Pocketly, you’re not just getting credit, you’re getting short-term, need-based financial support that understands how real-world expenses work, especially when you're in between paychecks or managing irregular income. It's simple to apply, transparent in how it's structured, and created to suit a wider range of financial profiles, whether you're salaried, self-employed, or somewhere in between.
Why Pocketly Could Be a Better Fit
- Quick Access Without the Complexity: Unlike credit cards that often come with hidden terms that demand lengthy approvals, Pocketly lets you apply through a seamless app experience and get funds disbursed swiftly.
- Minimal Processing Fees: A small, transparent processing fee ranging from 1% to 8%, depending on your loan amount and tenure, is applied upfront, with no hidden deductions or last-minute surprises.
- Designed for Salaried and Self-Employed Individuals: Pocketly offers personal loans tailored to both salaried users and self-employed professionals, recognizing different income flows, credit needs, and repayment preferences.
- Flexible Loan Amounts: Whether it’s ₹1,000 or ₹25,000, Pocketly allows you to borrow the amount that matches your immediate need, with no pressure to commit to more than you require.
- Transparent Charges: You know upfront what you’ll repay. No confusing interest structures, no surprise penalties, just a straightforward cost.
- Pay Back on Your Terms: Choose your repayment date and EMI plan. Whether it’s next week or next month, Pocketly puts control back in your hands.
- Perfect for Short-Term Gaps: Need a cushion until your salary arrives? Have a medical bill or urgent travel? Pocketly fills those temporary financial voids without the baggage of long-term credit commitments.
- Improves Credit Health: On-time repayments through Pocketly are reported to credit bureaus, helping you build or improve your credit profile without risking massive debt buildup.
Short-term expenses don’t always come with a warning, and sometimes your regular income doesn’t align with your immediate needs. Pocketly smooths over timing mismatches in cash flow with credit that’s fast, transparent, and built to adjust to real-life situations. It’s not just about borrowing, it’s about staying financially steady, even when things shift.
Conclusion
Instead of asking which is better, a line of credit or a credit card, it might be more useful to rethink the way you borrow in the first place. Traditional credit products were built around how banks wanted to lend, not how people actually spend. That’s why they often feel rigid, complex, or misaligned with real-life financial behaviour.
Before choosing any option, ask yourself one simple question: Is this product solving my problem, or am I adjusting my behavior just to make it work? If it’s the latter, that’s a sign to look for alternatives that fit your lifestyle, not the other way around.
Credit should simplify decisions, not complicate them. Whether it’s through more predictable repayments, quicker access to funds, or borrowing terms that don’t box you in, there’s value in exploring new-age solutions that feel more personal, more intuitive, and frankly, more human.
If your goal is to borrow smarter, not more, then it’s time to rethink the tools you rely on. Pocketly isn’t just another credit option; it’s a step toward managing money on your terms, with clarity and control.
FAQs
What is a line of credit?
A line of credit is a credit facility that allows you to borrow up to an approved limit and access funds when required, subject to the lender's terms.
What is a credit line?
A credit line is another term commonly used for a line of credit. It represents the maximum credit made available under the facility.
How does a line of credit work?
You receive an approved limit and can draw funds within that limit. Depending on the product, repaying the borrowed amount can restore your available credit.
What is the difference between a line of credit and a credit card?
Both can provide revolving credit, but their access methods, fees, interest structures, repayment requirements and typical uses can differ.
Is a line of credit the same as a personal loan?
No. A personal loan generally provides a specified loan amount with an agreed repayment schedule, while a revolving line of credit can allow repeated borrowing within an available limit.