

NBFC Personal Loans in India Growth Hits 30%: UBS Explains the Rise
Personal loans in India are gathering pace, with lending by non-banking financial companies (NBFCs) growing around 30% year-on-year in August 2026, according to UBS analysis reported by Moneycontrol on September 23. For borrowers, the development points to expanding lending activity, while individual approval and pricing still depend on the lender's assessment.
The figure comes from UBS analysis citing CRIF credit bureau data. It should not be described as an RBI announcement or a new lending rule. The original UBS research note was not publicly available in the sources accessed for this article; the figures below are attributed to published reporting.
What happened?
UBS analysis, reported on September 23, put NBFC personal loan growth at about 30% year-on-year in August 2026, up from 16% in March 2025. It also put bank personal loan growth at 9%. These figures describe lending trends and do not change an existing borrower's repayment agreement.
What is driving personal loan growth in India?
According to ANI's coverage of the UBS analysis, improving loan performance, available liquidity and greater willingness among lenders to extend credit support the recovery. UBS expects personal loans to lead the next phase of unsecured credit expansion. That expectation is an analyst outlook, rather than a confirmed future outcome.
Unsecured loans in India allow eligible borrowers to access funds without pledging an asset such as gold or property. Lenders still assess whether applicants can repay. A digital application can simplify submission, but it does not remove the need for an affordability assessment.
The personal loan market in India also contains different loan sizes and borrower groups. Sector growth cannot establish that every lender, income group or small-loan category is expanding at the same speed.
How much has NBFC lending accelerated?
The reported growth rate increased by 14 percentage points between March 2025 and August 2026. A change in the growth rate should be distinguished from the increase in the loan balance itself.
|
Measure |
Earlier reported figure |
August 2026 figure |
|
NBFC personal loan growth, year-on-year |
16% in March 2025 |
About 30% |
|
Bank personal loan growth, year-on-year |
Not included in this comparison |
About 9% |
Source: Moneycontrol's September 23 report on UBS analysis citing CRIF data. These figures should not be relabelled as application growth, approval rates or Pocketly's own growth.
Personal loan demand in India cannot be measured from this headline alone. Lending growth also reflects lenders' willingness to approve credit and the size of loans issued. It does not tell readers how many additional people applied or how many were declined.
What this means for borrowers
Greater lending activity may mean more offers to assess. It does not establish that a particular offer is affordable or suitable for your circumstances.
For salaried applicants, compare the repayment date with the date your salary usually arrives. A loan due before payday can create avoidable cash pressure even when the instalment looks manageable.
For freelancers and self-employed applicants, assess repayment using income that has already been received or can reasonably be relied on. An unpaid client invoice is an uncertain source for a fixed repayment obligation.
|
Borrower question |
Practical implication |
|
Will I qualify more easily? |
Approval still depends on the lender's eligibility and credit assessment. |
|
Will my interest rate fall? |
The growth figure provides no assurance of a lower individual rate. |
|
Should I accept a larger limit? |
Base the amount on the expense and repayment capacity. |
|
Does my existing EMI change? |
This report itself creates no change to the loan agreement. |
|
Can I skip document checks? |
Follow the lender's stated verification requirements. |
Will personal loan interest rates change?
The report does not establish a rate reduction for personal loans. Borrowers need a specific offer to assess their own borrowing cost.
When comparing an instant personal loan with another option, use the same requested amount and repayment period. A smaller instalment may simply reflect a longer tenure. Compare the amount credited to your account, the annual percentage rate (APR), scheduled repayments and any applicable charges.
The Reserve Bank of India's April 15, 2024 Key Facts Statement circular defines APR as the annual cost of credit including interest and associated charges. It sets out standardised disclosures for retail and MSME term loans. The Key Facts Statement, or KFS, is therefore an essential reference when assessing an offer.
A simple example: how much reaches your account?
Consider a hypothetical ₹20,000 loan with a 2% processing fee deducted upfront. For illustration, assume 18% GST applies to that fee.
|
Item |
Calculation |
Amount |
|
Sanctioned loan |
Given |
₹20,000 |
|
Processing fee |
₹20,000 × 2% |
₹400 |
|
GST on fee |
₹400 × 18% |
₹72 |
|
Amount received |
₹20,000 − ₹400 − ₹72 |
₹19,528 |
The borrower receives ₹472 less than the sanctioned amount. Interest and the repayment schedule must still be assessed separately. Someone facing a ₹20,000 bill would therefore have a ₹472 shortfall under these assumptions.
This example illustrates upfront deductions only. It is not an APR calculation or a Pocketly offer, and the assumed fee and tax treatment should not be applied to an actual loan without checking its disclosures.
What should you check before using a personal loan app?
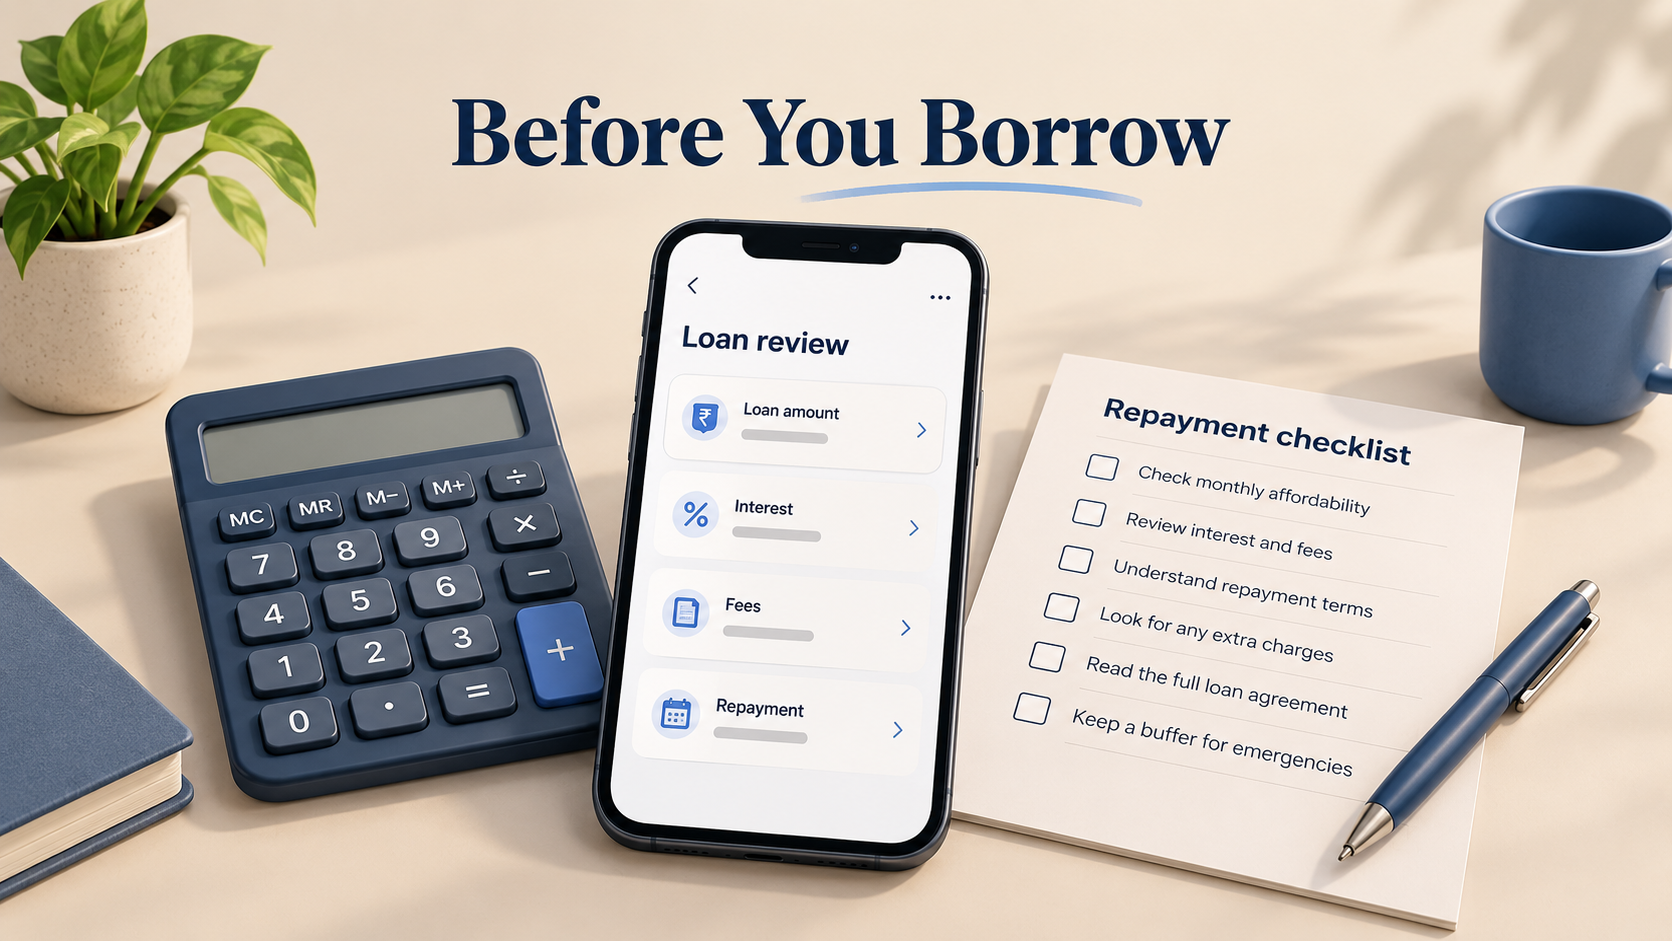
Before accepting an offer:
-
Identify the lender named in the agreement.
-
Read the KFS and compare APR across equivalent offers.
-
Confirm the amount that will reach your bank account.
-
Check every repayment amount and due date.
-
Review late-payment and early-closure terms.
-
Keep the agreement and customer support details accessible.
For Pocketly users, the platform's responsible-lending page identifies Speel Finance Company Private Limited as the RBI-registered NBFC lending through Pocketly. The page also states that borrowing costs, fees and lending terms are displayed through its application and website. Check the actual offer and agreement before accepting.
Pocketly provides a digital route for eligible applicants seeking a personal loan. Salaried and self-employed applicants should choose an amount that fits their expected cash flow and review the offered repayment terms. Sector-level growth does not establish an individual's eligibility or guarantee approval.
Does this affect existing borrowers?
The UBS analysis creates no new repayment deadline or automatic change to an existing EMI. Continue following your loan agreement and any valid lender communications.
If you receive a refinancing offer, compare the cost of closing the existing loan with the total cost of the replacement. Include fees as well as interest. A lower advertised installment alone is insufficient to establish a saving.
For anyone following unsecured credit in India, the practical question remains specific: how much will you receive, what will you repay, and can your income support the schedule?
Explore personal loan options through Pocketly - best personal loan app in india . Check your eligibility, review the offered KFS and repayment schedule, and apply for an amount suited to your needs. Approval and terms are subject to assessment.
Key takeaways
-
Published UBS analysis puts NBFC personal loan growth at about 30% year-on-year in August 2026.
-
The development is a credit-market report, with no new rule or implementation date attached to it.
-
Compare the KFS, APR, net disbursal and repayment schedule before accepting a loan.
FAQs
Did RBI announce 30% personal loan growth?
UBS analysis citing CRIF data for August 2026. It should be attributed to that reporting. RBI's loan-disclosure requirements provide separate borrower-protection context
Does 30% growth mean my approval chances increased by 30%?
No. A sector's reported lending growth cannot be converted into an individual's approval probability. Your application still requires assessment against the lender's criteria. The headline does not disclose an approval rate, the number of rejected applications or the terms any particular applicant will receive.
Are NBFC personal loans cheaper than bank loans?
The growth figures do not answer that question. Compare actual offers for the same amount and tenure, using APR and total repayments. Include upfront deductions and relevant fees. A lender category alone is insufficient to establish which offer costs less for a particular borrower.
Can self-employed people apply through Pocketly?
Pocketly has a loan offering for self-employed applicants. Eligibility and the final offer depend on the applicable assessment and verification. Before accepting, check the lender details, loan amount and repayment schedule in the app, and consider how variations in monthly income could affect timely repayment.
What should I compare when choosing an instant personal loan?
Compare the money credited to your account, APR, tenure, instalment amounts and repayment dates. Also review charges for late payment or early closure. Read the KFS before accepting, and choose an amount you can repay without relying on another loan to cover the installments.
Sources
-
Moneycontrol, "India entering strong personal loan growth cycle as unsecured credit revives: UBS," September 23, 2026, 14:18 IST. Secondary reporting of UBS analysis citing CRIF; original UBS note not independently accessed. https://www.moneycontrol.com/news/business/india-entering-strong-personal-loan-growth-cycle-as-unsecured-credit-revives-ubs-14036336.html
-
ANI via NewKerala, "India entering strong unsecured credit growth cycle; personal loans to lead acceleration: UBS," September 23, 2026. Syndicated reporting of the same UBS analysis, not independent validation of the underlying dataset. https://www.newkerala.com/news/a/india-entering-strong-unsecured-credit-growth-cycle-personal-547.htm
-
Reserve Bank of India, "Key Facts Statement (KFS) for Loans & Advances," April 15, 2024. https://www.rbi.org.in/Scripts/NotificationUser.aspx?Id=12663&Mode=0